



PW Consulting: Global PCB Epoxy Resin Market to Reach $4.9 Billion by 2032, Growing at 5.88% CAGR

Strategic Imperatives in the Worldwide Epoxy Resin for PCB Market: Navigating Growth, Volatility, and Trade Friction Through 2032
The printed circuit board (PCB) industry is currently navigating a transformation defined by the simultaneous pull of three powerful forces: the insatiable demand for high-performance electronics, the tightening grip of global trade defenses, and the relentless pressure of raw material cost volatility. Epoxy resin remains the cornerstone material for modern PCBs, dictating everything from thermal stability and dielectric performance to environmental compliance and manufacturing yield. For executives, procurement leaders, and investors, understanding the trajectory of this essential material is not merely an exercise in supply chain management; it is a prerequisite for securing competitive advantage in sectors ranging from consumer electronics to aerospace and defense.
In this context, PW Consulting has released a comprehensive new market study focused on the Worldwide Epoxy Resin for PCB Market. This strategic intelligence report provides the depth and rigor required to make informed decisions through the end of the decade and beyond. By integrating historical performance data with forward-looking scenario modeling, the study offers a clear roadmap for navigating one of the most technically demanding and geopolitically sensitive segments of the electronic materials supply chain.
Market Trajectory and the Case for Long-Term Planning
The scale of the global epoxy resin market for PCBs underscores its critical role in the broader electronics ecosystem. Recent historical data and baseline projections reveal a market that has consistently expanded, driven by the proliferation of advanced computing, automotive electrification, and the relentless miniaturization of electronic components. From a base exceeding $3,280 million in 2025, the market is projected to follow a robust upward trajectory, reaching a total revenue value of nearly $4,900 million by 2032. This expansion reflects a compound annual growth rate of approximately 5.88 percent over the forecast period, signaling a market that is growing steadily rather than experiencing erratic, cyclical swings.
However, the headline figures only tell part of the story. For strategic planners, the more telling narrative lies in the divergence between growth rates in mature regions versus high-velocity markets, and in the shifting balance of demand across application verticals. The interplay between volume expansion and value dynamics becomes particularly pronounced when analyzing how specific end-use sectors, such as communications and networking or automotive electronics, are modulating their material requirements in response to technological roadmaps and regulatory pressures.
The Technical Divergence Driving Demand Shifts
Demand for epoxy resin in PCBs is no longer uniform. As electronic devices push the boundaries of speed, density, and reliability, the material specifications required by PCB manufacturers are fragmenting into highly specialized formulations. The market is increasingly bifurcating between standard grades that serve high-volume, cost-sensitive applications and premium grades engineered for extreme performance. This bifurcation is most visible in the tension between brominated epoxy resins, which have long dominated due to their cost-effectiveness and flame retardancy, and halogen-free alternatives, which are gaining traction as environmental regulations and corporate sustainability mandates tighten globally.
Simultaneously, the push toward high-frequency, high-speed signal integrity in 5G infrastructure, advanced server base stations, and high-layer packaging substrates is accelerating the adoption of high-Tg (glass transition temperature) and specialized epoxy systems. These formulations, while typically commanding higher unit economics, are becoming indispensable for applications where thermal management, dimensional stability, and low dielectric loss are non-negotiable. The competitive dynamics within this landscape are heavily influenced by players who have vertically integrated their capabilities, from raw monomer production to finished copper-clad laminates and PCB inks.
Competitive Landscape: Vertically Integrated Giants and Regional Power Players
The competitive architecture of the global epoxy resin for PCB market is shaped by a mix of established multinational chemical corporations, regional specialists, and aggressively expanding Asian manufacturers. Market concentration remains a defining characteristic, with the top five firms accounting for a significant share of global revenue and the top three wielding a commanding portion of the market. This concentration amplifies the strategic importance of understanding not just who the players are, but how their distinct technological portfolios, geographic footprints, and capital allocation decisions are reshaping the supply-demand equilibrium.
Technology Moats and Regional Specialization
Japanese and Korean chemical giants continue to anchor the high-performance end of the spectrum. Companies such as DIC Corporation, Mitsubishi Gas Chemical Company, and Resonac Corporation have built formidable reputations around low-dielectric-loss formulations, high thermal resistance, and advanced novolac and BT resin systems tailored for multilayer PCBs, IC package substrates, and high-layer printed wiring boards. Their focus on materials for server, base station, and high-frequency applications positions them at the forefront of the technology curve, where performance premiums justify higher price points.
Epoxy Resins for Casting and Lamination Market
In tandem, Taiwanese and mainland Chinese manufacturers are executing aggressive capacity expansion strategies designed to capture volume growth and climb the value chain. Nan Ya Plastics Corporation, a vertically integrated producer of bisphenol-A based liquid and solid epoxy resins, exemplifies this approach, supplying high-Tg FR-4 materials and electronic-grade formulations with excellent electrical, mechanical, and dimensional stability for multilayer PCBs. Meanwhile, Chinese players such as Hongchang Electronics and Shengyi Technology are scaling up production of electronic-grade functional resins, halogen-free compositions, and high-Tg liquid systems, often with explicit targets in copper-clad laminates and high-end electronic materials.
Recent Strategic Shifts and Competitive Realignments
The competitive landscape has been further reshaped by a series of high-impact developments over the past year. In mid-2025, Zhuhai Hongchang commenced production on its Phase II project, adding 140,000 tons of annual capacity for liquid epoxy resin and reducing unit costs by an estimated 15 percent, thereby strengthening its cost competitiveness in the electronics and electrical sectors. By the end of 2025, the company disclosed an action plan for a Phase III project targeting an additional 80,000 tons per year of electronic-grade functional epoxy resin, alongside a high-end copper-clad laminate project, signaling a clear intent to deepen its footprint in advanced electronic materials.
Geopolitical and trade dynamics have introduced an equally potent layer of complexity. In May 2025, the U.S. International Trade Commission issued a final affirmative determination of material injury to the domestic industry from subsidized and dumped imports of epoxy resins from South Korea, Taiwan, and Thailand, effectively clearing the path for antidumping and countervailing duties. This ruling, which noted negligible imports from China and India, has immediate implications for cross-border supply chain configurations and pricing strategies. Across the Atlantic, the European Union imposed definitive anti-dumping duties on epoxy resin imports from China, South Korea, Taiwan, and Thailand in July 2025, while India followed suit in November 2025 with a five-year anti-dumping duty regime on liquid epoxy resin imports from a broad set of exporting nations.
On the commercial front, cost pressures are reverberating through the value chain. In April 2026, Mitsubishi Gas Chemical announced a 30 percent across-the-board price increase for products within its electronic materials division, including copper-clad laminates and related epoxy-based substrates, citing rising costs for copper foil, electronic cloth, and special epoxy resins. This move underscores the challenge manufacturers face in balancing input cost inflation with margin preservation, and highlights the growing importance of raw material forecasting in procurement planning.
Supply Chain Volatility and the Raw Material Matrix
No strategic assessment of the epoxy resin for PCB market is complete without a granular examination of the raw material environment. Bisphenol A, the key feedstock for most epoxy resin production, has exhibited notable price volatility, with downward pressure emerging in North America during the final quarter of 2025 as Asian offers intensified and downstream demand softened across polycarbonate and epoxy applications. Concurrently, epoxy resin prices across Asia followed a weak to bearish trend in the second half of 2025, characterized by ample supply, elevated inventories, and limited cost support from stable pricing in both bisphenol A and epichlorohydrin.
This macroeconomic backdrop creates a complex environment for procurement and production planning. On one hand, fading raw material costs can provide temporary relief and improve margin potential for resin producers and PCB fabricators. On the other hand, the protective trade measures enacted by the United States, the European Union, and India are artificially constraining supply flows in certain corridors, potentially decoupling regional price dynamics and creating arbitrage opportunities or, conversely, supply bottlenecks. Companies that fail to model these dual forces, commodity price cycles and trade policy interventions, risk suboptimal inventory positioning and unanticipated cost exposures.
Report Architecture: The Operational Intelligence Inside the Study
The Worldwide Epoxy Resin for PCB Market study is engineered to serve as a decision-making toolkit rather than a static data summary. The full report delivers a multi-layered analysis that bridges macroeconomic trends, granular segmentation, competitive profiling, and actionable supply chain intelligence. Key components of the study include:
- A detailed historical and forecast revenue analysis spanning the base year through the end of the forecast window, allowing readers to benchmark current performance against long-term trajectories and identify inflection points in the growth cycle.
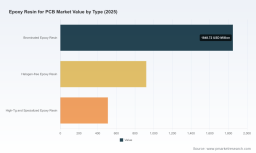
- Segment-level breakdowns that dissect market size and growth dynamics across resin types, including brominated, halogen-free, and high-Tg specialized formulations, alongside application-driven analysis spanning consumer electronics, automotive electronics, communications and networking, industrial and medical equipment, and aerospace and defense sectors.
- A comprehensive regional assessment that quantifies the relative weight of key geographies and explores the structural drivers, including manufacturing footprints, end-user demand profiles, and regulatory environments, shaping market performance in each territory.
- Deep-dive company profiles covering the leading global and regional players, with a focus on their technological capabilities, product portfolios, strategic positioning, and recent operational or financial developments that influence competitive dynamics.
- An integrated regulatory and trade analysis that maps the impact of antidumping and countervailing duty proceedings, environmental compliance mandates, and raw material feedstock trends, providing a holistic view of the forces that will shape pricing, sourcing, and market access over the forecast horizon.
- Scenario-based strategic implications designed to help stakeholders stress-test their planning assumptions against plausible shifts in demand, input costs, trade policy, and technological adoption rates.
By consolidating these dimensions into a single, rigorously sourced reference, the report enables executives to move beyond reactive management and toward proactive, evidence-based strategy formulation. Whether the objective is to evaluate capacity investment timing, optimize global sourcing architectures, benchmark against incumbent competitors, or assess the viability of entry into high-growth application segments, the study provides the granularity required to reduce uncertainty and accelerate decision velocity.
Why This Study Matters for 2026 Decision-Making
The decisions made in 2026 will set the tone for the entire forecast period. As the industry absorbs the effects of newly imposed trade remedies, responds to aggressive capacity additions in Asia, and adapts to fluctuating raw material economics, the margin for error is shrinking. Companies that continue to rely on fragmented data sources, outdated market assumptions, or generalized forecasts will face compounding strategic disadvantages. The epoxy resin for PCB market is entering a phase where differentiation will be earned through precision, not just scale.
Worldwide Epoxy Resin for PCB Market
Access to the complete market study offers a tangible advantage. It equips stakeholders with the contextual depth to interpret headline trends, the segmentation clarity to identify where growth is genuinely materializing, and the competitive intelligence to anticipate how rivals are positioning themselves. More importantly, it provides the connective tissue between seemingly disparate developments, linking a capacity expansion announcement in one region to a trade ruling in another, and connecting a raw material price dip in the third quarter to a major price increase announcement in the first quarter of the following year.
For organizations committed to capturing value in this market, the full report is not an optional reference; it is a strategic asset. The complete dataset, competitive benchmarks, and forward-looking scenario analysis are available in the full Worldwide Epoxy Resin for PCB Market study, accessible now on the PW Consulting website. Readers are invited to explore the full publication to obtain the detailed segment breakdowns, precise regional valuations, and actionable recommendations required to navigate the market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resin for PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


