



PW Consulting: Pipe Flanges Market Hits $5.34B in 2025, Projects $7.03B by 2032 at 4.01% CAGR

Navigating the 2026 Industrial Landscape: Why the Pipe Flanges Market Demands Strategic Foresight
In the complex ecosystem of industrial infrastructure, few components hold as much critical importance as the humble pipe flange. Serving as the vital connective tissue in piping systems, flanges ensure safety, pressure integrity, and modularity across sectors ranging from energy extraction to municipal water management. Yet, as we move deeper into 2026, the market for these essential components is undergoing a subtle but profound transformation. Static supply chains are giving way to dynamic networks influenced by regulatory shifts, raw material volatility, and regional industrial pivots. For executives, procurement leaders, and investors, understanding the trajectory of the worldwide pipe flanges market is no longer optional; it is a strategic imperative.
Worldwide Pipe Flanges Market
Our latest market research, spanning historical data from 2020 through the forecast period extending to 2032, offers a comprehensive lens into this evolution. This report is not merely a collection of statistics; it is a decision-support tool designed to help organizations navigate uncertainty. By analyzing revenue trends, competitive maneuvers, and regulatory frameworks, we provide the intelligence necessary to secure supply lines, optimize capital expenditure, and identify high-growth opportunities in a market projected to expand significantly over the coming years.
The Macro Trajectory: Growth Amidst Volatility
The global pipe flanges market has demonstrated resilience in the face of recent economic headwinds. Based on our analysis, the market revenue stood at approximately 5,342 million USD in the base year of 2025. Looking forward, the forecast period from 2026 to 2032 suggests a steady upward trajectory, with the market expected to reach over 7,000 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.01 percent.
While these top-line figures provide a snapshot of health, the true value lies in understanding the drivers behind the numbers. The period from 2020 to 2025 revealed patterns of recovery and adjustment, with revenue figures fluctuating as industries adapted to post-pandemic operational realities and shifting energy demands. The transition from 2025 into 2026 marks a critical inflection point. The modest growth observed in the immediate year suggests a market stabilizing after previous adjustments, setting the stage for more robust expansion in the latter half of the decade. For stakeholders, this implies that while immediate spikes may be tempered, the long-term fundamentals remain strong, driven by ongoing industrialization and infrastructure renewal projects globally.
Structural Dynamics: Segmentation and Demand Drivers
To truly leverage this market intelligence, one must look beyond aggregate revenue and understand the structural composition of demand. The market is differentiated by several key dimensions, including material composition, product type, end-user industry, and geographic region. Each of these segments presents distinct risk profiles and opportunity sets.
Material and Manufacturing Considerations
The choice of material remains a primary determinant of value within the supply chain. Carbon steel continues to hold a dominant position due to its cost-effectiveness and widespread application in standard industrial piping. However, the demand for stainless steel and alloy steel flanges is gaining momentum, driven by sectors requiring higher corrosion resistance and pressure tolerance. This shift is not merely technical; it is economic. Recent fluctuations in raw material costs have placed pressure on manufacturing margins. For instance, recent data indicates that U.S. Producer Price Index values for stainless steel have hovered significantly above historical baselines, reflecting ongoing cost volatility. Simultaneously, global steel prices in the U.S. market have shown stabilization in the low-to-mid 800s per short ton following previous fluctuations. These input cost dynamics directly influence the pricing strategies and production planning of manufacturers specializing in carbon and alloy steel flanges.
Application End-User Trends
Demand is heavily concentrated in specific industrial verticals. The oil and gas sector remains a cornerstone of consumption, leveraging flanges for upstream, midstream, and downstream infrastructure. Closely following are the petrochemical and chemical industries, which require high-integrity fittings for complex processing networks. Power generation also represents a substantial portion of the market, as utilities upgrade aging grids and explore new energy frameworks. Water and waste management sectors contribute a steady stream of demand, often driven by municipal infrastructure investments. Each of these end-users faces unique regulatory and operational pressures that dictate their procurement cycles and specification requirements.
Regional Perspectives
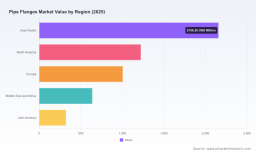
Geographically, the market is distributed across major economic zones. Asia Pacific represents a significant volume of activity, reflecting rapid industrialization and massive infrastructure projects in the region. North America and Europe maintain strong market positions, supported by mature industrial bases and ongoing maintenance replacements. Emerging regions in Latin America and the Middle East and Africa also contribute to the global total, often linked to energy exploration and development projects. Understanding the regional balance is crucial for companies looking to optimize their logistics networks or target specific export markets.
Regulatory Shifts Reshaping Compliance and Specifications
One of the most critical developments for market participants in 2026 is the regulatory landscape. Standards governing pipe flanges are not static; they evolve to address safety concerns and technological advancements. A major milestone occurred with the release of the ASME B16.5-2025 standard for Pipe Flanges and Flanged Fittings. This update, which covers nominal pipe sizes from 1/2 through 24, introduces revised pressure-temperature ratings based on updated ceiling values.
For manufacturers and engineers, compliance with the ASME B16.5-2025 edition is paramount. The standard introduces new definitions for key operational terms and adds additional ASTM materials for consideration. Furthermore, it includes a new appendix addressing minimum temperature limits and revises variables that impact design calculations. Pipe flanges must now comply with updated requirements for materials, dimensions, tolerances, marking, and testing to ensure pressure integrity in industrial piping systems. These changes ripple through the supply chain, affecting inventory planning, certification processes, and product development. Companies that fail to align their offerings with these updated specifications risk disqualification from bids or, worse, liability issues in the field. Our report details how these regulatory shifts are influencing manufacturer strategies and procurement timelines.
Competitive Landscape: Consolidations and Capabilities
The market structure is characterized by a mix of specialized manufacturers and large diversified conglomerates. Our analysis indicates a moderate level of market concentration, with the top three companies holding a combined share of approximately 16.4 percent and the top five holding around 22.85 percent. This fragmentation suggests that while there are key leaders, there is still ample room for niche players and regional specialists to thrive.
Several key companies define the current competitive arena. In the United States, Texas Flange and Federal Flange, both headquartered in Houston, remain prominent. Texas Flange specializes in ANSI, API, and AWWA pipe flanges in carbon steel, stainless steel, and alloys, catering to petrochemical, process, and waterworks industries with both standard and custom solutions. Federal Flange distinguishes itself as a leading manufacturer of ANSI and API 6A pipe flanges and fittings, with a strong emphasis on fast-turnaround capabilities and large diameter solutions. Similarly, Federal Flange and Allied International Group, with operations spanning Houston and Italy, operate as global producers and distributors of fittings, flanges, pipes, and PVF products through multiple manufacturing divisions.
On the technology and precision front, Swagelok Company supplies precision pipe flanges and fluid system components for critical applications, while Nippon Steel Corporation leverages advanced forging technology to offer precision pipe flanges for global industrial use. European and Asian players also exert significant influence. Metalfar S.p.A. in Italy and Flanschenwerk Bebitz GmbH in Germany produce high-performance steel pipe flanges and fittings for international markets. In China, Longan Flange manufactures a comprehensive range of steel flanges, including weld neck, blind, and orifice types, while Hebei Shengtian Pipe-Fitting Group Co., Ltd. stands as a major manufacturer of carbon steel pipe fittings and flanges.
Recent activity highlights the proactive nature of these competitors. In April 2026, Allied International Group participated as a major player in fittings, flanges, and pipes at TUBE Düsseldorf 2026. Similarly, Arrow Pipes participated as a Platinum partner at the same trade fair, the leading event for the tube and pipe industry. These engagements underscore the importance of face-to-face networking and product demonstration in a market where specifications and quality assurances are paramount. Additionally, the release of the ASME standard in May 2025 saw industry-wide responses, with companies adjusting their catalogs and compliance documentation to meet the new criteria.
Strategic Implications for 2026 Decision Makers
For business leaders, the insights contained in this report translate into actionable strategic directives. First, supply chain resilience must be prioritized. Given the fluctuations in raw material costs and the geographic dispersion of manufacturing hubs, relying on single-source suppliers exposes organizations to significant risk. Diversifying sourcing strategies across regions with different cost structures and regulatory environments can mitigate these vulnerabilities.
Second, compliance agility is a competitive advantage. With the ASME B16.5-2025 standard now in effect, companies that can rapidly certify their products and communicate compliance to customers will capture market share from slower-moving competitors. This requires investment in quality assurance teams and updated testing protocols.
Third, innovation in custom solutions offers higher margin opportunities. As seen with companies like Texas Flange and Federal Flange, the ability to provide custom-engineered connectors and large diameter capabilities allows manufacturers to serve specialized projects that standard off-the-shelf products cannot address. Understanding the specific needs of end-users in oil and gas or power generation can reveal gaps in the current market offerings.
Conclusion: Access the Full Intelligence
The worldwide pipe flanges market is at a junction where historical stability meets future complexity. The projection of growth to over 7,000 million USD by 2032 offers promise, but realizing value in this environment requires more than passive observation. It demands a granular understanding of material costs, regulatory updates, regional demand shifts, and competitive maneuvers.
This article has only scratched the surface of the available intelligence. To fully equip your organization for the decisions ahead, we invite you to access the complete Worldwide Pipe Flanges Market research report. Inside, you will find detailed segmentation analysis, comprehensive company profiles, deep dives into regulatory impacts, and scenario-based forecasting that goes beyond the high-level trends discussed here. Do not navigate the 2026 industrial landscape with incomplete data. Secure the full report today and turn market insight into strategic advantage.
Stainless Steel Flanges Market
For detailed analysis of this topic, please visit the official page: Worldwide Pipe Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


