



PW Consulting: NF3 and F2 Market Hits $1.52B in 2025, Projected 7.15% CAGR to $2.46B by 2032

Strategic Imperatives in the Global Nitrogen Trifluoride and Fluorine Gas Market Through 2032
In an era defined by relentless semiconductor scaling, accelerating solar photovoltaic deployment, and increasingly stringent environmental compliance frameworks, specialty fluorine chemistry has transitioned from a niche industrial input to a critical strategic enabler. Nitrogen trifluoride (NF3) and fluorine gas (F2) now sit at the intersection of advanced electronics manufacturing, clean energy infrastructure, and high-value chemical synthesis. Understanding where this market is headed, which participants will capture disproportionate value, and how regulatory and supply chain pressures will reshape procurement strategies has never been more urgent for corporate planners, procurement leaders, and capital allocators.
This comprehensive market intelligence study, anchored in a 2025 baseline and projecting through 2032, delivers the analytical rigor required to navigate one of the most capital-intensive and technically demanding specialty chemical segments in the global economy. Drawing on multi-year historical tracking, forward-looking modeling, and primary industry validation, the research translates macro growth trajectories into actionable decision frameworks for organizations operating across semiconductor fabrication, display manufacturing, solar cell production, and advanced fluorination applications.
Mapping the Macro Trajectory: From Historical Consolidation to Forecasted Expansion
The global NF3 and F2 market has demonstrated consistent upward momentum across the 2020 to 2025 historical window, expanding from approximately 1.08 billion USD in 2020 to an estimated 1.52 billion USD by 2025. This trajectory reflects sustained capital investment in advanced node semiconductor capacity, rapid scaling of next-generation display fabrication lines, and growing utilization of high-purity fluorination agents in specialty chemical workflows. The compounding effect of these demand drivers has established a durable growth foundation that extends well beyond the baseline year.
Projecting forward through the 2026 to 2032 forecast horizon, the market is expected to continue its expansion at a compound annual growth rate of 7.15 percent. Under this trajectory, total market revenue advances steadily from the mid-1.6 billion USD range in 2026 toward nearly 2.46 billion USD by 2032. This growth pace is neither speculative nor reliant on isolated technology breakthroughs; rather, it is grounded in multi-year capacity build-outs, sustained electronics output expansion, and the gradual substitution of lower-efficiency cleaning and etching chemistries with high-performance NF3 and F2 grades.
Fluorine Gas (F2) Market
Importantly, the forecast architecture reflects scenario-aware modeling that accounts for supply chain volatility, raw material price fluctuations, and evolving regulatory reporting requirements. Rather than presenting a single deterministic line, the analysis incorporates sensitivity bands around key demand drivers, allowing readers to stress-test procurement plans, capacity allocation decisions, and geographic sourcing strategies against plausible market shifts. This approach ensures that the intelligence delivered is not merely descriptive but operationally deployable for budgeting, inventory planning, and long-term supplier negotiation.
Structural Composition: How Product Types and Applications Shape Market Behavior
The market's internal architecture is defined by a clear divergence in scale and functionality between its two principal product categories. Nitrogen trifluoride dominates the overall revenue base, driven by its entrenched role in plasma-enhanced cleaning and etching processes within advanced semiconductor fabrication. Its high fluorine content, stability under controlled delivery conditions, and compatibility with ultra-high-purity handling requirements have cemented NF3 as a non-substitutable input for leading-edge wafer processing and flat-panel display manufacturing. Fluorine gas, while representing a smaller share of total revenue, occupies a strategically distinct position. Its aggressive reactivity profile supports specialized fluorination reactions in pharmaceutical synthesis, specialty chemical production, and select nuclear-related applications, creating a demand profile that is less cyclical but highly sensitive to purity grading, delivery safety protocols, and regulatory oversight.
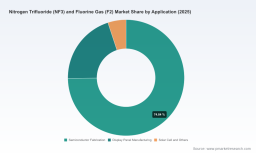
On the application side, the demand landscape is concentrated around high-technology manufacturing ecosystems. Semiconductor fabrication represents the largest consumption channel, reflecting the continuous push toward smaller node geometries, higher wafer throughput, and increasingly complex multi-patterning and high-aspect-ratio etching requirements. Display panel manufacturing constitutes the second major demand pillar, with NF3 serving critical cleaning functions across LCD and advanced display production lines. A smaller but strategically important application segment encompasses solar cell manufacturing and ancillary industrial uses, where fluorine-based chemistries support surface treatment, cleaning, and specialty synthesis workflows.
Regional distribution of market activity further illustrates the concentration of demand within advanced electronics manufacturing corridors. Asia Pacific accounts for the substantial majority of total market revenue, reflecting the dense clustering of semiconductor fabs, display production facilities, and solar manufacturing capacity across the region. North America and Europe maintain meaningful but comparatively smaller shares, supported by domestic semiconductor investments, specialty chemical synthesis demand, and regional regulatory frameworks that shape procurement and compliance strategies. The rest of the world represents a modest but gradually developing footprint, with emerging semiconductor and electronics initiatives contributing incremental demand over the forecast period.
Complementing this structural overview, the report provides granular segmentation breakdowns that map historical consumption patterns, forecast evolution, and competitive positioning across each product type, application vertical, and geographic corridor. Readers gain access to demand elasticity considerations, purity-grade differentiation dynamics, and application-specific substitution risk assessments that are essential for building resilient sourcing strategies and identifying high-margin service opportunities.
Competitive Architecture and Strategic Positioning
The NF3 and F2 market is characterized by a moderately concentrated competitive landscape, where scale advantages, purity certification capabilities, and geographic proximity to end-user manufacturing clusters heavily influence market share distribution. The top three participants collectively command a significant portion of total market revenue, while the leading five firms extend their combined footprint to an even larger share, underscoring the importance of established supply chain reliability, technical service capabilities, and long-term supply agreements in capturing premium positioning.
Solvay has embedded itself as a leading global producer of NF3 for semiconductor cleaning and F2 for chemical synthesis, maintaining production infrastructure across Europe and Asia that enables flexible regional servicing and rapid response to purity specification changes. Air Products operates as a major supplier of high-purity NF3 for the electronics industry alongside F2 serving uranium enrichment and pharmaceutical workflows, with operational facilities in the United States, China, and Taiwan that position the company at the center of key electronics and specialty chemistry corridors. Linde, leveraging its legacy capabilities in industrial gases and advanced process chemicals, provides NF3 for plasma etching in semiconductor environments and F2 for broader fluorination processes, supported by a global supply chain that includes plants in the United States and South Korea.
In the Asian electronics supply chain, Kanto Denka Kogyo has carved out a specialized role by focusing on ultra-high purity NF3 tailored for LCD and semiconductor manufacturing, with production capabilities in Japan that align closely with regional electronics demand patterns. Hyundai Steel's green gas operations contribute NF3 for flat panel display cleaning and F2 derivatives, utilizing South Korean facilities to supply regional semiconductor and display firms with integrated, geographically proximate delivery models. Pelchem, operating within the Peltzer Group, stands as a key African producer of F2 and NF3 for specialty chemicals and nuclear applications, with an export-oriented business model that extends its reach into global specialty and regulated markets. Morita Chemical Industries rounds out the competitive field by manufacturing NF3 for semiconductor and solar panel production, emphasizing high-purity grades designed for Japanese and global market requirements.
Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
The competitive dynamics among these players are shaped not only by capacity and pricing but also by recent strategic initiatives that signal long-term positioning. Air Products announced a capacity expansion at its Hsinchu, Taiwan facility in late 2024 to meet escalating semiconductor demand, reflecting a direct response to regional fab growth trajectories. Solvay introduced an upgraded high-purity F2 grade in mid-2024 aimed at advanced fluorination workflows in pharmaceutical synthesis, highlighting the ongoing premiumization of specialty fluorine products. Linde achieved ISO 45001 certification for NF3 and F2 handling at its Dalian, China plant in late 2023, reinforcing the growing importance of occupational safety and process safety certification as competitive differentiators in high-risk chemical handling environments.
The full competitive analysis within the report extends well beyond corporate profiles. It includes market share estimation frameworks, capacity expansion tracking, purity-grade portfolio mapping, regional servicing capabilities, supply agreement structures, and strategic M&A or partnership activity where relevant. Readers will gain a nuanced view of how incumbents defend share, how regional specialists capture premium niches, and where pocket opportunities may emerge for new entrants or existing players seeking to reposition their portfolios.
Market Dynamics: Raw Materials, Regulation, Trade Controls, and Logistics Friction
No strategic assessment of the NF3 and F2 market can be separated from the external dynamics that continuously reshape cost structures, delivery reliability, and compliance obligations. Raw material pricing volatility remains a persistent pressure point. Anhydrous hydrogen fluoride, a foundational input for fluorine chemistry production, experienced a 15 percent price increase to approximately 2,500 USD per metric ton in the fourth quarter of 2024, driven by supply disruptions originating in China. This movement illustrates how regional feedstock constraints can rapidly transmit into broader cost structures, affecting margin planning, contract pricing negotiations, and inventory risk management across the value chain.
Regulatory evolution adds another layer of strategic complexity. The European Union's REACH framework tightened NF3 emissions reporting requirements for semiconductor manufacturers effective January 2025, placing greater emphasis on traceability, abatement effectiveness, and environmental disclosure. For producers and end-users alike, these requirements elevate the importance of certified handling protocols, emissions tracking systems, and compliance documentation that can withstand regulatory scrutiny while supporting customer sustainability commitments.
Trade policy interventions have also begun to alter regional flow patterns. United States export controls on F2 shipments to China expanded under Bureau of Industry and Security rules in October 2024, affecting a meaningful share of cross-border deliveries and prompting reassessment of sourcing redundancy, alternative routing, and regional inventory buffering strategies. For organizations with exposure to China-linked semiconductor, display, or specialty chemical supply chains, these controls introduce both compliance risk and strategic planning complexity, particularly where F2 demand depends on cross-border material movement or where dual-use considerations intersect with industrial applications.
Logistics friction further compounds the operational challenge. The UN 1045 classification for fluorine gas mandates specialized cryogenic tanker handling, adding an estimated 10 to 15 percent to global logistics costs. This requirement influences delivery economics, regional servicing feasibility, and the relative attractiveness of localized production versus centralized distribution models. In markets where purity preservation, safety compliance, and timely delivery are non-negotiable, logistics architecture becomes a strategic variable rather than a mere operational detail.
The report integrates these dynamic factors into a cohesive analytical framework that connects raw material price sensitivity, regulatory chronology, trade control evolution, and logistics cost structures to practical decision guidance. Readers will find scenario-based cost modeling, compliance timeline mapping, and supply chain resilience recommendations that translate external volatility into structured mitigation pathways.
Why This Research Matters for 2026 Strategic Decision-Making
As organizations enter the 2026 planning cycle, the NF3 and F2 market presents a landscape where informed foresight separates resilient strategies from reactive adjustments. Procurement teams must navigate purity-grade differentiation, regional supply concentration, and rising compliance documentation demands while preserving cost competitiveness. Capital planners evaluating capacity investments or long-term supplier partnerships require forward-looking demand visibility that accounts for semiconductor node transitions, display technology evolution, solar manufacturing scaling, and specialty chemical application growth. Executives overseeing risk management need integrated understanding of raw material exposure, trade control implications, regulatory reporting obligations, and logistics cost trajectories to build strategies that hold under multiple future scenarios.
This research is designed to meet those needs by combining macro market sizing, multi-segment growth analysis, competitive positioning assessment, and dynamic external factor integration into a single, decision-ready intelligence package. It provides the structural clarity required to prioritize sourcing regions, evaluate supplier capability claims, forecast procurement cost trends, and identify where premium purity grades or localized delivery capabilities may generate margin advantage. Just as importantly, it deliberately preserves analytical depth on sensitive segmentation data, proprietary forecast models, and granular competitive measurements to ensure that readers who commit to the full study gain access to information that cannot be reconstructed from public summaries or fragmented industry commentary.
For organizations that treat specialty fluorine chemistry as a strategic input rather than a commodity purchase, the difference between adequate planning and optimized positioning lies in the quality of the underlying intelligence. This study delivers that foundation. To access the complete segmentation breakdowns, regional demand evolution, competitive share analysis, scenario-based cost and compliance modeling, and forward forecast detail across the 2026 to 2032 horizon, please visit the full report page and secure the comprehensive intelligence required to guide your 2026 and beyond strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


