



PW Consulting: Global Slaked Lime Market to Reach $9B by 2032, Driven by 4.25% CAGR

Navigating the Slaked Lime Sector in 2026: Strategic Imperatives from PW Consulting's Global Outlook
The global slaked lime market stands at a critical intersection of regulatory pressure, infrastructure renewal, and energy-driven cost volatility. As industrial operators and municipal authorities alike confront tightening emissions standards and aging water treatment networks, the demand for high-purity calcium hydroxide has evolved from a commodity consideration into a strategic supply chain priority. PW Consulting's latest Worldwide Slaked Lime Market report offers decision-makers a comprehensive, data-grounded lens into this transformation, mapping historical trajectories, projecting medium-term growth, and dissecting the competitive and operational forces that will define profitability through 2032.
For executives operating in construction, environmental services, chemical manufacturing, or public utilities, the 2026–2032 forecast period demands more than incremental planning. It requires a clear understanding of where value is concentrating, how feedstock economics are reshaping margin structures, and which regional demand centers will absorb capacity expansion. This overview distills the analytical architecture of the full study, illustrating how the report translates macro trends into actionable intelligence while preserving detailed quantitative breakdowns for subscribers who require precision in their strategic modeling.
The Macro Trajectory: Growth, Volatility, and Structural Shifts
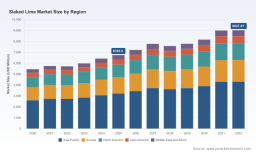
The global slaked lime market has demonstrated resilient expansion over the past half-decade, progressing from approximately USD 5,450.2 million in 2020 to an estimated USD 6,745.5 million in 2025. This historical arc reflects a compound trajectory shaped by post-pandemic infrastructure stimulus, sustained environmental compliance spending, and the gradual recovery of industrial processing volumes across multiple regions. Our baseline projection extends this momentum into a forecast window running through 2032, with the market advancing toward the USD 9 billion threshold as construction cycles mature, water and wastewater treatment mandates intensify, and flue gas desulfurization programs scale in high-emission economies.
The projected compound annual growth rate of 4.25 percent through 2032 may appear measured at first glance, but it understates the operational complexity beneath the headline figure. Medium-term growth is neither uniform nor automatic; it is being filtered through energy pricing dynamics, freight cost variability, and divergent regulatory timelines across jurisdictions. Forecasts for individual years between 2026 and 2032 reveal periods of acceleration followed by modest contractions, underscoring how capacity timing, feedstock availability, and demand-side project pipelines interact to create a non-linear revenue path. The full report unpacks these year-by-year inflection points, enabling planners to align procurement calendars, capex commitments, and product mix decisions with realistic volume expectations rather than smoothed averages.
Understanding the absolute revenue scale of the market is essential, but so is recognizing where concentration lies and where fragmentation persists. The total addressable opportunity across all forms, applications, and regions continues to expand, yet the distribution of that opportunity is highly uneven. Decision-makers who rely on aggregate growth rates without understanding the underlying structural drivers risk misallocating resources toward segments with limited margin expansion or constrained capacity absorption.
Regulatory Tailwinds and Supply-Side Constraints
Environmental regulation remains the most persistent catalyst for slaked lime demand. Stringent pollution control requirements across the United States, China, and India continue to drive procurement for hydrated lime in flue gas treatment and water and wastewater applications. As industrial emitters face tighter sulfur oxide, particulate, and heavy metal discharge limits, the consumption of high-purity slaked lime in desulfurization scrubbing systems and neutralization processes has become a compliance necessity rather than an optional upgrade. This regulatory floor provides a degree of demand certainty that insulates the market from cyclical downturns in discretionary construction or industrial processing.
Yet the supply side of the equation has grown increasingly complex. Lime kilns are inherently energy-intensive, requiring between 4.5 and 10 megajoules of fuel per kilogram of quicklime produced. Surges in natural gas and fuel oil prices accordingly translate directly into higher calcination costs, compressing margins for producers who cannot pass through cost increases or who operate with inflexible contract structures. In early 2026, quicklime feedstock pricing reflected significant geographic divergence, with benchmarks reported at approximately USD 156 per metric ton in China, USD 170 per metric ton in the Netherlands, and USD 128 per metric ton in the United States. These differentials influence downstream slaked lime economics, shaping regional competitiveness, import-export dynamics, and the viability of localized versus centralized production models.
Compounding these cost pressures, geopolitical tensions in early 2026 disrupted energy flows and logistics corridors, pushing freight rates higher by roughly 15 to 25 percent and adding surcharges to lime-related products. For buyers and sellers alike, the result has been a market where delivery reliability, regional inventory positioning, and contract hedging have become as strategically important as unit pricing. The report examines how these energy, logistics, and regulatory layers interact, providing a framework for evaluating risk exposure across procurement geographies and supply routes.
Regional and Application Dynamics: Where Demand Converges
Demand for slaked lime is distributed across a diverse set of end-use environments, each with distinct volume drivers, specification requirements, and procurement cycles. At a high level, the market's application footprint spans water and wastewater treatment, environmental protection through flue gas desulfurization, construction and infrastructure, chemical and industrial processing, and agriculture or soil treatment. The relative weight of these segments reflects broader economic and policy priorities: environmental compliance and municipal water security consistently anchor baseline demand, while construction activity and industrial processing volumes introduce cyclical sensitivity.
Regionally, the market's footprint is anchored by the Asia Pacific region, followed by Europe and North America, with Latin America and the Middle East and Africa representing additional but comparatively smaller demand pools. This distribution is not static. Shifts in municipal infrastructure investment, industrial relocation patterns, and the pace of environmental regulation implementation are gradually reweighting demand geography. Capacity additions in one region can alter trade flows, while localized feedstock availability and energy cost structures determine which production hubs remain competitive over time.
The full report provides granular segmentation that maps these regional and application dynamics in detail, allowing readers to assess which end-use categories are expanding most rapidly, how form preferences vary by region, and where regulatory or infrastructure projects are likely to generate near-term procurement spikes. Access to this level of segmentation is essential for companies evaluating market entry, capacity allocation, or product specialization strategies.
The Competitive Landscape: Scale, Focus, and Recent Moves
The slaked lime sector features a mix of globally integrated producers and regionally focused manufacturers, with consolidated players commanding significant but not overwhelming market share. The top three competitors account for approximately 18.4 percent of total market revenue, while the top five reach roughly 26.15 percent. This concentration profile indicates a market where scale matters for cost efficiency and distribution reach, yet where regional specialists and niche-grade producers retain meaningful positioning through localized service, product customization, and specialized application expertise.
Several established players illustrate the strategic directions shaping the competitive field. Carmeuse, headquartered in Belgium, operates as a global leader in lime products spanning high-calcium and dolomitic hydrated lime for steelmaking, environmental, construction, and chemical applications, with production facilities distributed across North America, Europe, and Asia. Lhoist Group, also based in Belgium, operates in more than 25 countries and supplies high-purity grades for water treatment, flue gas desulfurization, construction, and industrial uses, maintaining significant global production volumes. Graymont Limited, headquartered in Canada, has reinforced its North American and Asia-Pacific presence by focusing on construction, environmental, and industrial markets while pursuing capacity additions through acquisitions.
In the United States, Mississippi Lime Company stands as a key manufacturer of high-calcium quicklime and hydrated lime for chemical, industrial, environmental, and construction sectors, operating multiple plants with an emphasis on high-purity and specialty grades. United States Lime & Minerals, Inc. produces quicklime and hydrated lime from limestone quarries for construction, metals, environmental, oil and gas, and agriculture applications across multiple states. Complementary producers such as Nordkalk in Finland, Linwood Mining & Minerals Corporation, Cheney Lime & Cement Company, Pete Lien & Sons, Inc., Cape Lime in South Africa, Sigma Minerals Ltd in India, Valley Minerals LLC, Cornish Lime in the United Kingdom, Brookville Manufacturing in Canada, and Minerals Technologies Inc. in the United States further enrich the competitive fabric, each contributing regional depth, specialized grades, or application-specific capabilities.
Recent corporate activity underscores how companies are positioning for the 2026–2032 cycle. In February 2026, Lhoist Group commissioned an expanded hydrated lime production facility in North America to support growing demand from water treatment and flue gas desulfurization markets. Earlier, in January 2026, Graymont Limited announced a strategic partnership with a leading municipal water authority for the long-term supply of high-purity hydrated lime supporting water treatment plant upgrades, following its September 2025 acquisition of a lime processing facility in Malaysia that added significant quicklime and hydrated lime production capacity. In January 2025, Mississippi Lime Company committed to constructing a state-of-the-art sustainable kiln at its Bonne Terre, Missouri facility, signaling the industry's increasing attention to energy efficiency and environmental performance as competitive differentiators.
Worldwide Slaked Lime Market
These developments reflect a broader pattern: producers are aligning capacity investments and partnership structures with demand visibility in water and environmental applications, while simultaneously pursuing operational efficiencies that mitigate energy cost exposure. The report analyzes these moves not as isolated announcements but as indicators of how competitive advantage is being redefined through regional capacity timing, feedstock integration, and application specialization.
What the Full Report Delivers
PW Consulting's Worldwide Slaked Lime Market study is structured to support multiple layers of strategic decision-making. Beyond the macro revenue trajectory and forecast horizon, the report provides a detailed segmentation architecture covering product forms, end-use applications, and geographic markets. This structure enables readers to evaluate not just how large the market is, but how value is distributed across powdered slaked lime, slurry or milk of lime, and granular slaked lime; across environmental, construction, water treatment, chemical, and agricultural applications; and across the regional demand centers that shape procurement and logistics strategies.
The competitive analysis extends beyond corporate profiles to assess positioning, capacity footprints, and strategic timing. Readers gain insight into how leading producers are balancing scale with specialization, how recent facility expansions and acquisitions alter regional supply dynamics, and where fragmentation still creates opportunities for focused entrants or niche-grade suppliers. The inclusion of recent industry developments, from commissioning events to partnership announcements and sustainable production commitments, anchors the competitive assessment in real-time operational realities rather than static positioning maps.
Equally important, the study integrates supply-side dynamics that directly affect commercial planning. Energy intensity, feedstock pricing divergence, freight cost volatility, and regulatory implementation timelines are examined as interconnected variables rather than isolated headwinds. This integrated perspective helps procurement leaders, production planners, and market strategists evaluate where cost pressure is structural versus cyclical, where contractual flexibility can protect margins, and where capacity timing can create temporary windows of advantage or risk.
Worldwide Hydrated Lime Market
The full report also includes historical data spanning 2020 through the base year of 2025, providing a calibrated baseline against which forecasts can be tested. This historical context is essential for validating trend assumptions, understanding the magnitude of post-stimulus recoveries, and identifying whether current growth patterns reflect durable demand expansion or temporary cyclical rebounds.
Strategic Takeaways for 2026 Decision-Makers
For executives navigating the slaked lime sector in 2026 and beyond, several strategic imperatives emerge from the study's analytical framework:
- Recognize that regulatory-driven demand provides a durable baseline but does not eliminate volatility in construction, industrial processing, and freight-exposed segments.
- Model procurement and production decisions against year-by-year forecast variation rather than relying on smoothed long-term growth rates, especially where energy and logistics costs can shift margin profiles quickly.
- Assess regional competitiveness through the combined lens of feedstock pricing, energy cost structures, and freight exposure, since these variables increasingly determine which production hubs can compete on total delivered cost.
- Evaluate partnership and capacity strategies against visible demand pipelines in water treatment, flue gas desulfurization, and infrastructure projects, where multi-year procurement visibility can justify targeted capacity investments or long-term supply agreements.
- Monitor competitive moves not only by announced capacity additions but by the timing of commissioning, the specificity of application focus, and the operational efficiency investments that will determine cost leadership over the forecast period.
The slaked lime market is no longer a straightforward commodity play. It is a sector where regulatory mandates, energy economics, logistics constraints, and regional infrastructure priorities converge to shape both demand and competitive positioning. PW Consulting's Worldwide Slaked Lime Market report equips stakeholders with the analytical depth required to navigate that complexity, translating broad market trajectories into segment-level insights, competitive intelligence, and supply-side context that can be directly incorporated into commercial and operational planning.
For organizations that require precise segmentation data, region-specific demand breakdowns, form-level revenue splits, and detailed competitor benchmarking, the complete study provides the full quantitative architecture behind these strategic observations. Access to the complete dataset and analysis ensures that planning assumptions are grounded in validated market structure rather than aggregated approximations, enabling sharper execution across procurement, capacity, and market development decisions throughout the 2026–2032 forecast window.
For detailed analysis of this topic, please visit the official page: Worldwide Slaked Lime Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


