



PW Consulting: Worldwide Dairy-Free Infant Formula Market Hits $2.65 Billion in 2025, Projected to Hit $4.21 Billion by 2032

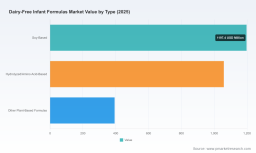
Global Dairy-Free Infant Formulas Market: Strategic Intelligence for 2026 and Beyond
The worldwide dairy-free infant formulas market stands at a critical inflection point in 2026. Driven by rising consumer awareness of infant sensitivities, evolving regulatory frameworks, and sustained demand for clean-label nutrition, this segment has transformed from a niche alternative into a structural pillar of the broader infant nutrition industry. Our latest comprehensive market research provides decision-makers with the analytical rigor required to navigate rapid category evolution, allocate capital efficiently, and position portfolios against compounding structural shifts.
Worldwide Dairy-Free Infant Formulas Market
Between 2020 and 2025, the market expanded from approximately $1.90 billion to $2.65 billion, reflecting a compound annual growth trajectory that has consistently outpaced conventional infant formula categories. Forward-looking projections through 2032 indicate sustained momentum, with the market anticipated to exceed $4.2 billion by the end of the forecast horizon. The intervening years will be shaped by evolving product architecture, channel migration, and regulatory recalibration. Understanding the mechanics behind these movements is no longer optional; it is a prerequisite for market leadership.
Why This Research Matters for 2026 Strategic Planning
Corporate strategy in infant nutrition requires more than high-level trend narratives. Executives evaluating product portfolio expansions, supply chain adjustments, or regional market entries need granular, actionable intelligence that connects macro market behavior to operational decision-making. This report is engineered to serve as a centralized strategic reference, translating complex market signals into structured insights that can be operationalized across R&D, commercial, regulatory, and M&A functions.
The analysis isolates the forces that will define competitive positioning throughout the forecast period. These include the maturation of soy-based formulations, the scientific and regulatory pathway evolution for hydrolyzed and amino acid-based alternatives, and the emergence of novel plant-based architectures that appeal to clean-label and flexitarian caregiver preferences. Each of these vectors carries distinct implications for formulation strategy, manufacturing complexity, and consumer trust.
Equally important is the shift in distribution dynamics. Retail infrastructure continues to recalibrate around omnichannel access, with traditional physical retail channels adapting to digital-native purchasing behaviors. The report dissects how these channels interact with product positioning, pricing architecture, and consumer discovery patterns, enabling brands to align go-to-market strategies with actual purchasing behavior rather than legacy assumptions.
Market Structure and Growth Architecture
The market's expansion has been supported by durable demand drivers rather than short-lived trend cycles. Caregivers increasingly seek formulas that address milk protein sensitivity, lactose intolerance, and broader digestive sensitivities, while simultaneously demanding ingredient transparency and nutritional completeness. This convergence has sustained category relevance across varying economic conditions and demographic segments.
Revenue composition reflects a diversified product landscape. Soy-based architectures represent a substantial portion of the dairy-free formula universe, leveraging established manufacturing pathways and recognized nutritional profiles. Hydrolyzed and amino acid-based formulations constitute a parallel pillar, addressing medically adjacent sensitivities and specialty nutritional requirements. A third, rapidly evolving segment encompasses other plant-based formulas that rely on non-soy botanical inputs and whole-food-inspired ingredient strategies. Each architecture carries distinct formulation requirements, cost structures, and consumer perception profiles.
Geography further shapes market behavior. Regional demand patterns are influenced by differing regulatory traditions, cultural attitudes toward plant-based infant nutrition, and the maturity of specialty retail ecosystems. North America, Europe, Asia Pacific, and Rest of World markets each exhibit distinct adoption curves and distribution characteristics. The report examines these differences not as isolated snapshots, but as interconnected elements of a global supply and demand system that multinational and regional players must navigate simultaneously.
Pricing dynamics and market concentration add further strategic complexity. A concentrated participant base holds meaningful share, which shapes competitive responses, innovation pacing, and barrier-to-entry calculations. At the same time, private-label manufacturing and store-brand expansion have introduced additional price architecture variability across channels. These structural factors influence margin expectations and portfolio positioning decisions in ways that must be modeled explicitly rather than assumed.
Competitive Landscape: Navigating Portfolio, Regulation, and Positioning
The competitive environment is defined by a mix of global incumbents, scientifically oriented specialists, and emerging clean-label innovators. Each participant approaches the dairy-free infant formula category through a distinct strategic lens, and understanding these differences is essential for evaluating partnership opportunities, benchmarking positioning, and anticipating competitive responses.
Abbott Laboratories continues to anchor its presence with established soy-based offerings that address milk protein sensitivity and lactose intolerance, leveraging scale, clinical heritage, and broad distribution access. Reckitt Benckiser, through its Mead Johnson heritage, maintains a strong position with plant-based soy formulations designed for sensitive digestive systems, reinforced by global marketing infrastructure and long-standing caregiver recognition. Nestlé S.A. approaches the category through a diversified infant nutrition portfolio, integrating dairy-free and plant-blend options that address sensitivities while preserving access to wider nutritional platforms. Danone S.A. similarly deploys plant-blend and specialty formulations across premium and therapeutic-adjacent positioning, using its Nutricia and related brand architecture to reach caregivers seeking hybrid dairy and plant combinations aligned with vegetarian or flexitarian preferences.
Beyond the large multinationals, a distinct set of specialists is shaping category innovation. Else Nutrition Holdings Inc. has moved toward whole-food plant-based, non-soy, non-dairy formulations built on almonds, buckwheat, and tapioca, targeting caregivers who prioritize clean-label composition and avoid both dairy and soy. Sprout Organic and Earth's Best extend the organic and plant-based frontier, with Earth's Best reinforcing non-GMO and vegan-sourced DHA positioning within an organic soy-based dairy-free framework. Perrigo Company plc plays an important structural role through store-brand and private-label manufacturing, ensuring that regulatory-compliant dairy-free and soy-based formulas remain accessible across retail ecosystems. Hain Celestial Group contributes organic and plant-based options that align with broader natural-ingredient consumer expectations, while Bobbie emphasizes organic formulation principles with plant-based elements designed for dairy-sensitive needs.
Recent Developments Shaping Strategic Decision-Making
The market environment in 2025 and early 2026 has been influenced by regulatory developments, product launches, and supply-chain events that directly affect category planning. These developments are not isolated news items; they are indicators of the operating conditions businesses will face throughout the forecast period.
Regulatory progress has been particularly consequential. In early 2026, the FDA listed Protein Efficiency Ratio rat bioassay study guidance as active, reinforcing a scientific validation pathway relevant to novel plant-based, non-soy infant formula architectures. For companies pursuing alternative protein systems, this signals a more defined route toward US commercialization and reduces ambiguity around evidence expectations. At the same time, broader regulatory momentum continues to reshape category boundaries. The FDA's uniform compliance dates for food labeling regulations spanning 2025 through 2026, together with guidances on allergen labeling and plant-based alternative labeling, directly affect how dairy-free claims and nutrient statements can be communicated. These rules influence packaging strategy, claim architecture, and consumer messaging across all participants.
Operation Stork Speed, launched in 2025, has added another regulatory layer by initiating updates to infant formula nutrient regulations that had remained largely unchanged since the 1980s and 1990s. Protein quality pathways are especially relevant for novel plant-based, non-soy formulations, making this initiative a key variable for R&D planning and clinical substantiation strategies. In parallel, US Congressional appropriations for fiscal year 2026 include report language directing the FDA to streamline regulatory pathways specifically for plant-based, non-soy, non-dairy infant formulas. This legislative signal expands the strategic conversation from compliance alone to potential category expansion and faster time-to-market for alternative architectures.
Supply-side events have also reinforced the importance of resilience planning. In late 2025, broad recalls involving infant formulas emerged due to cereulide toxin concerns linked to an ARA oil supplier, affecting multiple major manufacturers across several countries. While not limited to dairy-free products, the episode highlighted the interconnected nature of ingredient sourcing, quality assurance, and global recall exposure. For dairy-free formula strategists, the event underscores the need for robust supplier qualification, formulation redundancy, and transparent crisis communication frameworks.
On the commercial side, recent product activity continues to signal category vibrancy. New launches and retail rollouts in adjacent infant formula spaces indicate ongoing investment in the broader category, even when specific variants are not dairy-free. Such activity influences shelf visibility, caregiver trial behavior, and competitive intensity, all of which shape go-to-market calculations for dairy-free portfolios.
Report Scope: What Decision-Makers Will Gain
This market research is designed to provide an integrated view of the category rather than a fragmented collection of statistics. The report combines historical performance analysis, forward-looking forecasting, and structural decomposition to support strategy formulation across multiple functional domains.
The core content includes:
- A comprehensive market sizing framework covering the historical period and the full forecast horizon, enabling revenue trajectory modeling and baseline scenario planning.
- Segment-level analysis by product type, distribution channel, and region, structured to reveal where growth is concentrating and how category architecture is evolving.
- Competitive profiling of leading participants, with attention to product strategy, brand positioning, and the strategic implications of recent corporate and regulatory developments.
- Assessment of market concentration dynamics and their implications for pricing power, entry barriers, and incumbent response patterns.
- Regulatory and labeling context relevant to dairy-free claims, plant-based nomenclature, nutrient compliance, and novel protein validation pathways.
- Channel behavior analysis that connects retail and online purchasing patterns to product positioning and commercial execution.
- Strategic FAQs and operational considerations that translate technical and regulatory detail into practical decision-making guidance.
By linking quantitative structure with qualitative industry context, the report enables leadership teams to evaluate opportunity sizing, risk exposure, and strategic fit without relying on superficial trend assumptions.
Strategic Imperatives for the Forecast Period
As the market advances through the remainder of the decade, several strategic imperatives will separate adaptive organizations from those that underperform relative to category momentum.
First, formulation strategy must balance nutritional credibility with consumer-facing clarity. Dairy-free infant formulas operate in a category where caregivers scrutinize ingredient origin, protein quality, and digestive compatibility. Products that align scientific substantiation with clean-label expectations will have an advantage in trust formation, particularly as alternative protein architectures gain regulatory and commercial traction.
Second, distribution strategy should be treated as a growth lever rather than a fulfillment endpoint. The interaction between physical retail, online channels, and specialty outlets increasingly determines product discovery, repeat purchase behavior, and price perception. Brands that align channel mix with target caregiver behavior will be better positioned to convert demand into durable share.
Goat Milk Infant Formula Market
Third, regulatory readiness should be embedded into product development timelines. The evolving FDA guidance environment, nutrient regulation updates, and legislative signals around plant-based, non-soy pathways all affect time-to-market, claim eligibility, and market access. Organizations that integrate regulatory scenario planning into R&D and commercial planning will reduce execution risk and improve responsiveness to policy shifts.
Fourth, supply-chain resilience will remain a differentiator. Ingredient sourcing, supplier qualification, and recall readiness are no longer back-office concerns. They are strategic capabilities that influence brand trust, inventory continuity, and market reputation. As global supply networks remain exposed to quality and contamination risks, proactive resilience planning will be a competitive advantage.
Finally, portfolio architecture should reflect both specialization and scalability. Dairy-free infant formulas can serve broad sensitivity-driven demand, specialty nutritional needs, and premium clean-label positioning. The most effective portfolios will combine these layers without diluting focus, ensuring that each product architecture supports a clear consumer proposition and a defensible commercial position.
Conclusion
The worldwide dairy-free infant formulas market will continue to expand, but growth alone will not guarantee competitive success. The strategic winners in 2026 and beyond will be those who understand the interaction between product architecture, regulatory evolution, channel behavior, and supply-chain resilience. Our latest market research provides the structured intelligence required to make those decisions with confidence.
The full report Contains the detailed segmentation analysis, forecast modeling, competitive assessments, and operational context needed to translate category momentum into concrete business strategy. We invite executives, strategy teams, and commercial leaders to access the complete market intelligence and use it to shape portfolio decisions, investment priorities, and market-entry planning for the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy-Free Infant Formulas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


