



Global Metal Facade Cladding Market to Reach $35,620.5M by 2032, Growing at 5.42% CAGR: PW Consulting

Navigating the Metal Facade Cladding Market: Strategic Intelligence for 2026 and Beyond
The global built environment is undergoing a profound transformation, driven by sustainability mandates, urban densification, and an unyielding demand for architectural performance. In this shifting landscape, metal facade cladding has evolved from a purely aesthetic choice to a critical component of building envelope engineering. As organizations align their capital allocation and product strategies for the 2026–2032 horizon, understanding the structural forces shaping this sector is no longer optional. Our newly released Worldwide Metal Facade Cladding Market research delivers a definitive, data-grounded roadmap for executives, developers, and material strategists seeking to navigate the next phase of growth.
Market Trajectory: A Foundation of Steady Expansion
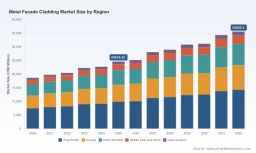
The sector has demonstrated remarkable resilience over the pastHalf-decade, even as macroeconomic volatility and supply chain recalibration tested industry benchmarks. Historical tracking from 2020 through 2025 reveals a consistent upward trajectory, with total market revenue climbing from approximately 18.65 billion USD to a validated base year valuation of 24.62 billion USD in 2025. This expansion reflects not only recovery from pandemic-era construction slowdowns but also a structural pivot toward high-performance envelope systems that integrate thermal efficiency, weather durability, and modern design language.
Looking forward, the forecast window through 2032 points to sustained momentum. Market modeling indicates a compound annual growth rate of 5.42 percent, positioning the sector to surpass the 25.17 billion USD threshold by 2026 and continue its ascent toward the 35.62 billion USD range by the end of the forecast period. For decision-makers, this trajectory signals more than incremental opportunity; it highlights a market where early positioning in product innovation, regional capacity planning, and value-engineered cladding architectures will compound into long-term competitive advantage.
It is worth noting that this growth is not uniform across every segment. Variations in regional construction pipelines, material substitution dynamics, and application-specific demand create pockets of accelerated opportunity alongside more moderate gains. Our research deconstructs these divergences in detail, enabling stakeholders to allocate resources where the probability of ROI is highest rather than relying on aggregate averages.
Core Segment Architecture and Demand Drivers
The market's structural composition reveals distinct demand centers that shape pricing power, manufacturing footprints, and go-to-market strategies. Material technology remains the foundational axis of competition. Aluminum-based systems continue to command the largest share of the material landscape, reflecting their balance of formability, corrosion resistance, and compatibility with advanced coating technologies. Galvanized steel and stainless steel maintain strong relevance in applications where structural load, longevity, or industrial-grade resilience are paramount. Zinc and copper-based solutions occupy specialized niches, often anchored by premium architectural projects where patina development, weatherability, and bespoke fabrication justify higher specification costs.
Application segmentation further clarifies where value is being captured. Commercial building projects represent the most substantial demand pool, driven by mixed-use developments, corporate campuses, retail modernization, and high-rise envelope retrofits. Residential construction constitutes a significant secondary channel, particularly in markets experiencing housing intensification and a shift toward multi-family structures that leverage metal cladding for both curb appeal and weatherproofing performance. Industrial facilities round out the application spectrum, with demand emerging from warehouses, processing plants, and specialized infrastructure that require cladding solutions capable of withstanding harsh environmental exposure and meeting stringent maintenance cycles.
On a regional basis, the demand geography reflects a layered story of maturity and emergence. Asia Pacific stands out as a volume-intensive region, fueled by rapid urbanization, large-scale commercial development, and expanding manufacturing infrastructure. Europe presents a different dynamic, characterized by stringent energy performance codes, deep renovation pipelines, and a strong preference for cladding systems that align with circularity and low-carbon objectives. North America contributes a mature but steadily expanding base, shaped by institutional procurement standards, fire-safety regulations, and a growing appetite for modular and prefabricated cladding assemblies. The Middle East and Africa, along with Latin America, represent shorter but high-velocity opportunity corridors, often tied to landmark projects, hospitality expansions, and government-led infrastructure programs.
Regulatory Tailwinds and Industry Dynamics
Policy and performance standards are increasingly dictating the pace and direction of cladding adoption. Building energy codes and certification frameworks such as LEED and BREEAM have woven facade efficiency directly into project scoring mechanisms, incentivizing developers to specify metal cladding systems that reduce operational energy consumption through superior thermal bridging control, reflectivity optimization, and integrated insulation compatibility. In parallel, revisions to the EU Energy Performance of Buildings Directive continue to promote high-efficiency envelopes and zero-emission building targets, reinforcing the strategic relevance of durable metal cladding in both new builds and deep retrofits across European markets.
Safety regulations are exerting an equally powerful influence. Following years of heightened scrutiny on combustibility and fire propagation in high-rise construction, the industry has pivoted toward fire-resistant and low-maintenance cladding materials. This shift is reshaping product specification patterns, accelerating demand for certified composite panels, coated metal substrates, and proprietary testing protocols that satisfy localized building codes. The regulatory environment is not merely a compliance hurdle; in many markets, it is becoming a filter that rewards manufacturers and specifiers who can articulate verifiable performance, documented testing, and lifecycle durability.
Raw material dynamics add another layer of complexity to the operating environment. Aluminum sheet prices in North America posted a notable quarter-over-quarter increase in late 2025, reflecting tight supply conditions against steady demand. These cost pressures have already begun to flow through to downstream pricing strategies. For instance, PAC-CLAD announced a 10 percent price adjustment on aluminum sheets, coils, and panels effective January 1, 2026, citing raw material input inflation as a primary driver. Such developments underscore the importance of procurement hedging, long-term supplier agreements, and design-for-cost engineering that can preserve margin integrity without compromising spec quality.
Competitive Landscape and Strategic Positioning
The competitive architecture of the metal facade cladding market is defined by a cohort of internationally active manufacturers that blend material science expertise with architectural service capabilities. Kingspan Group continues to emphasize insulated metal panels and high-performance cladding systems engineered for energy efficiency and durability across commercial and industrial contexts. Alucobond, operating under 3A Composites, has built its reputation on aluminum composite panels that deliver lightweight profiles, fire resistance, and customizable finishes suitable for contemporary architectural expression worldwide.
Arconic Corporation remains a formidable presence in high-rise facade applications through its Reynobond and Reynolux product families, which combine advanced coatings and structural performance with aluminum composite and solid metal cladding systems. Tata Steel Limited supplies Colorcoat and other pre-finished steel and aluminum products targeting sustainable building envelope solutions, particularly in markets where locally optimized supply chains can offer cost and logistics advantages. Alucoil contributes specialized aluminum composite and lacquered aluminum materials designed for building facades, transport, and industrial cladding applications, reinforcing the broader European manufacturing base.
ALPOLIC, from Mitsubishi Chemical, extends the metal composite material category with solutions widely recognized for aesthetic versatility and proven performance in demanding exterior environments. ArcelorMittal leverages its building envelope division to offer steel-based cladding panels and architectural systems that align with large-scale structural programs. PAC-CLAD, from Petersen Aluminum, manufactures architectural metal wall panels across steel and aluminum, including composite and corrugated configurations tailored to commercial facade requirements. Zahner occupies a distinct high-end segment, specializing in custom-fabricated metal facades that span stainless steel, copper, zinc, and aluminum for artistic and premium architectural projects. BlueScope Steel reinforces the pre-painted steel category through its COLORBOND product line, providing durable cladding options for commercial and industrial construction. Reynaers Aluminium advances aluminum facade and curtain wall systems, including cladding panels optimized for energy-efficient building envelopes. Americlad rounds out this competitive field by focusing on architectural metal cladding and fabrication, delivering wall panel systems, composite panels, and modular facade solutions.
Taken together, these players illustrate a market where differentiation is increasingly achieved through coating technology, fire-performance certification, fabrication agility, and envelope integration expertise rather than material commodity alone. Concentration metrics indicate a moderately fragmented landscape, with the top three players accounting for approximately 18.4 percent of market revenue and the top five reaching roughly 24.15 percent. This structure suggests ample room for mid-tier specialists and regional leaders to capture share through niche engineering, localized service networks, and specification partnerships, while also rewarding scaled incumbents who can consolidate channel reach and technical support.
What the Research Delivers for 2026 Decision-Making
Our Worldwide Metal Facade Cladding Market study is structured to convert market intelligence into executable strategy. Beyond the headline growth trajectory, the report maps the interrelationships between material innovation, application demand, regional construction activity, and regulatory pressure. It provides a granular view of how cladding systems are specified across commercial, residential, and industrial programs, and where procurement teams are increasingly prioritizing performance verification, lifecycle cost modeling, and supply continuity over lowest-first-cost sourcing.
Decision-makers will find direct utility in several areas. For product and engineering leaders, the research identifies specification trends that are reshaping substrate selection, coating preferences, and panel system configurations, helping teams prioritize R&D and portfolio investments. For commercial and strategy teams, it examines pricing dynamics, including the downstream effects of raw material movements and how leading manufacturers are recalibrating price architecture in response to input cost volatility. For market-entry and expansion teams, the regional and application breakdown clarifies where demand is structurally supported by construction pipelines, regulatory incentives, or retrofit activity, enabling more disciplined geographic prioritization.
Worldwide Wall Cladding Market
The report also evaluates competitive positioning and capability gaps across the supplier base, providing a reference framework for benchmarking service offerings, certification portfolios, and fabrication capabilities. By integrating industry context such as evolving energy directives, fire-safety requirements, and sustainability certification pressures, the analysis helps executives anticipate where future specification barriers and opportunities will emerge. Recent market signals, including the 2025 aluminum pricing adjustments and upcoming sector exhibitions that convene installers, fabricators, and architects, are treated as actionable indicators of how procurement behavior and channel dynamics are evolving heading into 2026.
Crucially, the study does not stop at descriptive trends. It isolates the variables that will determine which organizations can expand margins, secure specification loyalty, and scale manufacturing or fabrication capacity in alignment with demand growth. The structural insights are designed to support capital planning, M&A screening, supplier negotiations, and product roadmap decisions with a level of specificity that generic industry summaries cannot match.
Why Access the Full Analysis Now
The transition from aggregate market sizing to segment-level execution requires a comprehensive intelligence asset that connects demand drivers, material economics, regulatory pressure, and competitive capability into a single strategic lens. The Worldwide Metal Facade Cladding Market report is built for exactly that purpose. It equips executives with the evidence base needed to align product development, pricing strategy, regional focus, and partnership decisions with the realities of the 2026–2032 market environment.
The full research contains the detailed segmentation data, regional revenue mappings, application-level demand breakdowns, competitive benchmarking frameworks, and scenario-based growth indications that underpin the strategic observations discussed here. For teams preparing procurement forecasts, specification roadmaps, capacity investments, or market-entry evaluations, the complete dataset and analytical commentary provide the empirical foundation necessary for confident decision-making.
To access the complete analysis, including all segmentation dimensions, competitive profiles, and forward-looking scenario detail, visit the source page for this research. The full report delivers the depth required to convert market visibility into operational advantage.
Worldwide Metal Facade Cladding Market
For detailed analysis of this topic, please visit the official page: Worldwide Metal Facade Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


