



PW Consulting: Worldwide Maskless Lithography Market Hits $1.12B in 2025, Projects 8.76% CAGR to 2032

The Strategic Pivot to Maskless Lithography: Navigating a Defining Era for Precision Manufacturing
The evolution of semiconductor packaging, microelectronics fabrication, and advanced microfabrication has reached an inflection point. As node scaling yields diminishing returns and application complexity accelerates across artificial intelligence, high-performance computing, and next-generation sensor domains, the industry is actively repositioning its tooling architectures. Among the most consequential shifts is the accelerated adoption of maskless lithography machines, which are transitioning from niche prototyping assets to strategic enablers of flexible, high-mix, and rapidly iterating production environments.
Our latest Worldwide Maskless Lithography Machine Market study is designed not as a static size-and-forecast exercise, but as a decision-support framework for executives navigating technology transitions, capacity allocation, and competitive positioning through 2032. The analysis synthesizes historical demand trajectories, forward-looking adoption curves, competitive intensity metrics, and the operational realities shaping procurement and R&D roadmaps in 2026 and beyond.
A Market Architecture Built for Scale and Complexity
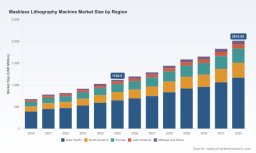
Reflecting the cumulative effect of four years of structural expansion, the global market for maskless lithography systems advanced from approximately USD 678.45 million in 2020 to a base-year valuation of USD 1,120.5 million in 2025. This progression underscores a sustained institutional commitment to digital patterning technologies that reduce dependency on physical reticles, compress design-to-fabrication cycles, and support the iterative demands of advanced packaging and micro-device development.
Worldwide DMD Maskless Lithography Machine Market
Looking ahead, the forecast period from 2026 to 2032 maps a trajectory of compounding value creation, with projected revenue reaching an estimated USD 1,195.91 million in 2026 and ascending toward USD 2,016.98 million by 2032. This expansion is anchored by a forecast CAGR of 8.76 percent, a rate that reflects both organic technology maturation and the broadening of addressable use cases across research, commercial production, and specialized manufacturing workflows.
For enterprise strategists, this macroeconomic arc is only the starting point. The real strategic value lies in understanding how growth is distributed across operational modes, how technology pathways are bifurcating between throughput-oriented and resolution-oriented architectures, and where concentration patterns indicate durable competitive advantages versus fragmented, price-sensitive segments. Our report dissects these structural dynamics without reducing them to surface-level aggregates, enabling precise capital allocation decisions rather than generalized market assumptions.
Beyond Headline Forecasts: The Operational Core of the Study
A market of this complexity cannot be managed through summary statistics alone. The research delivers an integrated, operator-oriented blueprint covering the full decision lifecycle, from technology evaluation and vendor selection through capacity planning and regulatory readiness. Key components include:
- Technology pathway assessment spanning digital micromirror device platforms, laser direct imaging systems, and electron beam lithography architectures, including comparative evaluations of resolution, throughput, uptime economics, software integration complexity, and suitability for specific substrate formats and patterning tolerances.
- Application-driven demand mapping that distinguishes deployment priorities across advanced packaging, printed circuit boards, MEMS and microfluidics, and research and development environments, with explicit guidance on how workflow variations influence machine configuration, consumable strategy, and yield expectations.
- Competitive intensity diagnostics that quantify market concentration, benchmark positioning logic, and identify the strategic levers used by incumbents and emerging entrants to capture share in both high-volume manufacturing-adjacent and low-volume, high-value niches.
- Regulatory and standardization context covering FDA and ISO compliance considerations for microelectronics and medical device applications, as well as the operational implications of laser beam characterization protocols aligned with ISO 11146 for process control and repeatability.
- Technology bottleneck analysis focusing on data-rate management, pixel-count scaling, stitching error mitigation, and computational patterning demands that arise when maskless systems are applied to large-format substrates in AI and HPC packaging scenarios.
- Investment and procurement decision frameworks that connect machine economics to product roadmaps, enabling leaders to assess whether maskless lithography should be positioned as a complementary R&D and rapid-iteration asset or as a strategically embedded production capability for specific portfolio segments.
Each section is structured to support concrete action: supplier evaluation scorecards, technology-fit matrices, adoption timing guidance, and scenario-based considerations that reflect the practical tension between flexibility and throughput in maskless workflows.
Competitive Positioning in a Concentrated yet Differentiated Arena
The maskless lithography landscape is shaped by a balance of established precision-engineering leaders and specialized technology developers, with concentration levels that reward scale, integration depth, and application-specific reliability. The study examines the strategic profiles of leading participants whose product architectures, geographic footprints, and technology roadmaps define the current competitive terrain.
Heidelberg Instruments, headquartered in Heidelberg, Germany, continues to anchor its position as a global leader in high-precision laser lithography systems, maskless aligners, and direct-write platforms serving micro- and nanofabrication across R&D, rapid prototyping, advanced packaging, and production environments. Its recent system enhancements illustrate the broader trend toward performance-dense direct-write architectures that retain maskless flexibility while addressing production-adjacent tolerances.
EV Group, based in St. Florian am Inn, Austria, has reinforced its emphasis on scalable high-throughput digital lithography through maskless exposure platforms built on MLE technology. Its focus on high-volume manufacturing compatibility, advanced packaging, MEMS, and biomedical applications highlights how maskless systems are increasingly positioned to bridge prototyping agility and manufacturing throughput in selective workflow contexts.
Raith GmbH, operating from Dortmund, Germany, provides high-resolution maskless laser beam lithography systems optimized for grayscale and direct-write microfabrication. Its emphasis on ultimate resolution and controlled throughput reflects a segment of the market where pattern fidelity and feature control outweigh raw volume economics.
Kloe, headquartered in Montpellier, France, has expanded its footprint as a manufacturer of direct laser writing equipment and maskless photolithography systems for high-resolution microfabrication, microfluidics, and 3D structures, with deployment spanning more than 45 countries. Its international distribution model demonstrates how specialized maskless tools are becoming embedded across diverse regional innovation ecosystems.
miDALIX, based in Slovenia, offers tabletop maskless lithography systems designed for universal direct-write patterning on micrometer-scale samples using standard photoresists, appealing to research settings and applications requiring precise micropatterning without extensive infrastructure overhead.
JEOL Ltd., headquartered in Tokyo, Japan, complements this landscape with photomask and direct-write lithography equipment, including electron-beam systems that support advanced semiconductor research, nanofabrication, and high-precision mask and reticle writing. Its involvement reflects the enduring role of electron-beam pathways in demanding resolution-critical workflows.
Nanoscribe GmbH, located in Karlsruhe, Germany, addresses maskless high-throughput microfabrication and wafer-scale production in photonics and optics through grayscale lithography systems designed for rapid prototyping and patterning, extending maskless relevance into optical and photonic device development.
Worldwide Maskless Lithography Machine Market
Vistec Electron Beam GmbH, based in Jena, Germany, specializes in electron beam lithography systems for maskless direct-write applications in semiconductor and nanofabrication, reinforcing the segmentation between optical and electron-based maskless modalities.
Durham Magneto Optics, in the United Kingdom, provides compact direct-write optical lithography machines suited to rapid prototyping and small-volume manufacturing in R&D cleanrooms, emphasizing accessibility and footprint efficiency for laboratory-scale operations.
NanoSystem Solutions, Inc., in Japan, delivers maskless lithography tools built around DMD-based immediate exposure onto photoresist with telecentric optics, aligning with workflows that prioritize streamlined patterning integration and reduced mechanical complexity.
Microlight3D, based in France, develops DMD-based maskless lithography systems for direct patterning without physical masks, contributing to a growing ecosystem of digitally controlled exposure architectures that reduce mask supply dependencies and expand design iteration speed.
This competitive landscape is further energized by recent corporate activity that signals where the market is moving in real time. The opening of a co-creation platform equipped with a proprietary Roll-to-Roll maskless lithography system illustrates how flexible electronics commercialization is accelerating demand for new processing modalities. Parallel advances in high-resolution digital micromirror devices with substantially expanded pixel counts are addressing computational and precision bottlenecks in advanced packaging maskless lithography, enabling sub-micron resolution and higher data throughput. In parallel, upgrades to direct-write lithography platforms and the demonstration of high-throughput maskless exposure systems alongside hybrid bonding technologies at major industry events reflect the sector's push toward more production-relevant performance envelopes.
Against this backdrop, market concentration metrics provide essential context for competitive strategy. The study places these concentration levels within a broader analytical frame, showing where scale advantages are likely to compound, where application specialization can shield participants from head-to-head price competition, and where consolidation dynamics may reshape supplier selection over the forecast horizon.
Decision Architecture for 2026 and the Forecast Horizon
For executives evaluating maskless lithography in 2026, the central challenge is not simply whether to adopt the technology, but how to position it relative to existing masked processes, capacity models, and product roadmaps. The research supports this decision architecture through several strategic lenses.
First, maskless lithography is increasingly understood as a complementary capability rather than a wholesale replacement for masked high-volume manufacturing. Its strongest value proposition lies in enabling real-time data transfer and adaptive patterning that overcome reticle size limits and stitching errors on large-format substrates, particularly for AI and HPC packaging, rapid prototyping, and low-volume production runs. Companies that treat maskless systems as strategic flexibility assets—rather than only as cost-reduction tools—tend to capture faster design cycles and more resilient development pipelines.
Second, addressing technology bottlenecks is now inseparable from commercial viability. High data rates and high pixel counts in DMD-based systems, alongside laser beam characterization discipline under relevant ISO standards, directly influence throughput predictability, process consistency, and deployment confidence. The report provides practical evaluation criteria for assessing whether a given system can meet application requirements without imposing excessive computational, integration, or maintenance burdens.
Third, regulatory and quality considerations are increasingly embedded in procurement logic. Maskless lithography systems used in microelectronics and medical devices must align with FDA and ISO guidelines for safety, quality, and environmental impact. These requirements are not peripheral compliance details; they shape vendor selection, validation timelines, and total cost of ownership, especially for organizations operating in regulated or safety-critical application domains.
Fourth, competitive positioning will increasingly depend on the ability to match technology architecture to workflow reality. Throughput-focused platforms, high-resolution direct-write systems, and electron-beam-based maskless solutions each address distinct constraint sets. The study helps leaders separate marketing claims from operational fit by mapping each architecture to use-case economics, integration complexity, and expected performance envelopes in real deployment conditions.
Finally, the forward forecast implies that growth will be sustained by expanding adoption across multiple demand centers rather than by a single dominant application vertical. The strategic implication is clear: organizations that plan for maskless lithography as part of a diversified capability portfolio—spanning advanced packaging, printed circuit boards, MEMS and microfluidics, and R&D prototyping—will be better positioned to absorb demand volatility and capture cross-functional value as the market matures through 2032.
Accessing the Full Intelligence Framework
This article provides a structured preview of the strategic logic underpinning the Worldwide Maskless Lithography Machine Market study. It outlines the market trajectory, the technology and application dimensions that matter most in 2026, and the competitive and regulatory forces shaping procurement and investment decisions. However, the precise segmentation values, regional and application demand distributions, concentration calculations, and vendor-specific strategic scoring are intentionally held within the full report to preserve analytical integrity and support informed decision-making at the operational level.
For teams that require detailed segmentation models, comparative technology assessments, concentration analysis, and scenario-based procurement guidance, the complete study is the intended reference point. The full report enables a more granular reading of where value is being created, how technology pathways are differentiating, and what specific actions will align an organization's maskless lithography strategy with its broader product and capacity roadmap.
In a market where flexibility, precision, and throughput are increasingly interdependent, strategic clarity is not optional. Our research is built to provide that clarity, translating market expansion into actionable intelligence for the decisions that will define competitive positioning throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Maskless Lithography Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


