



PW Consulting: Energy Efficient Sludge Treatment Market to Hit $9,505 Million by 2032

Navigating the Energy Transition: A Strategic Deep Dive into the Global Energy Efficient Sludge Treatment Market (2026–2032)
Introduction: The Imperative for Resource Recovery in a Carbon-Constrained World
As global wastewater infrastructure enters a phase of profound transformation, energy efficiency in sludge treatment has evolved from a technical optimization to a strategic necessity. Municipalities, industrial operators, and technology providers are confronting intersecting pressures: stringent decarbonisation mandates, rising energy costs, and regulatory frameworks that increasingly treat sludge not as waste but as a recoverable resource stream. Against this backdrop, PW Consulting is pleased to introduce our comprehensive Worldwide Energy Efficient Sludge Treatment Market study, a decision-grade intelligence product designed to equip executives, investors, and policy advisors with the structural clarity needed for 2026 planning cycles and beyond.
The market has demonstrated remarkable resilience and directional momentum over the past half-decade. Valued at approximately 3,450.0 million USD in 2020, the sector has expanded through a series of fundamentally driven adoption cycles, reaching an estimated 5,250.0 million USD in 2025. Our baseline projections indicate continued acceleration, with the market advancing toward a 9,505.13 million USD valuation by 2032, underpinned by a compound annual growth rate of 8.85 percent. These figures are not merely retrospective summaries; they represent a structural inflection point where regulatory timelines, capital allocation priorities, and technological maturity are converging. For decision-makers navigating capital-intensive infrastructure investments or technology positioning strategies, understanding the mechanics behind this trajectory is no longer optional—it is a prerequisite for competitive positioning.
This executive preview outlines the analytical architecture of our full report, highlights the strategic dimensions shaping competitive dynamics, and demonstrates how the study translates macroeconomic trends into actionable intelligence. As with all PW Consulting deliverables, the complete segmentation matrices, regional growth drivers, technology adoption curves, and company-level benchmarking data are reserved for subscribers, ensuring that procurement decisions are guided by verified, granular intelligence rather than aggregated industry noise.
Market Architecture and Growth Mechanics: A Structural Overview
The expansion of energy efficient sludge treatment is not a monolithic phenomenon. It is the cumulative result of multiple adoption pathways, each responding to distinct operational constraints and policy signals. Across the 2020–2025 historical window, the market navigated a period of technological consolidation, where early-stage pilot deployments matured into commercially scalable solutions. The 2024–2025 period, in particular, marks a transition from compliance-driven procurement to value-creation-oriented investment, as wastewater operators increasingly pursue energy neutrality, biogas recovery, and phosphorus reclamation as core performance metrics.
Our analysis identifies three interlocking growth vectors that will define the 2026–2032 forecast period. First, regulatory momentum is compressing decision timelines. The revised EU Urban Wastewater Treatment Directive, for instance, mandates energy neutrality for wastewater treatment plants by 2045, creating a hard deadline that accelerates capital planning and technology replacement cycles. In parallel, UK water companies have formalised net-zero commitments targeting 2030, with regulators actively monitoring greenhouse gas reductions across sludge and wastewater operations. These policy anchors are not peripheral; they are reshaping procurement criteria, financing structures, and operational performance benchmarks across mature and emerging markets alike.
Second, the energy footprint of wastewater infrastructure itself is forcing a reevaluation of process design. Aeration systems alone account for 50–60 percent of total plant energy consumption, which means that marginal improvements in sludge handling, dewatering efficiency, and thermal integration produce disproportionate operational savings. Consequently, energy efficient sludge treatment has become a lever for holistic plant optimisation rather than a standalone equipment purchase. Third, the commercialisation of advanced dewatering and thermal hydrolysis technologies is expanding the economic envelope for biogas production and resource recovery, enabling operators to convert sludge streams into district heat, electricity, or recycled byproducts without reliance on external fossil fuels.
The report dissects these dynamics across technology adoption curves, application-specific deployment patterns, and regional infrastructure readiness levels. While high-level market sizing provides directional confidence, the strategic value for 2026 decision-making lies in understanding where capital is flowing, which technological pathways are achieving commercial scale, and how regulatory timelines are reshaping procurement cycles. Subscribers to the full study gain access to the underlying segmentation architecture, including technology-specific revenue trajectories, application-driven demand profiles, and regional deployment intensities—all mapped against historical adoption baselines and forward-looking policy signals.
Technology Pathways and Application Dynamics
Energy efficient sludge treatment encompasses a diverse set of process technologies, each with distinct performance profiles, capital requirements, and integration complexities. Our study recognises four principal technology pathways that are shaping commercial deployment: anaerobic digestion, thermal hydrolysis, solar drying and composting, and advanced dewatering. These are not competing paradigms but complementary layers within an integrated treatment architecture, and their relative commercial weight varies significantly according to feedstock characteristics, regulatory environments, and operator objectives.
Anaerobic digestion remains the foundational pathway for biogas recovery and organic stabilisation, particularly where municipal wastewater treatment facilities seek to offset energy consumption or generate surplus power. Thermal hydrolysis has emerged as a high-impact intensification step, improving biosolids quality, increasing biogas yield, and enhancing downstream resource recovery potential. Solar drying and composting approaches serve niche but strategically important applications where land availability, climate conditions, and regulatory acceptance align. Advanced dewatering solutions, meanwhile, are increasingly positioned as energy-saving infrastructure components that reduce downstream thermal load, lower transportation costs, and improve overall plant efficiency.
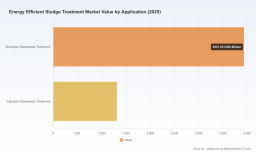
In terms of application segmentation, municipal wastewater treatment represents the dominant deployment environment, reflecting the scale of public infrastructure investment and the pervasive influence of municipal decarbonisation mandates. Industrial wastewater treatment constitutes a distinct but rapidly evolving demand stream, where sludge characteristics, compliance requirements, and energy recovery economics differ materially from municipal profiles. The interplay between these application domains creates both competition for technology suppliers and opportunities for hybrid solution architectures.
A critical structural insight from our analysis is that energy efficiency in sludge treatment is rarely achieved through a single equipment upgrade. Instead, it emerges from system-level integration: combining mechanical dewatering with thermal pre-treatment, recovering heat from filtrate streams, and aligning biogas production with on-site energy demand or district heating networks. The report evaluates these integration patterns across multiple operational contexts, providing decision-makers with a framework for assessing total cost of ownership, payback horizons, and regulatory alignment. Detailed technology adoption matrices, application-specific revenue distributions, and regional deployment intensities are fully elaborated in the complete study, where procurement teams and strategy functions can benchmark their investment assumptions against verified market data.
Competitive Landscape and Strategic Positioning
The competitive environment in energy efficient sludge treatment is characterised by a mix of global engineering conglomerates, specialised technology providers, and integrated environmental services firms. Market concentration metrics indicate a moderately fragmented landscape, with the top three participants collectively representing approximately 28.5 percent of market value and the top five accounting for 39.2 percent. This structure suggests that while scale advantages and integrated service offerings confer meaningful competitive benefits, there remains substantial room for technology differentiation, regional partnerships, and application-specific leadership.
ANDRITZ AG has established a prominent position through its Sludge2Power adiabatic sludge treatment technology and EcoFluid bubbling fluidized bed boiler systems, enabling energy-efficient sewage sludge mono-incineration with self-sustained combustion and phosphorus-rich ash recovery. In September 2025, ANDRITZ was selected to construct a cutting-edge mono-incineration plant at the Böblingen waste incineration site in Germany, a project that underscores the commercial viability of adiabatic treatment at Heating values as low as 3 MJ/kg while producing district heat and electricity without external fossil fuels. This development reflects a broader trend in which thermal treatment pathways are being repositioned as energy recovery assets rather than end-of-pipe disposal solutions.
Alfa Laval AB continues to strengthen its presence through decanter centrifuge platforms such as the ALDEC G3 and ALDEC G3 VecFlow, alongside AS-H belt presses and thermal sludge treatment solutions designed for low energy consumption and high dewatering efficiency. In February 2026, Alfa Laval signed a memorandum of understanding with AquaGreen to combine decanter centrifuge technology with sludge pyrolysis, targeting an end-to-end sustainable treatment solution that produces renewable energy and biochar. This partnership illustrates how technology leaders are expanding beyond core equipment into integrated value chains that align with circular economy objectives.
Veolia Environnement S.A. and SUEZ SA remain central actors in the integrated sludge management space, offering comprehensive handling, dewatering, biosolids processing, and resource recovery capabilities within broader wastewater infrastructure and operations and maintenance services. Veolia’s portfolio spans anaerobic digestion, MemGas technology, thermal processes, and biosolids management, with a clear emphasis on energy autonomy and surplus energy sales. SUEZ’s approach similarly integrates sludge handling and resource recovery into full lifecycle wastewater treatment operations, reinforcing the strategic importance of service continuity and asset performance monitoring.
Wastewater Treatment Reactor Market
Regional and specialised players are also shaping competitive dynamics through targeted innovation. HUBER SE has focused on the Q-PRESS screw press platform, emphasising low electricity costs, wear resistance, and higher-torque gearboxes with reduced energy consumption. In November 2025, HUBER introduced significantly more wear-resistant scraper lips and enhanced gearbox configurations, alongside energy recovery from filtrate water via RoWin heat exchangers. Cambi AS has carved a differentiated position in thermal hydrolysis through CambiTHP, which increases biogas yield, improves biosolids quality, and strengthens the overall energy profile of sludge treatment installations. Flottweg SE and Xylem Inc. contribute complementary capabilities in decanter centrifuge optimisation and broader water technology portfolios, respectively, reinforcing the ecosystem nature of energy efficient sludge treatment solutions.
The full report provides detailed company profiles, competitive positioning assessments, and recent development tracking across the participant landscape. Readers seeking to evaluate supplier capabilities, partnership opportunities, or displacement risks will find the complete study essential for mapping technology roadmaps against commercial execution patterns.
Regulatory Tailwinds and Operational Realities
Regulatory frameworks are acting as both accelerators and boundary conditions for market development. In Europe, the revised Urban Wastewater Treatment Directive is not merely an environmental target; it is a structural redesign mandate that pushes wastewater operators toward energy neutrality by 2045. This timeline has direct implications for asset replacement cycles, technology selection, and capital planning, particularly in markets where legacy infrastructure is approaching the end of its operational life. The directive’s emphasis on decarbonisation also elevates the strategic importance of sludge treatment as a lever for Scope 1 and Scope 2 emissions reduction, rather than a standalone waste management function.
In the United Kingdom, water companies have committed to net-zero emissions by 2030, with regulators actively monitoring progress on greenhouse gas reductions across sludge and wastewater operations. These commitments create a near-term execution window that favours technologies capable of delivering measurable efficiency improvements within compressed deployment horizons. Meanwhile, in the United States, the EPA’s 40 CFR Part 503 framework continues to govern sewage sludge management and land application under the Clean Water Act, supporting biosolids standards and resource recovery practices. While the regulatory emphasis in the U.S. has historically focused on pathogen control and land application compliance, the broader trajectory is shifting toward energy recovery and resource circularity, creating incremental opportunities for advanced treatment technologies.
Worldwide Energy Efficient Sludge Treatment Market
Operational realities further complicate and enrich the market picture. Sludge composition varies widely across municipal and industrial sources, influencing dewaterability, biogas potential, and thermal treatment feasibility. Energy pricing volatility, maintenance logistics, and operator expertise all affect the realised performance of energy efficient treatment systems. Our study incorporates these practical considerations into adoption assessments, helping decision-makers distinguish between laboratory-stage promise and commercially proven reliability. Detailed regional regulatory mappings, compliance-driven demand forecasts, and operational benchmarking data are provided in the complete report to support risk-adjusted investment planning.
Why This Study Matters for 2026 Decision-Making
Market intelligence is most valuable when it converts macro trends into decision-ready structure. The Worldwide Energy Efficient Sludge Treatment Market study is designed to do exactly that for executives navigating 2026 capital allocation, technology selection, partnership strategy, and regional expansion planning. Rather than providing a static snapshot, the report offers a dynamic analytical framework that links historical performance, regulatory timelines, technology maturity, and competitive execution into a single decision architecture.
For technology suppliers, the study clarifies where demand is concentrating, which performance attributes are becoming procurement prerequisites, and how recent partnerships and product updates are reshaping competitive expectations. For wastewater operators and municipal authorities, it provides a structured assessment of technology pathways, integration considerations, and regulatory alignment that supports total cost of ownership evaluations and multi-year infrastructure planning. For investors and financial analysts, the report delivers market sizing, growth trajectories, concentration metrics, and segment-level demand signals that inform valuation assumptions and portfolio strategy.
Importantly, the study is constructed to withstand scrutiny in complex procurement and investment processes. Historical data spans 2020–2025, providing a robust baseline against which forecast assumptions can be tested. The 2026–2032 forecast period is anchored in observable regulatory deadlines, technology deployment patterns, and regional infrastructure pipelines, rather than speculative extrapolation. This discipline is essential in a market where overstated growth projections or undifferentiated segment claims can distort capital decisions and erode trust.
Subscribers to the full report gain access to the complete segmentation framework, including technology-specific and application-specific revenue distributions, regional market intensities, and company-level competitive assessments. These elements are deliberately withheld from the public preview to preserve the analytical integrity of the product and to ensure that detailed intelligence is deployed where it can directly inform commercial and strategic decisions.
Conclusion: Converting Structural Shift into Strategic Advantage
The Worldwide Energy Efficient Sludge Treatment Market is no longer a niche segment of wastewater infrastructure; it is a strategic battleground where regulatory timelines, energy economics, and resource recovery objectives intersect. The market’s trajectory from approximately 3,450.0 million USD in 2020 to a projected 9,505.13 million USD by 2032, at an 8.85 percent CAGR, reflects more than incremental growth. It signals a structural reconfiguration of how sludge is treated, valued, and integrated into broader energy and environmental systems.
For organisations preparing for the 2026 decision cycle, the opportunity lies not in recognising that change is occurring, but in understanding precisely where value is being created, which technologies are crossing commercial thresholds, and how regulatory mandates are compressing procurement and investment timelines. PW Consulting’s full market study provides the depth, structure, and verification required to navigate this environment with confidence. We invite executives, strategy leaders, and investment professionals to access the complete report for the detailed segmentation, regional analysis, technology adoption curves, and competitive benchmarking that will underpin their 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Energy Efficient Sludge Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


