



PW Consulting: Global BWR Market to Hit $4,495.8M by 2032, Driven 4.33% CAGR

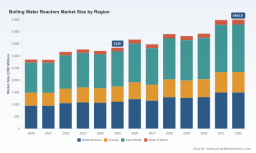
Strategic Imperatives in the Boiling Water Reactor Market: Navigating the 2026-2032 Horizon
The global nuclear energy landscape is undergoing a paradigm shift. As nations seek to balance decarbonization goals with energy security, the Boiling Water Reactor (BWR) segment stands at a critical inflection point. For stakeholders operating within this complex ecosystem, understanding the trajectory of market evolution is not merely an academic exercise—it is a prerequisite for capital allocation, risk mitigation, and long-term competitiveness.
This analysis serves as an introduction to our latest comprehensive market study, Worldwide Boiling Water Reactors Market. Drawing on rigorous quantitative modeling and qualitative industry assessment, this research provides a detailed roadmap of the sector from the base year 2025 through the forecast period ending in 2032. The following insights highlight the strategic value embedded within this intelligence, offering a preview of the operational and financial dynamics that will define the next decade.
Market Trajectory and Financial Outlook
The economic narrative of the BWR market is one of resilience tempered by volatility. Analysis of historical data from 2020 to 2025 reveals a sector that has maintained substantial valuation despite global disruptions. In 2020, the market established a baseline revenue scale in the billions of USD, navigating through the initial shocks of the pandemic era. By 2025, the market size has stabilized and grown, reflecting renewed interest in nuclear capacity as a baseload power solution.
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate (CAGR) of 4.33%. This growth trajectory suggests a steady expansion rather than a speculative bubble, driven by lifecycle extensions of existing fleets and the commissioning of new advanced units. The revenue projections indicate that by the end of the forecast window, the market will have surpassed its 2025 valuation significantly, underscoring the compounding value of sustained nuclear infrastructure investment.
However, growth is not linear. The data highlights variability in annual market size, reflecting the lumpy nature of nuclear project cycles, regulatory approvals, and construction milestones. For enterprise leaders, this underscores the importance of timing and liquidity management. The study provides the granularity needed to anticipate these fluctuations, allowing organizations to align their resource planning with the broader market rhythm.
Worldwide Boiling Water Reactors Market
Segmentation Dynamics: Technology, Service, and Application
A superficial view of the market reveals aggregate numbers, but strategic advantage lies in understanding the underlying segmentation. The BWR market is not monolithic; it is divided by reactor generation, service type, and end-user applications, each carrying distinct risk and return profiles.
From a technological standpoint, the market comprises established Generation II BWR units, Advanced Boiling Water Reactors (ABWR), and the emerging Small Modular BWR category. The coexistence of these generations creates a complex value chain. Legacy units demand different support structures compared to next-generation designs. The report dissects the revenue contribution and strategic weight of each generation, offering clarity on where capital is flowing and which technologies are gaining traction among operators.
Service segmentation further refines this picture. The market is driven by equipment and components procurement, maintenance and outage services, and nuclear fuel management. Each of these service lines responds to different operational triggers. For instance, maintenance services are tied to the operational hours and regulatory inspection schedules of active plants, while equipment procurement is linked to new build projects and major upgrades. Understanding the proportional significance of these segments allows vendors to tailor their go-to-market strategies and helps operators optimize their outsourcing decisions.
Furthermore, the geographic distribution of market activity presents distinct operational environments. Regional dynamics are influenced by local energy policies, regulatory frameworks, and existing infrastructure maturity. The study maps these regional variances without oversimplifying them, providing a nuanced view of where demand is concentrated and where potential barriers to entry exist. This regional intelligence is critical for multinational corporations seeking to optimize their supply chain logistics or for local players assessing competitive threats from abroad.
Nuclear Moisture Separator Reheaters Market
Competitive Landscape and Key Player Strategies
The BWR market is characterized by a high degree of concentration, with a few dominant entities shaping the technological and commercial standards. The industry context reveals a playing field where expertise, regulatory certification, and long-term service capabilities are significant moats.
Central to this landscape are key industry leaders such as GE Hitachi Nuclear Energy, Hitachi-GE Nuclear Energy, Ltd., and Toshiba Energy Systems & Solutions Corporation. These organizations are not merely manufacturers; they are partners in the lifecycle management of nuclear assets. GE Hitachi Nuclear Energy, based in Wilmington, North Carolina, remains a primary global supplier of BWR technology. Their portfolio includes the certified BWRX-300 small modular reactor and economic simplified BWR designs, positioning them at the forefront of both traditional and innovative deployments.
In Japan, the joint venture Hitachi-GE Nuclear Energy, Ltd., headquartered in Tokyo, plays a pivotal role in delivering ABWR technology and providing engineering, procurement, and maintenance services for BWR fleets. Their presence underscores the importance of international collaboration and localized expertise in sustaining nuclear operations. Similarly, Toshiba Energy Systems & Solutions Corporation continues to develop ABWR technology and support BWR operations, fuel, and modernization projects worldwide. The interplay between these entities drives innovation and sets benchmarks for safety and efficiency.
Recent developments highlight the agility of these key players. For example, GE Hitachi Nuclear Energy achieved a significant construction milestone in November 2024 by pouring first concrete for BWRX-300 Unit 1 at the Darlington New Nuclear Project site, as announced by Ontario Power Generation. Earlier in May 2024, they were selected by the Tennessee Valley Authority for potential deployment of multiple BWRX-300 units at the Clinch River Early Site Permit area. Furthermore, in March 2024, they received final safety design approval from the Canadian Nuclear Safety Commission for the BWRX-300 reactor. These events signal a transition from conceptual planning to tangible execution, reinforcing confidence in the technological readiness of advanced BWR solutions.
Market concentration metrics indicate that the top players hold a substantial share of the market revenue, creating an environment where strategic partnerships and supply chain resilience are paramount. The report analyzes these dynamics in depth, exploring how oligopolistic structures influence pricing power, innovation cycles, and barriers to entry for new entrants.
Industry Dynamics and External Catalysts
The BWR market does not operate in a vacuum. It is sensitive to a wide array of external factors ranging from raw material costs to geopolitical regulations. A comprehensive market study must account for these variables, as they can materially impact project economics and operational continuity.
Raw material availability remains a critical concern. For instance, the U3O8 spot price exceeded $100 per pound in Q1 2024 due to supply tightness, according to the TradeTech Uranium Price Indicator. Such fluctuations in fuel costs can alter the levelized cost of energy for nuclear operators and influence long-term contracting strategies. The study evaluates how these input cost trends ripple through the service and equipment segments.
Regulatory frameworks are equally influential. In the United States, legislation prohibiting Russian uranium imports and establishing a domestic supply chain was signed into law in May 2024, effective August 2024. This shift aims to reduce dependency on foreign sources but also introduces complexities in supply chain reconfiguration. Simultaneously, the International Atomic Energy Agency released a revision to Specific Safety Guide SSG-35 on seismic design for light water reactors including BWRs in September 2023. Compliance with evolving safety standards requires capital investment and technical adaptation, factors that are meticulously modeled in our forecast.
Policy incentives also play a transformative role. The UK's Great British Nuclear initiative shortlisted the BWRX-300 among small modular reactor designs for nationwide rollout in July 2023, signaling governmental support for specific technologies. In the United States, the Inflation Reduction Act provides up to 30% investment tax credit for new nuclear capacity including BWR deployments, as noted by the US Department of Energy in August 2022. These financial mechanisms can significantly improve project viability and attract private investment. The report integrates these policy drivers to assess their net impact on market growth and regional attractiveness.
Strategic Applications for Enterprise Decision-Making
Access to high-quality market intelligence enables organizations to move from reactive positioning to proactive strategy formulation. This Worldwide Boiling Water Reactors Market study is designed to support decision-making across multiple functional areas.
For investment analysts and financial planners, the detailed revenue forecasts and CAGR projections provide the foundation for valuation models and risk assessments. Understanding the historical volatility and future growth curves allows for more accurate cash flow modeling and scenario planning. The segmentation data further enables the isolation of specific growth drivers, helping investors identify which sub-sectors offer the most attractive risk-adjusted returns.
For corporate strategists and business development teams, the competitive landscape analysis offers insights into potential partnership opportunities and market gaps. By understanding the strengths and recent activities of key players like GE Hitachi and Toshiba, organizations can identify areas where they can differentiate their offerings or where collaboration might be mutually beneficial. The report also highlights the shifting focus towards small modular reactors and advanced designs, suggesting where innovation efforts should be concentrated.
For operations and supply chain managers, the insights into service types and regional dynamics are invaluable. Knowing the demand patterns for maintenance services versus equipment procurement helps in capacity planning and inventory management. Regional analysis aids in determining where to locate assets or how to navigate local regulatory requirements. Furthermore, awareness of external catalysts such as uranium price trends and regulatory changes allows for better hedging strategies and compliance planning.
Ultimately, this research empowers stakeholders to navigate uncertainty with greater confidence. In an industry where project timelines span decades and capital intensity is high, informed decision-making is the primary defense against risk. The study does not merely report on the past; it constructs a credible view of the future, grounded in data and industry expertise.
Conclusion
The Boiling Water Reactor market represents a critical component of the global transition to sustainable energy. As we move through the forecast period of 2026 to 2032, the interplay of technological advancement, regulatory evolution, and market concentration will define the opportunities available to industry participants. The data suggests a market on a path of steady growth, supported by both the extension of existing assets and the emergence of advanced reactor designs.
This teaser provides a glimpse into the depth of analysis available in our full report. However, the complete strategic picture requires a deeper dive into the specific segment dynamics, regional breakdowns, and proprietary forecasts that cannot be fully elaborated here. For organizations committed to making informed decisions in this high-stakes environment, access to the comprehensive Worldwide Boiling Water Reactors Market study is an essential investment. We invite you to explore the full report to unlock the detailed intelligence necessary to navigate the future of nuclear energy with precision and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Boiling Water Reactors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


