



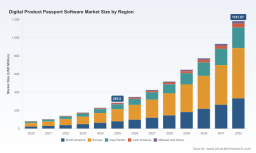
PW Consulting: Digital Product Passport Software Market Surges to $285.5M in 2025, 22.5% CAGR to $1.18B by 2032

The Digital Product Passport Software Market: A Strategic Imperative for 2026 and Beyond
As global regulatory frameworks shift toward unprecedented transparency, the Digital Product Passport Software Market has emerged from a niche sustainability initiative into a core infrastructure requirement for modern enterprises. Based on our latest comprehensive analysis, this sector is not merely growing—it is accelerating at a pace that demands immediate strategic attention from C-suite executives, supply chain leaders, and compliance officers. The transition from voluntary sustainability reporting to mandatory digital traceability represents a fundamental restructuring of how products are manufactured, tracked, and consumed.
Our research indicates that the market revenue, measured in USD Million, has exhibited a compound annual growth rate (CAGR) of 22.5% throughout the forecast period extending from 2026 to 2032. This trajectory underscores a critical reality: Digital Product Passport (DPP) software is no longer a future consideration but a present-day operational necessity. With the overall market size projected to expand significantly from its base year levels in 2025, organizations that delay adoption risk not only regulatory penalties but also competitive obsolescence in increasingly transparent supply chains.
This article serves as a strategic overview of the market dynamics, competitive landscape, and operational considerations detailed in our full report. While we outline the macro-level forces shaping the industry, the specific segmentation data, regional revenue splits, and granular adoption rates are reserved for our licensed intelligence portal. Understanding the breadth of this opportunity requires looking beyond the headline numbers to the structural shifts driving demand.
Regulatory Catalysts and Market Dynamics
The primary engine propelling this market expansion is the tightening regulatory environment, particularly within the European Union. The Ecodesign for Sustainable Products Regulation (ESPR) has established a phased implementation roadmap for Digital Product Passports across priority sectors. Our analysis highlights that batteries are set to become the first mandatory category from 2027, followed by textiles, iron and steel, and other key industries. This regulatory cascade creates a domino effect across global supply chains, compelling manufacturers outside the EU to adopt compliant systems if they wish to maintain access to the European market.
A critical milestone in this regulatory timeline is the operational launch of the central EU DPP Registry. Scheduled to become functional in July 2026, this registry will serve as the central node for market access verification. Organizations must ensure their software infrastructure is interoperable with this registry well before the deadline. The implication for enterprise strategy is clear: compliance is not a checkbox exercise but a data integration challenge that requires robust software architecture capable of communicating with centralized government databases.
However, regulatory pressure is only one side of the coin. The market dynamics are equally influenced by the need for supply chain visibility and consumer engagement. Modern consumers increasingly demand verifiable proof of sustainability claims, driving brands to adopt DPP solutions that offer end-to-end traceability. This dual pressure—regulatory compliance on one end and consumer trust on the other—creates a resilient demand curve that is less susceptible to economic downturns than typical software markets.
Key Industry Developments and Strategic Partnerships
The landscape is evolving rapidly through strategic collaborations and pilot projects that signal the transition from concept to scalable execution. In early 2026, significant moves were observed among key players. For instance, a notable Memorandum of Understanding was signed between DigiProd Pass and Fashion Power Group for a Digital Product Passport pilot project in apparel manufacturing. Such initiatives demonstrate the industry's focus on practical application within the textile sector, which remains a high-priority area for regulation.
Simultaneously, technology giants are entering the fray to provide the infrastructure necessary for scale. A collaboration between Siemens and Accenture has been advancing Digital Product Passports from concept to scalable execution, with a specific focus on data integration. This involvement of major industrial technology firms validates the market's maturity and suggests that DPP software will increasingly become embedded within broader Manufacturing Execution Systems (MES) and Enterprise Resource Planning (ERP) platforms.
Furthermore, sector-specific preparations are underway. Leaders in the textile space have highlighted ongoing DPP pilots and groundwork for production systems ahead of the 2026 registry launch. These updates indicate that early movers are already stress-testing their data pipelines to ensure they can handle the volume and veracity requirements of a fully operational registry. The convergence of regulatory deadlines and technological readiness creates a narrow window for organizations to finalize their vendor selection and implementation strategies.
Market Segmentation and Deployment Preferences
Our report dives deep into how organizations are choosing to deploy DPP solutions. While specific revenue splits are detailed in the full intelligence subscription, the broader trends indicate a strong preference for certain deployment models based on organizational size and complexity. Cloud-based DPP software deployments are becoming the default choice for many entities, particularly Small and Medium-sized Enterprises (SMEs). This preference is driven by lower upfront infrastructure costs and the flexibility of subscription models compared to traditional on-premises solutions.
Digital Product Passport Software Market
The shift toward cloud-based architectures also addresses the scalability challenges inherent in managing vast amounts of product data. However, this introduces new operational considerations. Organizations must remain vigilant about cloud spending efficiency, as reports suggest that unused resources can lead to significant waste in cloud hosting budgets. For scalable DPP platforms reliant on cloud hosting for data management, optimizing these costs is a key operational factor that our research examines in detail.
Industry vertical adoption also varies significantly based on regulatory exposure and supply chain complexity. Sectors such as textiles and apparel, electronics, and automotive batteries are leading the charge. Each sector presents unique challenges regarding data standardization and lifecycle management. For example, the electronics sector must navigate complex chemical compliance data, while the fashion industry focuses heavily on material provenance and labor standards. Our full report provides a comparative analysis of these vertical-specific requirements, helping stakeholders understand which solutions are best tailored to their specific operational context.
Competitive Landscape and Vendor Ecosystem
The market is characterized by a mix of specialized startups, established compliance software providers, and large conglomerates entering the space. Our analysis identifies a fragmented but consolidating landscape, with a handful of key players capturing significant attention. The competitive intensity is high, driven by the race to establish standard-setting positions before the registries go live.
Among the notable entities shaping the market is Spherity, based in Cologne, Germany. Their VERA Digital Product Passport solution is heavily focused on battery passports and compliance with ESPR and REACH regulations. They enable lifecycle management and integrate recycling and resale marketplace functionalities, making them particularly relevant for the battery sector where mandatory compliance begins earliest.
In the textiles and fashion domain, TrusTrace, headquartered in Stockholm, Sweden, delivers an end-to-end DPP compliance solution. Their offering includes supplier traceability, unique IDs, and QR codes designed for standardized consumer interfaces. This focus on verified supply chain data aligns closely with the needs of fashion brands facing intense scrutiny over sustainability claims. Similarly, Arianee, located in Paris, France, offers a blockchain-powered DPP platform specialized in product lifecycle, ownership tracking, and consumer engagement, with a strong foothold in luxury goods and fashion.
Kezzler, from Oslo, Norway, provides a Connected Products Platform (CPP) for digital IDs and DPP across industries including textiles and footwear. Their support for GS1 Digital Link and partnerships for supply chain visibility positions them as a infrastructure-play vendor. On the compliance and chemical safety side, 3E Exchange, based in Carlsbad, California, provides Digital Product Passports integrated with safety, chemical, and regulatory compliance data such as PFAS and RoHS, catering to supply chain visibility and sustainability requirements.
Renoon, operating out of the Netherlands, functions as a DPP infrastructure platform connecting data, compliance, and customer value for fashion and textile brands, with a strong emphasis on operational system integration. iPoint-systems, based in Reutlingen, Germany, offers software solutions for product compliance and sustainability data management supporting DPP requirements, leveraging their long history in compliance software.
Blockchain technology remains a core component for several players. Circularise, also based in the Netherlands, provides blockchain-based Digital Product Passports for material traceability, transparency, and circular economy applications. In the realm of retail and labeling, Avery Dennison, headquartered in Mentor, Ohio, delivers DPP as a Service (DPPaaS) via their atma.io platform for end-to-end product traceability and EU compliance in fashion and retail. Finally, Carbonfact, with a presence in France and the USA, offers an AI-powered platform for LCA-based Digital Product Passports in apparel and footwear, automating environmental data and publishing compliant DPPs.
Market concentration metrics suggest that while no single vendor dominates the entire landscape, there is a moderate level of consolidation among the top players. This fragmentation offers buyers choice but also creates complexity in selecting the right partner. Our full report includes a detailed vendor benchmarking matrix that evaluates these companies based on technology stack, compliance coverage, and scalability.
Strategic Considerations for 2026 Decision Makers
For enterprise leaders planning their 2026 strategies, several critical factors emerge from our analysis. First, the timeline for compliance is non-negotiable. With the EU DPP Registry becoming operational in July 2026, the window for system integration and testing is narrowing. Organizations must prioritize data readiness, ensuring that product information is structured, verifiable, and accessible via API.
Second, data privacy cannot be an afterthought. DPP systems handling personal data must comply with GDPR requirements, including data minimisation, explicit consent, and breach notification within 72 hours. Potential fines can reach up to 4% of global turnover, representing a significant financial risk. Our research outlines the specific data governance frameworks required to mitigate this risk while maintaining the transparency needed for compliance.
Third, the cost of non-compliance is severe. Under ESPR regulations, non-compliance prohibits the market placement of affected products in the EU. Member states are empowered to enforce fines and potential public procurement exclusions. This creates a clear line of sight between DPP software investment and revenue protection. The software is not an IT expense but a license to operate in key markets.
Finally, organizations must consider the long-term scalability of their chosen solution. As the registry expands to include more product categories beyond batteries and textiles, the software must be flexible enough to accommodate new data fields and reporting standards. Vendors that offer modular architectures and strong integration capabilities with existing ERP and PLM systems will likely provide more value over the forecast period.
Conclusion and Access to Full Intelligence
The Digital Product Passport Software Market represents one of the most significant shifts in industrial data management in recent decades. The convergence of regulatory mandates, consumer demand, and technological maturity creates a compelling case for immediate action. With a projected CAGR of 22.5% and a market size expanding into the billions by the end of the decade, the stakes for strategic positioning are high.
However, navigating this landscape requires more than general awareness. Success depends on granular insights into regional adoption rates, specific vendor capabilities, and detailed cost-benefit analyses of deployment models. Our full market research report provides the depth required to make informed investment decisions, including proprietary data on segmentation splits, competitive positioning, and risk assessments that are not available in public summaries.
To access the complete dataset, including detailed regional revenue projections, specific vendor benchmarking scores, and comprehensive regulatory impact analyses, we invite you to explore our dedicated research portal. The intelligence contained within is designed to equip your organization with the precision needed to lead in the era of digital transparency.
Shipping Software Market
For detailed analysis of this topic, please visit the official page: Digital Product Passport Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


