



PW Consulting: Global Utility String Inverter Market Hits $7,505M in 2025, Projected 8.74% CAGR to 2032

Navigating the 2026 Landscape: Strategic Insights from the Worldwide Utility Scale String Inverter Market
The global energy transition is entering a phase of structural maturation, where the performance, scalability, and regulatory alignment of utility-scale string inverters have become decisive factors in project economics and grid resilience. As solar deployments shift from policy-driven experimentation to commercially optimized infrastructure, procurement teams, technology strategists, and market planners require intelligence that cuts through fragmented signal and isolates actionable trajectory. The latest Worldwide Utility Scale String Inverter Market research report delivers precisely this framework: a rigorously modeled, multi-dimensional analysis designed to anchor 2026 corporate decision-making in verifiable market mechanics rather than speculative narratives.
This executive briefing outlines the core analytical architecture of the study, demonstrates its direct application to 2026 strategic planning, and illustrates how procurement roadmaps, capacity allocation, and competitive positioning can be refined using the report’s proprietary segmentation and scenario modeling. Readers seeking granular regional breakdowns, power-rating revenue distributions, and component-level valuation matrices will find those datasets systematically mapped within the full publication, where they are structured for immediate integration into investment committees, supply chain forecasts, and technology adoption timelines.
The 2026 Inflection Point: Why Utility-Scale String Inverters Demand Refined Strategic Intelligence
The utility-scale inverter segment has evolved from a commoditized balance-of-system component into a highly engineered nexus of grid-forming capability, modular scalability, and software-integrated asset management. Recent industry assessments confirm that string inverter architectures now command a majority share of the utility-scale on-grid inverter market, driven by their inherent flexibility in phased deployments, simplified maintenance logistics, and favorable levelized cost of energy profiles. This structural shift compels stakeholders to reassess procurement criteria, vendor qualification metrics, and long-term service agreements with greater precision than historical centralized-inverter paradigms required.
The research report captures this transition by establishing a continuous historical baseline spanning 2020 through 2025, then projecting forward across a six-year forecast window through 2032. Total market revenue, measured in USD millions, has been reconstructed using shipment-weighted valuation, regional deployment pacing, and component-mix evolution. The trajectory from the early 2020 baseline to the mid-2020s reflects accelerated project pipelines, improved inverter power density, and the compounding effect of utility-scale tender activity across multiple geographies. Forecasts extend this momentum through 2032, with the compound annual growth rate anchoring at 8.74 percent. This growth rate is not presented as a static assumption but as a dynamically stress-tested output that incorporates capacity expansion cycles, module-to-inverter power matching trends, and evolving interconnection standards.
For 2026 decision-makers, this methodology translates into three immediate strategic advantages. First, it isolates the inflection between historical shipment execution and forward-looking capacity commitments, enabling capital planners to distinguish between temporary supply tightness and structural demand expansion. Second, it maps the interaction between hardware deployment and software/service attachment rates, revealing how recurring revenue streams and performance guarantees are reshaping vendor selection criteria. Third, it provides a disciplined baseline against which internal procurement forecasts, regional pipeline assumptions, and technology roadmap milestones can be calibrated, reducing the risk of overcommitting to inventory or underpreparing for specification upgrades.
Research Architecture: How the Report Converts Complexity into Executable Intelligence
The study is engineered to serve cross-functional teams rather than a single procurement silo. Its analytical framework is organized around multiple interdependent dimensions that mirror how enterprise stakeholders actually evaluate utility-scale inverter decisions. Each dimension is built with transparent modeling assumptions, cross-validated against shipment records, tender documentation, and manufacturer capacity disclosures, then stress-tested across macroeconomic and regulatory scenarios.
Segmentation Framework and Analytical Depth
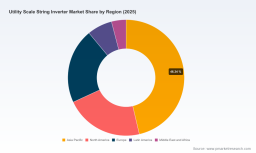
The report dissects the market through three core segmentation axes, each designed to reveal distinct commercial implications. Regional analysis maps deployment concentration, policy-driven pipeline velocity, and supply chain localization trends without reducing complex geographies to simplistic growth rankings. Power-rating segmentation captures the ongoing shift toward higher-current architectures and modular block configurations that align with next-generation photovoltaic module formats and phased plant commissioning strategies. Component-level analysis separates hardware revenue from software and services, illuminating how remote monitoring, predictive maintenance, grid-support firmware, and performance optimization layers are becoming inseparable from the core inverter value proposition.
A dedicated competitive concentration module quantifies market consolidation dynamics, tracking how leading manufacturers balance scale, technological differentiation, and regional service footprints. The analysis contextualizes concentration metrics against recent production expansions, product architecture launches, and grid-forming capability introductions, allowing readers to assess whether market share shifts reflect temporary pricing advantages or durable structural moats.
Operational Content for 2026 Planning Cycles
Beyond high-level sizing, the publication delivers practical instruments that can be embedded directly into internal workflows. These include:
- Pipeline-to-capacity alignment matrices that help procurement and engineering teams match inverter specifications with anticipated module upgrades and site layout changes.
- Vendor capability benchmarking across grid support features, thermal performance thresholds, and modular scalability, enabling systematic shortlisting rather than anecdotal comparison.
- Regulatory exposure mapping that ties incentive phase-out timing, market-based pricing transitions, and interconnection rule updates to deployment windows and margin sensitivity.
- Supply chain cost-pressure indicators that connect raw material pricing movements, labor cost escalation, and manufacturing expansion timelines to component valuation and total installed cost forecasts.
This structuring ensures that the report functions not merely as a market snapshot but as a decision-support system for 2026 budgeting, vendor negotiations, and technology roadmapping. The full report preserves detailed data tables, scenario overlays, and regional granularity so that analysts can extract precisely the slice required for their internal models without reconstructing the underlying methodology from scratch.
Worldwide Utility Scale String Inverter Market
Competitive Positioning and the 2026 Vendor Landscape
The utility-scale string inverter market is contested by a diverse set of manufacturers whose strategies diverge along technology integration, regional service strength, production scalability, and software differentiation. Competitive analysis in the report evaluates these players through a multi-layered lens: shipment momentum, architecture innovation, grid-forming and high-current readiness, service network density, and exposure to regional policy shifts. Rather than presenting a static leaderboard, the research maps how each company’s recent moves position it for specific deployment profiles and procurement priorities in 2026 and beyond.
Major Chinese manufacturers continue to emphasize modular architectures, high power density, and AI-assisted fault detection. Recent product introductions highlight scalable block configurations, enhanced current support for high-power modules, and intelligent arc-fault and grid-forming capabilities designed for large PV plants and elevated ambient operating conditions. These developments signal a clear intent to align inverter design with the next wave of utility-scale projects that prioritize phased construction, higher module currents, and reduced derating risk under temperature stress.
European and other established technology providers are responding with heightened focus on industrial-grade reliability, modular system design, and grid integration solutions that address stringent interconnection requirements and long-term performance guarantees. Recent production expansions and high-capacity inverter line adjustments illustrate how incumbents are scaling to meet global demand while reinforcing perceptions of engineering robustness and service continuity.
Simultaneously, companies with strong regional footholds are leveraging localized supply, specialized high-voltage string platforms, and utility-scale ground-mount expertise to defend or expand share in specific markets. Others are extending their footprint from distributed or commercial segments into larger utility configurations, while integrated industrial and electrification players continue to position inverters within broader energy management and power conversion portfolios.
The report synthesizes these dynamics into a structured competitive matrix that helps buyers evaluate trade-offs among price, technological readiness, service responsiveness, and supply continuity. It also tracks how recent product launches and production expansions alter short-term availability expectations, which is critical for 2026 project timelines where specification changes late in the design cycle can cascade into delivery delays or renegotiation risk.
Regulatory, Cost, and Market Structure Dynamics Shaping 2026 Decisions
No utility-scale procurement strategy in 2026 can ignore the regulatory and cost environment. The research embeds these forces directly into its scenario analysis rather than treating them as peripheral commentary. In the United States, legislative changes affecting clean electricity production and investment tax credits introduce timing sensitivity for facilities with construction commencement and in-service dates beyond specific thresholds. The report translates these policy milestones into deployment pacing implications, helping planners sequence projects to align incentive eligibility with inverter procurement, manufacturing lead times, and interconnection queue realities.
PV Inverters Market
On the cost side, recent movements in global polysilicon pricing and labor cost escalation in North American utility-scale installations feed directly into total system cost modeling. Even when inverter hardware constitutes a defined share of balance-of-system expenditure, upstream material pricing and installation labor dynamics influence bidding environments, margin structures, and the relative attractiveness of higher-efficiency or higher-reliability inverter options. The research incorporates these cost-pressure indicators to illustrate where inverter specification choices can partially offset broader system cost inflation through improved performance, reduced downtime, or simplified commissioning.
Regulatory shifts in other regions similarly reshape project economics and inverter selection logic. Market-based pricing reforms for new wind and solar capacity, restrictions on full-export configurations above certain capacity thresholds, and evolving compensation structures alter how developers value export flexibility, curtailment resilience, and grid-support features. The report analyzes how these policy transitions influence the relative priority of modular designs, software-driven optimization, and inverters capable of operating efficiently under variable compensation and export constraints.
Taken together, these dynamics underscore why deterministic forecasting is insufficient in 2026. The report’s value lies in its ability to connect policy timeline shocks, input-cost volatility, and technology differentiation into a single evaluative framework, enabling stakeholders to test deployment timing, specification selection, and vendor commitments against multiple plausible futures.
From Intelligence to Execution: Translating Findings into 2026 Corporate Strategy
The strategic utility of this research is maximized when organizations move from observation to integration. For procurement and supply chain leaders, the report supports more disciplined vendor shortlisting, contract structuring, and inventory positioning by clarifying where modular scalability, current-class upgrades, and software attachment rates are becoming decisive purchasing criteria. For technology and engineering teams, it offers a structured basis for evaluating grid-forming readiness, thermal performance margins, and compatibility with next-generation module formats. For executives and market planners, the modeled growth trajectory and concentration analysis inform capacity planning, partnership evaluation, and regional prioritization with reduced reliance on fragmented public data.
Because the full dataset preserves detailed regional valuation, power-rating revenue distribution, component-level breakdowns, and competitive event timelines, teams can extract the exact parameters needed for internal financial models, bid strategy documents, and technology roadmaps without reconstructing the underlying market logic. The publication is deliberately organized so that high-level narrative supports strategic alignment while granular tables and scenario overlays enable precise operational use.
Accessing the Full Market Intelligence
The Worldwide Utility Scale String Inverter Market research report is structured as a working intelligence asset for organizations that must make capital, procurement, and technology decisions in a fast-shifting environment. Its combination of historical reconstruction, forward-looking growth modeling, segmentation depth, and competitive event tracking provides a comprehensive foundation for 2026 planning cycles. Stakeholders seeking complete regional data splits, power-rating and component revenue distributions, vendor benchmarking details, and scenario-based projections are encouraged to access the full report through the source page, where the complete intelligence set is available for immediate integration into strategic workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Utility Scale String Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


