



Worldwide Coffee Concentrate Juice Market: Why 6.12% CAGR Changes Everything

Strategic Trends and Commercial Opportunities in the Global Coffee Concentrate Market
Market Landscape and Core Challenges
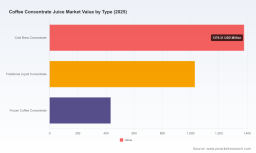
The global coffee concentrate market has demonstrated consistent expansion, with revenue climbing from approximately USD 2,120.45 million in 2020 to an estimated USD 2,842.50 million in 2025. Projections indicate a compound annual growth rate of 6.12 percent through 2032, positioning the sector to reach roughly USD 4,303.18 million by the end of the forecast window. This trajectory reflects a broader reallocation of value within the beverage industry, where convenience, consistency, and scalability are increasingly dictating procurement decisions across both commercial and retail channels. The market's steady expansion suggests that concentrate formats are no longer functioning as a niche input but are becoming a structural component of modern beverage architecture.
Despite the favorable growth backdrop, the industry is navigating several structural friction points that will determine which participants capture disproportionate value in the coming years. First, raw material volatility continues to inject uncertainty into cost planning and margin management. The International Coffee Organization's Composite Indicator Price averaged 296.89 US cents per pound in January 2026, followed by a downward drift toward lows near 262 US cents per pound in February before partial stabilization in the 273–290 US cents per pound range during the spring months. This pattern underscores the sensitivity of concentrate economics to crop cycles, weather outcomes, and supply expectations. When input costs shift rapidly, manufacturers with limited hedging discipline or inflexible procurement structures face compressed profitability, while more adaptive firms can protect margins and even gain share during periods of price dislocation.
Second, regulatory architecture remains uneven and poorly synchronized across markets, creating compliance friction for global operators. Coffee and tea infusions derived from dried ingredients fall outside the scope of FDA Juice HACCP regulation, a distinction that differentiates coffee concentrates from fruit or vegetable juice concentrates intended for beverage use. At the same time, labeling rules for products purporting to contain juice require explicit juice content declarations and mandate that beverages made from concentrate include terms such as "from concentrate" or "reconstituted" where the product name appears. For coffee concentrate manufacturers operating in adjacent or hybrid categories, these overlapping and sometimes contradictory requirements increase formulation complexity, labeling costs, and the risk of misclassification. Firms that invest early in regulatory mapping and documentation discipline will face fewer costly disruptions as product portfolios expand across categories and geographies.
Third, the combination of market concentration and ongoing process innovation is raising the competitive bar. With the top three participants accounting for roughly 38.45 percent of revenue and the top five reaching approximately 52.3 percent, scale, brand equity, and distribution reach continue to confer meaningful advantages. Yet concentration also signals an opportunity for targeted differentiation. As major operators push proprietary processing technologies and customized concentrate variants, smaller or regionally focused players must avoid competing on commodity-like volumes alone. The market is bifurcating: scale players are leveraging volume and branding, while agile suppliers are carving positions through specialty origins, performance-focused processing, and tailored foodservice formats. Recognizing this divergence is essential for any operator planning capacity, partnership, or entry decisions.
Coffee Concentrates Market
Key Growth Drivers
Several interconnected forces are shaping the direction of the coffee concentrate market and creating differentiated opportunities for participants that align their capabilities with structural demand shifts.
Technological Innovation and Processing Differentiation
Process innovation remains one of the most consequential drivers of competitive advantage. Advances in cold-brew extraction, high-Brix concentration, and shelf-stable liquid formulation are enabling manufacturers to deliver concentrates with improved flavor consistency, reduced preparation complexity, and broader application compatibility. Recent product activity illustrates this trajectory clearly. In July 2025, Red Diamond Coffee & Tea introduced the Fitz Cold Brew Coffee Concentrate for foodservice operators, designed to simplify cold brew preparation by providing a ready-to-dilute format that reduces labor, variability, and equipment demands. A few months later, in April 2026, Nestlé and Starbucks unveiled the Starbucks Coffee Craft concentrate, expanding cold coffee availability through a concentrate format engineered for consistent taste and efficient deployment across foodservice and beverage manufacturing applications.
These launches are not isolated product additions; they reflect a broader shift toward concentrates that serve as operational tools rather than raw inputs. For beverage manufacturers and foodservice operators, the commercial appeal of concentrates increasingly rests on repeatability, speed of preparation, and compatibility with existing dispensing or blending infrastructure. Suppliers that can pair flavor integrity with formulation flexibility, such as customized Brix levels or origin-specific profiles, are well positioned to deepen customer relationships and move beyond transactional supply arrangements. The strategic implication is that processing capability is becoming a core differentiator, and investment in extraction, stabilization, and customization technologies is likely to separate market leaders from follow-on competitors.
Demand-Side Transformation and Channel Evolution
Consumer and enterprise behavior is reshaping where and how coffee concentrate is consumed. Cold coffee formats have moved from a seasonal novelty to a sustained category with year-round demand, and the concentrate segment is benefiting directly from this normalization. Foodservice operators are drawn to concentrate formats that reduce preparation variability and labor intensity, particularly in high-turnover environments where consistency and speed are essential. At the same time, retail and household channels are absorbing concentrates as consumers seek convenient, customizable home beverage experiences without the operational burden of brewing from scratch.
This channel divergence is producing distinct demand profiles. Foodservice demand tends to prioritize operational efficiency, portion control, and compatibility with existing equipment. Retail and household demand places greater weight on shelf stability, ease of use, and perceived premium quality. Manufacturers that design concentrate portfolios with these channel-specific requirements in mind can capture value across multiple touchpoints without forcing a single format to carry all use cases. The broader insight is that demand growth is being supported not only by total volume expansion but also by the migration of coffee consumption into formats that are inherently more concentrate-friendly.
Supply Chain Dynamics and Cost Structure Realignment
Coffee concentrate economics are being recalibrated by evolving raw material conditions and supply chain design choices. The recent softening of green coffee pricing, driven by expectations of record Brazilian harvests and broader global supply surpluses, has altered the near-term cost environment. While lower input prices can relieve margin pressure, they also introduce new considerations around procurement timing, inventory strategy, and supplier relationships. Firms that treat raw material volatility as a recurring design parameter rather than an episodic disruption are better equipped to maintain cost discipline. This includes diversifying origin exposure, structuring flexible offtake arrangements, and aligning concentrate specifications with cost-efficient processing routes where feasible.
PW Consulting
Supply chain resilience is increasingly tied to operational flexibility. Concentrate manufacturers are evaluating everything from batch sizing and packaging configurations to logistics networks and regional production footprints. In a market where foodservice and industrial processing customers demand reliable availability and predictable lead times, the ability to balance efficiency with responsiveness is becoming a differentiator. Cost structures that incorporate proactive inventory planning, multi-origin sourcing, and format optimization are more likely to sustain profitability through cycles of input price movement. The practical takeaway is that supply chain design is no longer a back-office concern; it is a strategic lever that shapes pricing power, service levels, and customer retention.
Regulatory Clarity as a Strategic Enabler
Regulatory dynamics are also functioning as a growth enabler by clarifying where concentrate products sit within existing compliance frameworks. The distinction between coffee and tea infusions from dried ingredients and juice-based concentrates under FDA Juice HACCP guidance helps reduce uncertainty for coffee-focused manufacturers, provided that labeling and category positioning are managed carefully. In parallel, customs marking exemptions for roasted and instant coffee and certain coffee preparations can simplify trade documentation and reduce administrative overhead for exporters and importers operating across jurisdictions. Where beverage products include juice claims, however, percentage declarations and from-concentrate labeling requirements still apply and must be integrated into product development and packaging processes.
These regulatory nuances are not merely compliance checkboxes; they influence product architecture, market entry sequencing, and labeling investment. Organizations that build regulatory literacy into their formulation and go-to-market planning can reduce time-to-market, avoid rework, and position products more cleanly within their intended categories. As the concentrate market expands across both coffee-centric and hybrid beverage applications, clarity on classification and labeling will increasingly separate operators that scale smoothly from those that encounter avoidable friction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global scale players, specialized concentrate suppliers, and foodservice-oriented manufacturers, each pursuing distinct value propositions. Nestlé and Starbucks exemplify a partnership-driven approach to category expansion, leveraging brand equity and distribution muscle to accelerate cold coffee availability through concentrate formats. Their focus on broad availability and recognizable branding targets mass consumption and beverage manufacturing channels where standardization and reach are paramount. This strategy underscores the continued relevance of scale, but it also highlights the importance of product relevance: even large incumbents must ensure that concentrate formats align with specific usage occasions and preparation expectations.
Finlays represents a more customization-oriented posture, supplying tailored coffee concentrates including cold brew and high-Brix variants for beverage manufacturing and ready-to-drink products. Its emphasis on multiple origins and certifications signals a strategy built on formulation flexibility and sourcing credibility. For industrial and beverage manufacturing customers, this profile can translate into stronger partnership potential, particularly where product differentiation depends on origin selection, processing nuance, or certification requirements. In a market where generic concentrate offerings are increasingly commoditized, the ability to adapt specifications to customer needs becomes a meaningful differentiator.
U.S.-based manufacturers such as Westrock Coffee Company, The J.M. Smucker Company, Keurig Dr Pepper, All American Coffee LLC, Red Diamond Coffee & Tea, Chameleon Cold-Brew, CoolBrew, and Jedwards International illustrate the breadth of domestic concentration activity across private label, retail, and foodservice applications. Some participants emphasize proprietary processing for customized formats, while others focus on convenience-driven foodservice concentrates or organic retail-oriented cold brew products. Red Diamond's Fitz Cold Brew launch, for example, reflects a practical service logic: enabling foodservice operators to deliver premium cold brew with simplified preparation. CoolBrew's proprietary cold-drip process and Chameleon's organic positioning point to differentiation through process identity and category authenticity. These approaches demonstrate that U.S. players are competing not only on volume but also on format design, brand narrative, and channel fit.
International and specialty-oriented operators add further texture to the landscape. Jake-Frut & Jake-Café provides custom branding solutions for concentrated juices and liquid coffee, targeting customers that value packaging and brand integration. Cafeahaus AG DEK specializes in soluble coffees and liquid coffee extracts for food industry and vending applications, an area where compatibility, dosing reliability, and machine-friendly formats matter. Batavia Cold Drip Coffee, with operations spanning the Netherlands and Indonesia, offers bulk liquid cold drip concentrates with customizable recipes and packaging options, an appealing profile for buyers seeking scale without sacrificing formulation input. Together, these companies show that the market is not a simple hierarchy of global giants versus niche suppliers; it is a layered ecosystem where competitive advantage can be built through provenance, customization, service model, or application expertise.
The competitive trajectory appears to be moving toward selective consolidation and simultaneous niche differentiation. Scale players will continue to consolidate advantageous distribution, brand recognition, and processing capacity, especially in broad consumer and foodservice segments. At the same time, new entrants and focused incumbents will likely find room by addressing underserved applications, origin narratives, organic or specialty certifications, and operational pain points such as preparation complexity or format incompatibility. The most durable strategies will be those that combine credible processing capability with clear customer value, whether that value is operational efficiency, flavor consistency, customization, or category positioning. A market with this level of strategic diversity rewards companies that define their positioning precisely rather than attempting to compete across every dimension at once.
Future Outlook: Three Signals to Watch
Looking ahead to the 2026–2032 window, several signals point to where strategic attention should be concentrated.
First, cold coffee adoption will continue to anchor concentrate demand, but the growth logic will increasingly shift from novelty to operational integration. As foodservice and beverage manufacturing customers mature in their use of concentrate formats, the value proposition will depend less on introducing cold coffee and more on improving preparation efficiency, consistency, and scalability. Manufacturers that align concentrate specifications with real-world workflow requirements, including dilution ratios, dispensing compatibility, and batch-to-batch stability, are likely to secure stickier customer relationships. The related opportunity is to design concentrate portfolios for repeatable deployment rather than one-off product launches.
Second, a period of lower input prices can reshape competitive behavior if it leads to complacency in cost management or procurement discipline. Lower green coffee pricing may temporarily ease margin pressure, but it can also obscure the need for robust hedging, origin diversification, and specification-to-cost alignment. Operators that use favorable pricing windows to strengthen supply chain resilience and lock in flexible sourcing arrangements will be better positioned when prices cycle back. The risk is that temporary cost relief encourages volume-driven competition without corresponding value or efficiency gains, which can erode profitability over time.
Third, category boundaries will continue to test labeling and regulatory clarity, especially as beverage concepts blur the line between coffee, juice-adjacent, and hybrid formats. Products that incorporate juice claims, from-concentrate language, or multi-ingredient formulations will face tighter scrutiny on declaration accuracy and consumer communication. This creates both a compliance challenge and an opportunity: companies that develop clean, category-appropriate labeling and transparent product narratives can reduce friction and build trust, while those that treat labeling as an afterthought risk rework, market delays, or consumer confusion. The strategic opportunity lies in treating regulatory and labeling design as part of product architecture rather than a downstream task.
Strategic Recommendations for Decision-Makers
For manufacturers, the immediate priority is to align concentrate development with application-specific value. This means prioritizing processing consistency, customization capability, and preparation simplicity where customer workflows demand it. Investment should be directed toward formats and specifications that reduce customer friction, whether that friction is operational, sensory, or regulatory. In parallel, supply chain strategy should incorporate flexible sourcing and inventory planning so that margin protection is not dependent on any single price environment.
Worldwide Citrus Concentrate Market
For investors, the most relevant question is not whether the market is expanding, but which business models are best configured to capture durable margin and share. Comparative evaluation should focus on processing differentiation, channel fit, customer retention logic, and exposure to raw material cycles. Companies that can demonstrate repeatable concentrate performance, clear application relevance, and disciplined cost management are more likely to translate market growth into sustained profitability. Due diligence should also assess regulatory readiness, especially for products operating near category boundaries or with multi-ingredient formulations.
For procurement and sourcing teams, concentrate selection should be evaluated on total operational impact rather than unit price alone. Dilution performance, shelf stability, equipment compatibility, lead-time reliability, and documentation clarity all influence total cost of ownership. Where feasible, buyers should seek suppliers with proven customization capacity and transparent compliance practices, particularly if product portfolios are expected to expand into hybrid or multi-format use cases. Strategic sourcing relationships, rather than transactional purchasing, will increasingly determine how smoothly concentrate programs scale.
Market-level growth is only one part of the story. The more consequential question is which participants will convert that growth into defensible advantage through better processing, smarter sourcing, and sharper category positioning. Detailed segmentation, regional dynamics, and application-level cost structures provide the granularity needed to make those judgments with confidence. Readers seeking a deeper view of segment performance, competitive benchmarking, and forward scenarios can consult the full PW Consulting report on the worldwide coffee concentrate market for more detailed data and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Coffee Concentrate Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


