



HSA Provider Market 2032: Inside the 11.55% CAGR and 290 Billion Shift

Strategic Trends & Commercial Opportunities in the Health Savings Account Provider Market
Market Overview: Scale, Trajectory, and Core Challenges
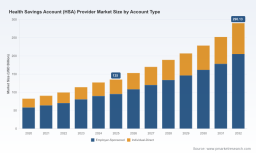
The Health Savings Account (HSA) provider market has matured into a cornerstone of the U.S. consumer-directed healthcare ecosystem, reflecting both structural shifts in insurance design and evolving consumer expectations around health financing. Measured in constant terms over a five-year baseline through 2025, the market has expanded from roughly 82.5 to 135.0 across the referenced period, with projections extending through 2032 pointing to sustained momentum. The forward trajectory implies a compound annual growth rate of approximately 11.55 percent, lifting the market size to nearly 290.1 by the end of the forecast window. This expansion is not merely a function of inflation or administrative growth; it signals a fundamental recalibration of how households and employers approach healthcare spending, savings, and investment.
Worldwide Financial Wellness Benefits Market
Beneath the headline figures, several structural realities define the current operating environment. First, account distribution is heavily weighted toward employer-sponsored arrangements, which dominate the overall composition, while individual-direct accounts represent a meaningful but smaller share. This split underscores the continued reliance on workplace channels for account origination, even as digital enrollment pathways and direct-to-consumer marketing gradually broaden the addressable base. Second, the provider landscape is fragmented across Banks and Financial Institutions, Insurance Carriers, and FinTech and Third-Party Administrators, with no single category achieving outright dominance. That fragmentation creates both distribution frictions and partnership opportunities, as each provider type brings distinct capabilities in compliance, investment access, and user experience. Third, regional concentration remains pronounced, with North America accounting for the overwhelming majority of activity and the rest of the world representing a negligible fraction, highlighting the deeply U.S.-centric nature of the current regulatory and tax framework.
The market also exhibits meaningful concentration at the top, with the largest players collectively holding roughly 48.2 percent of the landscape and the top five approaching 62.4 percent. Such concentration suggests established incumbents have secured durable advantages in employer relationships, compliance infrastructure, and asset accumulation, yet the remaining share leaves considerable room for differentiated entrants and niche platforms. The challenges ahead are equally clear. Providers must navigate the tension between scale-driven margin improvement and the growing expectation for personalized digital experiences, all while operating within a regulatory perimeter that ties account eligibility to qualifying High Deductible Health Plans. Compounding these dynamics, the shift from pure spend accounts to true investment vehicles is reshaping customer expectations, forcing providers to prove out performance, transparency, and long-term value rather than merely facilitating contributions and withdrawals.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Realities
The most visible catalyst for market expansion is the accelerating convergence of financial services and digital health platforms. Modern HSA architectures increasingly embed self-service dashboards, real-time claim adjudication, automatic investment enrollment, and integrated budgeting tools that treat health spending as part of broader household finance. These capabilities reduce administrative burden for employers and improve engagement among account holders, which in turn supports higher asset retention and deeper investment adoption. The trend toward embedding HSA functionality within broader benefits ecosystems—often layered with flexible spending arrangements, health reimbursement arrangements, and emergency savings features—has transformed the account from a standalone tax-advantaged vehicle into a multi-purpose financial hub. Recent industry reporting highlights that assets reached nearly 174 billion across 41.7 million accounts at year-end 2025, with 19 percent year-over-year asset growth and a rising share allocated to investments, signaling that users and sponsors are increasingly comfortable with longer-horizon financial behaviors.
Regulation continues to shape the speed and structure of adoption, not only by defining eligibility but by setting annual contribution limits that influence household behavior and employer design choices. For 2026, the IRS set HSA contribution limits at 4,400 for self-only coverage and 8,750 for family coverage, parameters that guide recurring contributions and encourage year-end planning. Because HSAs must be paired with a qualifying High Deductible Health Plan to preserve tax advantages, any shift in employer insurance strategy, employee cost sensitivity, or plan design directly influences account origination and asset accumulation. The regulatory backdrop also rewards providers that can demonstrate robust compliance, clean reporting, and seamless integration with plan documents and payroll workflows. In practice, the firms that most effectively translate regulatory requirements into friction-free employer onboarding and employee education capture disproportionate share of new accounts and assets.
Demand-side dynamics reinforce this trajectory. Employers are increasingly weighing total rewards packages that blend clinical coverage with financial wellness, recognizing that HSA participation can influence employee retention, productivity, and financial resilience. Individuals, meanwhile, are becoming more deliberate about health spending, investment growth, and portability as job mobility rises and traditional employer relationships become less sticky. This behavioral shift favors platforms that offer clear fee structures, intuitive investment options, and educational support that demystifies contribution strategies, catch-up provisions for older participants, and the interplay between current spending and future growth. The result is a market where user experience and transparency are no longer differentiators but baseline requirements.
Cost structures and operating models are evolving in parallel. As digital onboarding, automated compliance checks, and platform-based integrations reduce marginal handling costs, providers are gaining latitude to compete on value rather than price alone. At the same time, the economics of managing growing asset balances introduce new considerations around recordkeeping, custody, and investment administration. Companies that can align scalable technology with disciplined cost control are better positioned to sustain margins as the market expands, especially when investment assets increasingly represent a meaningful portion of total value. The strategic implication is straightforward: the winners will be those that turn cost efficiency into better user outcomes, not just internal savings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by several well-established players, each leveraging a distinct blend of scale, integration, and product breadth. Fidelity Investments has built a reputation for fee-light HSAs paired with broad investment menus that span stocks, ETFs, and mutual funds, complemented by seamless connectivity to retirement accounts. Its positioning emphasizes low cost and investment flexibility, appealing to account holders who view their HSA as a long-term savings and investment instrument rather than a transactional spend account. HealthEquity has concentrated on employer-sponsored administration at scale, combining compliance rigor with integrated consumer-directed benefits that include FSAs and HRAs. Its strengths lie in analytics, account volume, and enterprise-grade support, and its recent financial results—record revenue of 1.31 billion, over one million new HSAs from sales, and an outlook raised for fiscal 2027 with 17.8 million total accounts and more than 36 billion in assets—illustrate how scale and disciplined execution can compound in a maturing market.
HSA Bank, operating as a division of Webster Bank, blends HSA administration with investment access through brokerage relationships and integrated benefits solutions, while also extending into adjacent pillars of employee financial wellness. Its acquisition of SecureSave to expand into employer-sponsored Emergency Savings Accounts signals a move toward broader financial resilience offerings, allowing employers to bundle health savings with emergency savings in a single wellness narrative. Lively has carved out a modern, digital-first identity with an emphasis on user-friendly tools, transparent pricing, and support for both individuals and small-to-mid employers, positioning itself as an agile alternative to more traditional administrators. Optum Bank leverages its integration within a large health benefits ecosystem to offer HSAs connected to broader care and benefits management, with investment options available through brokerage windows or managed solutions. Bank of America brings a conventional banking footprint with tiered interest rates and basic investment access, appealing to consumers who prioritize familiar banking relationships and integrated account management.
The strategic differences among these players reveal a market that is simultaneously consolidating around scale and differentiating around experience. Incumbents with deep employer relationships and robust compliance infrastructure continue to capture the bulk of new accounts, while newer platforms compete on design, fee clarity, and specialized workflows that reduce administrative overhead for smaller sponsors. The evolution is also visible in product adjacency: providers are extending beyond core HSA administration into emergency savings, wellness incentives, and integrated benefit stacks, recognizing that household financial decisions rarely occur in isolation. This blending of use cases creates opportunities for cross-selling and deeper engagement, but it also raises the bar for operational discipline, as each new feature must be supported by clear governance and reliable user communication.
Concentration patterns suggest that while the largest players enjoy meaningful advantages in distribution and asset accumulation, the market remains open to targeted innovation. The gap between top-tier scale and the long tail of smaller providers creates a natural environment for partnerships, platform integrations, and geographic or segment specialization. At the same time, the expectation for investment adoption and digital fluency is pulling even traditional providers toward more modern interfaces and transparent fee logic. The net effect is a landscape in flux: scale still matters, but differentiation through experience, ecosystem fit, and adjacent financial wellness capabilities is increasingly decisive.
Strategic Outlook: Three Trends Shaping the Next 3-5 Years
First, the HSA will continue its evolution from a spend account to a core investment vehicle within household finance. As assets grow and a larger share is allocated to investments, providers that offer well-structured investment options, clear performance reporting, and educational support will deepen engagement and retention. The commercial opportunity lies in building trust around long-term outcomes, including guidance on contribution strategies, catch-up eligibility, and the interaction between current healthcare spending and future growth. Platforms that can communicate value without complexity are likely to capture more assets and fewer lapses.
Second, financial wellness bundling will become a standard expectation rather than a differentiator. Employers and individuals increasingly view health savings alongside emergency savings, retirement readiness, and benefits transparency as part of a single financial resilience strategy. Providers that can integrate these use cases in a coherent, compliant manner will gain preference in employer selection and individual adoption. The upside is higher engagement and broader account utility; the risk is operational complexity and the potential for feature sprawl that dilutes clarity.
Third, digital experience and fee transparency will increasingly separate leaders from laggards. As account holders compare platforms on usability, investment access, and total cost, providers that invest in self-service design, proactive education, and straightforward fee logic will stand out. The uncertainty here is twofold: regulatory parameters can change with annual limits and eligibility rules, and competitive pressure may compress fee-based economics, pushing providers to rely more on scale, ecosystem partnerships, and value-added services to sustain margins.
Actionable Recommendations for Decision-Makers
For employers and plan sponsors, the priority is to treat HSA design as a strategic component of total rewards rather than an administrative checkbox. That means selecting providers based on integration quality, fee clarity, investment readiness, and employer analytics, while pairing account access with education that improves participation and asset retention. Sponsors should also evaluate adjacent financial wellness capabilities, such as emergency savings integrations, as part of a cohesive offer that supports employee resilience and engagement.
Health Products Market
For investors and market participants, the most durable opportunities lie in platforms that combine scalable compliance infrastructure with modern user experience and credible investment pathways. Attractive theses typically emphasize asset growth, investment adoption trends, and the ability to expand into adjacent wellness use cases without sacrificing operational discipline. Caution is warranted where differentiation rests primarily on marketing claims without transparent fee structures, reliable service levels, or clear employer value.
PW Consulting Information & Electronics Research Center
For technology providers and procurement teams, the mandate is to prioritize interoperability, clean data flows, and enrollment simplicity. Solutions that reduce onboarding friction, automate compliance checks, and deliver actionable reporting will earn preference in a market where scale and experience increasingly converge. Timely, granular intelligence on segment dynamics, provider positioning, and adoption patterns can sharpen procurement decisions and reduce integration risk, especially as the market continues to reward providers that align product design with real user behavior. For those seeking deeper segmentation, competitive benchmarking, and tailored strategic guidance, PW Consulting’s full research report provides detailed breakdowns and customized recommendations to support concrete next steps.
For detailed analysis of this topic, please visit the official page: Health Savings Account (HSA) Provider Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


