



Underwater Vessel Repair Services Market: Why 5.15% CAGR Reshapes Growth Through 2032

Underwater Vessel Repair Services Market: Strategic Trends and Commercial Opportunities (2025-2032)
Market Landscape and Critical Challenges
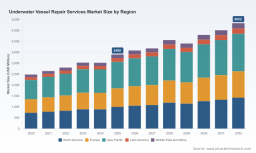
The underwater vessel repair services market has established itself as a critical enabler of maritime operational efficiency, bridging the gap between scheduled dry-docking intervals and unplanned maintenance events. Valued at approximately USD 3.4 billion in 2025, the industry has navigated a period of recalibration between 2020 and 2025, recovering from pandemic-era disruptions while absorbing structural shifts in fleet management. Projections indicate a compound annual growth rate of 5.15 percent through 2032, positioning the market to surpass USD 4.8 billion by the end of the forecast horizon. This expansion reflects not merely a return to baseline but a fundamental rethinking of how vessel uptime, hull integrity, and propulsion efficiency are managed across commercial, defense, and offshore segments.
At its core, the market addresses a persistent operational constraint: dry-docking is expensive, time-consuming, and often misaligned with commercial sailing schedules. Underwater repair techniques have matured into a viable alternative for specific maintenance tasks, allowing operators to extend service intervals, reduce port滞留 time, and maintain continuous cargo or mission cycles. Classification societies, port authorities, and ship operators have gradually built familiarity with these methods, creating a regulatory and operational foundation that supports further deployment. Yet the trajectory is not linear, and several structural friction points will define how the market evolves over the next cycle.
One defining challenge lies in the variability of regulatory acceptance and workforce qualification standards across jurisdictions. While established classification frameworks provide guidance, the interpretation of underwater intervention scope, material compatibility, and post-repair inspection rigor differs significantly between regions and flag states. Operators weighing underwater solutions against traditional dry-dock repair must navigate a patchwork of approvals, which introduces scheduling uncertainty and increases due diligence overhead. This fragmentation is particularly pronounced for cross-regional fleets that must satisfy multiple oversight regimes without compromising standardization.
A second pressure point centers on technical boundaries and misapplication risk. Not every maintenance task is suitable for underwater execution. Complex weld repairs, structural modifications involving thick plating, or systems requiring high-precision tolerances still demand controlled dry environments. The strategic risk for operators and service providers alike is overpromising underwater feasibility in contexts where dry-dock reliability remains superior. A disciplined segmentation of repair types, paired with clear performance criteria, is becoming essential to avoid downtime extensions, rework cycles, and reputational exposure.
A third tension involves cost perception versus long-cycle value. Underwater intervention can offer compelling short-term savings in reduced port time and preserved schedules, but the economics depend heavily on fleet type, voyage pattern, and access logistics. For some operators, particularly those with tightly clustered routes or high utilization profiles, the value proposition is immediate. For others, the calculus is more nuanced, requiring scenario modeling that accounts for repositioning costs, weather windows, and the opportunity cost of delayed maintenance. As fleet operators refine their total-cost-of-ownership models, service providers that can quantify and prove lifecycle value will gain a structural advantage over those competing primarily on headline price.
Key Drivers Shaping Market Trajectory
Technological Innovation and the Expansion of Feasible Scope
Underwater repair has moved beyond basic cleaning and minor interventions into a broader and more technically differentiated service envelope. Advances in remotely operated tooling, acoustic and ultrasonic inspection methods, and specialized coating reapplication techniques are extending the range of tasks that can be executed with confidence while vessels remain in the water. Precision propeller work, targeted steel plate interventions, and underside inspection routines are increasingly supported by structured workflows that integrate pre-task sonar mapping, real-time monitoring, and post-work verification.
What matters strategically is not only the capability itself but the data trail that accompanies it. Operators are progressively treating underwater maintenance events as data-generating touchpoints, where hull condition, biofouling progression, and component wear can be documented without removing the vessel from service. This shift is turning repair from a purely reactive cost center into a source of operational intelligence. Fleet managers evaluating maintenance strategies are beginning to weigh not just the immediate repair outcome but the broader visibility gained into asset condition. Service providers that can pair technical execution with standardized reporting, repeatable measurement protocols, and integration into fleet maintenance planning systems are positioning themselves at a premium tier of the market.
Policy, Environmental Regulation, and Port-Mandated Maintenance Rhythms
Environmental regulation continues to reshape maritime operating economics. Expectations around emissions performance, hull efficiency, and antifouling management are pushing operators to treat hull condition as an efficiency variable rather than a purely structural concern. A deteriorating or heavily fouled hull increases resistance, raises fuel consumption, and complicates compliance planning. This regulatory backdrop has renewed attention on maintenance timing, because delays that allow hull degradation to accumulate can become expensive in both fuel and inspection exposure.
At the same time, port-state and coastal requirements are reinforcing the need for structured inspection and repair programs. Compliance documentation, survey readiness, and predictable maintenance intervals are becoming more tightly linked to commercial access and operational flexibility. Underwater repair services that align with these compliance rhythms can offer a meaningful advantage: they help operators maintain survey readiness without necessarily triggering full dry-dock campaigns for every maintenance decision. The strategic implication is that the value of underwater services is increasingly tied to regulatory alignment and documentation quality, not only to mechanical intervention. Providers that understand how to map their offerings to inspection and compliance cycles are better placed to win recurring contracts and long-term service relationships.
Underwater Drone Market
Demand-Side Shifts in Fleet Utilization and Uptime Prioritization
Commercial shipping, offshore operations, and naval programs share a common pressure: schedule integrity is increasingly non-negotiable. Cargo routing complexity, charter market expectations, and mission-critical operational continuity all increase the penalty of unplanned downtime. In that environment, the traditional model of clustering maintenance into extended dry-dock periods is being reassessed. Operators are more willing to evaluate partial intervention strategies that preserve sailing schedules while addressing targeted maintenance needs.
This demand-side evolution is not uniform, but it is directional. Vessels with high utilization profiles or those operating on thin margin logic are especially sensitive to downtime costs. For them, underwater repair services represent a way to manage priority maintenance items without interrupting revenue-generating activity. For other segments, the appeal lies in risk mitigation: addressing localized deterioration early, before it escalates into broader structural or propulsion issues. The commercial logic here is straightforward but often underutilized. The market opportunity is expanding not because every repair should be done underwater, but because operators now have a more credible option to sequence maintenance intelligently, protect uptime, and reduce the volatility of repair timing.
Cost Structures, Access Logistics, and the Reassessment of Total Maintenance Economics
The economics of vessel repair are being reconsidered through a broader lens that includes repositioning, port fees, opportunity cost, and schedule disruption. Underwater repair does not automatically win on price, but it can alter the economic equation when total operational impact is measured rather than the isolated cost of the intervention. This is especially relevant where vessels face long wait times for dry-dock slots, where port availability is constrained, or where extended downtime would cascade across multiple voyages or missions.
At the same time, cost pressure is pushing service providers to improve efficiency. Mobilization planning, crew deployment, tooling standardization, and weather-dependent access windows all influence margin stability. The operators that succeed are those that can reduce variability: repeatable deployment models, clearly defined service scopes, and credible assessment processes that separate suitable underwater tasks from those requiring dry-dock resolution. In practice, this is creating a market dynamic where professionalization and process reliability are becoming as important as technical skill. The competitive winners are increasingly those who can offer predictability, because predictability translates into lower operational risk for the ship operator and better scheduling economics for the service provider.
Competitive Landscape and Leading Strategies
The competitive field in underwater vessel repair is defined less by scale dominance than by specialization, geographic reach, and the ability to deliver repeatable technical results with minimal operational disruption. Companies that have built strong reputations typically combine deep underwater technical capability with disciplined project management, clear scope definition, and established relationships with operators and classification bodies. Rather than competing across every possible service category, leading providers tend to concentrate on a subset of capabilities where they can evidence consistent performance and reduce the customer's perceived execution risk.
A company such as Hydrex Underwater Technology has built its positioning around underwater interventions that reduce dependence on dry docking for specific maintenance needs, including steel plate replacement, propeller polishing, and blade straightening performed while the vessel remains in the water. The strategic significance of this profile lies in the operational message it communicates: targeted underwater repair can be executed as a structured service rather than as an improvised field activity. Providers with this orientation typically differentiate through procedure standardization, deployment speed, and the ability to present underwater work as a planned maintenance option with defined outcomes. In a market where trust and repeatability matter, that positioning can support premium engagement models and long-term fleet relationships.
Subsea Global Solutions represents a complementary strategic posture, emphasizing commercial underwater repair and maintenance for hulls, rudders, and propulsion systems on large vessels. The commercial focus here is important because large vessel operators face acute downtime sensitivity and often operate under tight port and routing constraints. Service providers that can deploy quickly, work across major maritime hubs, and address propulsion and hull systems with credible inspection and verification practices are better positioned to capture recurring commercial demand. In this segment, advantage is often derived from responsiveness, geographic coverage, and the capacity to fit repair activities into live operational schedules rather than disrupting them.
Looking at the market structure more broadly, several evolution patterns are emerging. First, there is a clear trend toward consolidation of reputation around a limited number of technically credible providers in each major region. Because underwater repair carries execution risk and regulatory visibility, operators tend to favor vendors with established track records and demonstrable procedure discipline. This concentration does not imply a fully consolidated market, but it does suggest that credibility and proof of performance are becoming central competitive currencies.
Second, differentiation is increasingly driven by service design rather than by the underwater act alone. Providers are expanding into inspection-linked maintenance, condition documentation, and planning support that helps operators decide when underwater intervention is appropriate and when dry-dock remains the stronger option. This advisory dimension can strengthen customer stickiness because it connects repair services to broader fleet maintenance strategy. It also helps providers avoid the commoditization trap by moving the conversation from unit price toward operational outcomes.
Third, the entry landscape is creating pockets of new competition in specific niches. Regional operators with strong port access, specialized tooling, or experience in particular vessel classes can compete effectively against broader international providers by offering faster mobilization and closer local relationships. At the same time, large and diversified marine service organizations may seek to integrate underwater repair into wider maintenance portfolios, using it as one element within a broader uptime and asset-integrity offering. The result is a market that is neither purely fragmented nor fully consolidated, but strategically layered, with competition intensifying where reliability, access, and scope definition intersect.
Future Trends and Commercial Implications (2026-2032)
Over the next three to five years, the underwater vessel repair market is likely to evolve along a few recognizable trajectories, each carrying distinct commercial implications. One is a gradual expansion of condition-based maintenance logic into underwater work. As hull and propulsion data become more routinely integrated into fleet planning, operators will increasingly seek maintenance providers that can link inspection findings directly to intervention recommendations, prioritizing underwater repairs where they are genuinely advantageous and deferring others to dry-dock when warranted. This will reward providers that can deliver assessment-led services with clear technical justification, rather than those offering only task-based execution.
A second trend is the growing premium on access, speed, and mobilization reliability. Port congestion, dry-dock availability constraints, and tighter operational schedules will continue to make responsiveness a differentiating factor. Commercial opportunity will tilt toward providers with strong regional coverage, efficient deployment models, and the ability to slot underwater maintenance into live operations with minimal disruption. This favors service designs that reduce setup time, standardize tool and crew deployment, and maintain consistent quality across repeated interventions.
A third trend is heightened accountability around documentation and classification alignment. As regulators, ports, and operators place greater emphasis on survey readiness and performance evidence, underwater repair providers will be expected to demonstrate not only that a repair was completed, but that it was completed in a verifiable and repeatable manner. This will likely increase demand for structured reporting, standardized inspection inputs, and maintenance records that integrate cleanly into fleet management processes. Providers that treat documentation as part of the service product, not an afterthought, will have an advantage in securing recurring work with larger fleets and institutional operators.
These trends also carry uncertainty. The market may face headwinds if classification or jurisdictional expectations diverge further, if underwater techniques are misapplied to inappropriate repair types, or if cost pressure pushes some operators toward lower-quality service offerings that undermine confidence in the broader category. Another source of variability is environmental and weather-dependent access, which can influence mobilization economics and schedule reliability. The commercial opportunity, therefore, is strongest for providers and buyers who approach underwater repair as a managed component of fleet strategy, with clear scope rules, credible verification, and realistic expectations about where the technique adds value and where it does not.
PW Consulting Automotive & Machinery Research Center
Strategic Implications for Decision-Makers
For operators and procurement teams, the priority is to treat underwater repair as a structured option within the maintenance planning process, not as an ad hoc substitute for dry-dock work. That means defining which hull, propulsion, and inspection tasks are suitable for underwater intervention, establishing performance criteria, and ensuring that service selection is based on total operational impact rather than unit price alone. Contracts and service agreements should make scope boundaries explicit, including inspection inputs, verification expectations, and the conditions under which dry-dock referral remains necessary.
For investors and market entrants, the opportunity lies in capability depth and process reliability rather than in broad but shallow service coverage. Segments tied to hull maintenance, propulsion-related intervention, and inspection-linked repair are likely to remain central to demand, but durable advantage will come from repeatable execution, credible documentation, and the ability to reduce mobilization and scheduling friction. Providers that can connect technical service to fleet uptime logic, and that can evidence performance consistently across multiple vessel types and regions, are better positioned to capture premium and recurring demand over time.
For manufacturers and technology providers supporting the repair ecosystem, the strategic opening is to align tooling, inspection, and coating solutions with the practical demands of underwater deployment. Solutions that improve precision, reduce setup variability, or strengthen the quality and usability of inspection data are likely to gain traction, especially as operators increase their reliance on maintenance data for decision-making. The most useful innovations will be those that make underwater work more predictable, better documented, and easier to integrate into broader asset-management workflows.
Underwater Hull Cleaning Service Market
The commercial trajectory of the underwater vessel repair services market will be shaped less by universal adoption than by disciplined use, credible execution, and alignment with operational and regulatory realities. Decision-makers who build that discipline into their maintenance strategy now will be better placed to capture value as the market matures toward 2032. For those seeking a more granular view of service segments, regional demand patterns, and competitive positioning across vessel types and application areas, a detailed research report can provide the supporting segmentation data and scenario framing needed for planning.
For detailed analysis of this topic, please visit the official page: Underwater Vessel Repair Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


