



Worldwide Label Rolls Market: Why Asia Pacific & 4.65% CAGR Redefine Growth Strategy

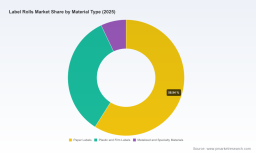
Strategic Trends and Commercial Opportunities in the Worldwide Label Rolls Market
Market Overview and Core Challenges
The worldwide label rolls market has established itself as a foundational component of the global packaging ecosystem. In 2025, the industry reached an estimated revenue valuation of 14.25 billion USD, reflecting consistent expansion over the preceding five years. Historical data indicates a trajectory from approximately 11.35 billion USD in 2020, driven by steady industrial activity and packaging demand across multiple sectors. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.65 percent through 2032, with revenue expected to approach 19.59 billion USD by the end of the forecast period. This growth trajectory underscores the sector's resilience, yet it also highlights a market that is evolving faster than traditional supply chains can accommodate.
Despite the positive outlook, the industry faces several structural challenges that will define competitive positioning in the coming years. One of the most pressing issues is the tension between rising material costs and the demand for sustainable solutions. Producers of thermal paper and label substrates are navigating volatile input markets, with pricing pressures becoming particularly acute in early 2026. This cost environment forces manufacturers to make difficult trade-offs between margin preservation and competitive pricing, especially in price-sensitive segments.
A second critical challenge lies in the shifting regulatory landscape. Extended producer responsibility frameworks are gaining traction at regional levels, altering the incentive structures for packaging materials. As jurisdictions introduce new requirements for recyclable and responsibly sourced materials, label manufacturers must adapt their product portfolios and supply chain practices. These regulatory changes are not merely compliance exercises; they are reshaping procurement priorities and product design standards across end-use industries.
Finally, the market is experiencing a technological inflection point. Digital printing capabilities are maturing rapidly, enabling shorter runs, greater customization, and faster time-to-market for brands. However, integrating digital workflows into mainline production requires capital investment and operational rethinking. Companies that fail to align their manufacturing capabilities with these technological shifts risk losing relevance in segments where agility and personalization are becoming table stakes.
Key Drivers of Market Evolution
Several interconnected forces are propelling the label rolls market forward, each carrying distinct implications for strategic planning. Technology innovation stands out as a primary catalyst. The adoption of linerless label formats and perforated roll designs is reducing material waste while streamlining application processes. Recent product launches have demonstrated how removing backing paper can simplify handling and lower environmental footprints simultaneously. These innovations are not niche experiments; they represent a broader shift toward leaner material usage and more efficient downstream processing.
Regulatory and policy developments are equally influential. State-level extended producer responsibility initiatives are creating new demand signals for pulp-based and sustainably produced materials. As governments encourage packaging that aligns with circular economy principles, label manufacturers are being pushed to source materials that meet evolving standards. This dynamic is not uniform across regions, but the direction of travel is clear: compliance is increasingly tied to market access and customer preference.
On the demand side, brand owners are prioritizing labeling solutions that support sustainability claims and supply chain transparency. Consumers and retailers alike are scrutinizing packaging materials more closely, forcing manufacturers to provide documentation, certifications, and material traceability. This shift is particularly pronounced in food, beverage, and personal care segments, where labeling plays a critical role in communicating product attributes and regulatory compliance. The demand for labels that perform reliably while meeting sustainability criteria is reshaping procurement specifications and vendor selection criteria.
Labelling Market
Supply chain and cost dynamics complete the picture. Input cost pressures have been evident in recent months, with thermal paper producers implementing price increases and broader printing material indices reflecting elevated cost environments. At the same time, certain film substrates are experiencing demand-driven pricing adjustments linked to e-commerce growth and food packaging needs. Tariff considerations on raw materials add another layer of uncertainty, making supply chain diversification and hedging strategies more important than ever. Companies that can secure stable input sources or pass through cost changes transparently will be better positioned to maintain profitability.
Competitive Landscape and Leading Strategies
The competitive environment in the label rolls market is characterized by a mix of established multinational suppliers and specialized regional players. The top five companies collectively account for a significant share of market revenue, yet the concentration levels indicate room for competitive maneuvering. This structure suggests that while scale advantages matter, differentiation through material innovation, sustainability credentials, and service capabilities remains a viable path for both incumbents and challengers.
Leading manufacturers are pursuing distinct strategic positions. Some companies are leveraging their global production networks and broad material portfolios to serve diverse end-use industries, emphasizing reliability and volume capacity. Others are focusing on specialty substrates, such as thermal papers, self-adhesive films, and sustainable label stocks, targeting segments where performance and compliance requirements are particularly stringent. A recurring theme among top performers is the integration of sustainability into core product strategy, with initiatives spanning material sourcing, waste reduction, and recyclable label formats.
Label Release Paper Market
Recent developments illustrate how these strategies are playing out in practice. Innovations in linerless label rolls have garnered recognition for reducing backing paper waste and enabling single-step application, signaling a growing appreciation for efficiency and environmental benefits. Simultaneously, price adjustments in thermal paper grades highlight the reality of input cost pressures and the need for proactive pricing and procurement strategies. The broader maturation of digital printing for labels and packaging is also reshaping competitive dynamics, as manufacturers who can support digital workflows and short-run flexibility gain an edge in brand-driven applications.
PW Consulting
The market is likely to see continued evolution through both consolidation and specialization. Larger players may pursue acquisitions to expand geographic reach or deepen material expertise, while smaller firms may carve out niches in sustainable materials, thermal solutions, or regional service networks. New entrants with novel substrate technologies or digital integration capabilities could also disrupt established routines. For decision-makers, the key is to monitor not just market share movements but the underlying strategic bets companies are making around sustainability, technology, and supply chain resilience.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to shape the label rolls market. First, sustainability-driven material innovation will accelerate. Linerless formats, recyclable substrates, and responsibly sourced papers are expected to move from niche offerings to mainstream considerations, especially as regulatory frameworks and customer expectations tighten. Companies that invest early in sustainable label solutions will be better positioned to capture demand from brand owners seeking to align packaging with environmental commitments.
Second, digital integration will become a more central element of label production and application. As digital printing matures for mainline use, the ability to support variable data, shorter runs, and rapid design changes will become increasingly valuable. This trend creates opportunities for suppliers that can bridge material supply with digital workflow compatibility, enabling customers to respond faster to market shifts and consumer preferences.
Third, cost management and supply chain agility will remain critical success factors. Input price volatility, tariff uncertainties, and regional regulatory variation will continue to test margins and planning stability. Businesses that diversify sourcing, develop transparent pricing models, and build flexible production systems will be more resilient. At the same time, there is a risk that overinvestment in any single material pathway could leave companies exposed if demand patterns or regulatory requirements shift unexpectedly.
Actionable Guidance for Decision-Makers
For manufacturers, the priority should be aligning product portfolios with the dual demands of performance and sustainability. This means evaluating material choices, investing in linerless or recyclable options where feasible, and ensuring that production capabilities can support digital and short-run requirements. Building flexibility into manufacturing lines and supplier relationships will help navigate cost volatility while capturing emerging opportunities.
Investors should focus on companies demonstrating clear strategies around sustainable materials, digital readiness, and supply chain resilience. Market growth is positive, but the distribution of value will depend on execution. Monitoring pricing power, innovation pipelines, and regulatory adaptability will provide early signals of which players are likely to compound value over the forecast period.
Procurement and sourcing teams should prioritize transparency and diversification. With input costs fluctuating and regional regulations evolving, relying on single-source suppliers or rigid contracts increases exposure. Exploring alternative substrates, negotiating flexible pricing mechanisms, and aligning specifications with future regulatory expectations can reduce risk while supporting longer-term cost stability. In all cases, access to detailed, up-to-date market intelligence is essential for making informed choices. For those seeking deeper segmentation data, company-level profiling, and tailored strategic recommendations, the full research analysis provides a more granular view of the opportunities and trade-offs ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Label Rolls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


