



Small Molecule Liquid Chromatography Columns: Why 6.12% CAGR Redefines the Market

Strategic Horizons: Navigating Growth and Innovation in the Global Small Molecule Liquid Chromatography Columns Market
Market Overview and Core Challenges
The global market for small molecule liquid chromatography columns is entering a phase of sustained, structured expansion. Valued at approximately $2,185.4 million in 2025, the sector is projected to surpass $3.3 billion by 2032, advancing at a compound annual growth rate of 6.12 percent. This trajectory reflects a mature yet evolving landscape where analytical precision, regulatory compliance, and operational efficiency converge. Historical performance from 2020 through 2025 demonstrates a consistent upward curve, driven by decades of method standardization and the entrenched role of chromatography in pharmaceutical development, quality control, and analytical research. The market remains heavily shaped by a concentrated competitive environment, where a handful of established manufacturers command significant share and benefit from deep technical portfolios, longstanding customer relationships, and integrated workflow solutions.
Despite the favorable growth trajectory, the industry faces structural challenges that will define competitive outcomes over the next several years. First, method validation and regulatory rigor are raising the performance threshold for column manufacturers. Analytical laboratories and pharmaceutical developers increasingly require columns that deliver reproducible retention times, minimal bleeding, and predictable lot-to-lot consistency, especially when methods must support regulatory filings or routine quality control. Columns that cannot meet these demands risk exclusion from validated workflows, regardless of price advantage. Second, the sector is contending with evolving cost and supply chain pressures. Material sourcing, manufacturing precision, and distribution logistics all influence margins, while end-users are placing greater emphasis on total cost of ownership rather than upfront purchase price. This shift rewards suppliers that can demonstrate longer column life, reduced re-equilibration time, and lower failure rates in high-throughput environments. Third, the market is experiencing a quiet but meaningful transformation around sustainability and environmental impact. Laboratories and procurement teams are increasingly scrutinizing the environmental footprint of consumables, from manufacturing processes to waste generation during method development and routine analysis. Suppliers that proactively address these expectations through certified practices or greener product design are gaining a subtle but growing credibility advantage.
Ion Chromatography Column Market
These dynamics create a market that is expanding but not undifferentiated. Growth is concentrated where technical reliability, regulatory alignment, and operational value intersect. Companies that treat columns as simple consumables risk being commoditized, while those that embed performance assurance, method support, and lifecycle value into their offerings are better positioned to capture share in an increasingly discerning buyer environment.
Chromatography Columns Market
Key Drivers Shaping Market Trajectory
Several interconnected forces are accelerating demand and reshaping competitive expectations across the small molecule liquid chromatography column market. The most prominent is continuous technical innovation in column chemistry and particle architecture. The shift toward highly efficient separations has reinforced demand for core-shell designs, inert surface treatments, and chemistries that tolerate challenging matrices without sacrificing resolution. Recent product activity underscores this direction. In September 2025, Agilent Technologies introduced the Altura Ultra Inert HPLC column series, aimed at improving performance with metal-sensitive small molecules and expanding applicability to peptide-related workflows. Earlier in the year, Waters Corporation expanded its MaxPeak Premier reversed-phase portfolio with preparative OBD columns designed for the purification of small molecules, peptides, and oligonucleotides. These launches illustrate how manufacturers are extending column capabilities beyond routine analytical use into purification and more demanding analyte profiles, effectively broadening the value proposition of a single product platform.
Regulatory and quality expectations are acting as a second powerful driver. The analytical procedure development guidance from the U.S. Food and Drug Administration emphasizes validated methods for small molecule pharmaceutical analysis, reinforcing the need for consistent column performance within HPLC workflows. In parallel, the United States Pharmacopeia maintains listings of chromatographic columns by brand for compendial methods, providing a framework for equivalence and reproducibility without endorsing specific suppliers. This environment rewards manufacturers that can document performance, support method transfer, and reduce variability across lots. It also increases the barrier to entry for undifferentiated products, since laboratories are less willing to risk method robustness on unproven hardware. A related signal of this trend is the growing attention to environmental accountability in manufacturing and use. Waters Corporation’s achievement of My Green Lab ACT Ecolabel certification for 42 LC columns reflects a broader movement toward transparency in the environmental impact of laboratory consumables. While sustainability alone does not drive purchasing decisions, it increasingly complements technical and compliance considerations in supplier evaluations.
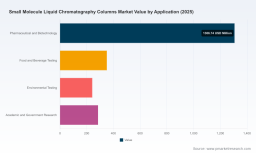
Demand-side behavior is changing as well. Pharmaceutical and biotechnology organizations continue to represent the largest application segment, where small molecule analysis remains central to drug development, impurity profiling, stability testing, and quality control. At the same time, food and beverage testing, environmental monitoring, and academic or government research are sustaining steady demand for reliable separation tools. Across these sectors, users are seeking columns that reduce method development cycles, improve throughput, and minimize rework. This creates a preference for products that combine high efficiency with practical robustness, especially in settings where instrument time and analyst capacity are constrained. The result is a buyer mindset oriented toward performance assurance and workflow efficiency rather than price alone.
Supply chain and cost structure dynamics are reshaping how value is delivered and captured. Manufacturing precision, packing consistency, and quality control are critical differentiators because they directly affect column longevity and reproducibility. At the same time, regional demand patterns are encouraging suppliers to think more carefully about production footprint and distribution responsiveness. YMC Co., Ltd. broke ground on an expanded manufacturing facility in May 2025 to strengthen production of DAC columns and small molecule chromatography products for the Americas and Europe, a move that signals the importance of aligning capacity with regional demand and shortening supply pathways. GL Sciences followed a similar product-focused trajectory in November 2025 with the release of an Inertsil Hybrid-C18 HPLC column designed for enhanced alkali resistance in pharmaceutical applications. These developments suggest a market in which innovation is not limited to chemistry alone; it also encompasses manufacturing scale, material durability, and the ability to serve diverse application requirements without sacrificing consistency.
Taken together, these drivers point to a market where growth is earned through demonstrated reliability, regulatory readiness, and operational value. Suppliers that align product development with validation needs, support faster method workflows, and strengthen manufacturing and distribution resilience are best placed to convert market expansion into sustained share gains.
Competitive Landscape and Leading Strategies
The competitive structure of the small molecule liquid chromatography column market is defined by a concentrated group of technically advanced manufacturers, each pursuing differentiation through product architecture, application focus, and workflow integration. Waters Corporation, Agilent Technologies, and Thermo Fisher Scientific hold particularly prominent positions, supported by broad portfolios, established reputations, and deep ties to pharmaceutical and quality control environments. Their strategies tend to revolve around offering a wide range of separation modes, particle sizes, and formats while reinforcing performance claims through advanced surface technologies, inert designs, and preparative capabilities. Shimadzu Corporation contributes with column series built around specialized packing technologies that support small molecule workflows in pharmaceutical and quality control settings, while Phenomenex emphasizes high-efficiency core-shell and traditional chemistries tailored for pharmaceutical, clinical, and research use.
A second tier of highly focused competitors adds further differentiation through specialty chemistries and application-specific engineering. Restek Corporation provides Raptor and Ultra columns designed for reliable small molecule separations across pharmaceutical and environmental applications, emphasizing robustness across diverse matrices. YMC Co., Ltd. brings more than forty years of experience in analytical and preparative chromatography, with a strong emphasis on packing materials and columns for pharmaceutical purification and analysis. GL Sciences Inc. competes through Inertsil and InertSustain series that prioritize alkali resistance and inertness for pharmaceutical and chemical analysis. Tosoh Bioscience offers TSKgel columns suited to analytical and process applications, while Merck KGaA, through its MilliporeSigma and Supelco presence, supplies a diverse set of HPLC and UHPLC columns spanning monolithic, fused-core, and conventional designs. This layered competitive structure means that leadership is not defined solely by scale; it is also shaped by niche strength, chemical expertise, and the ability to support specialized workflows.
Recent company actions reveal how these players are translating strategy into market position. Agilent’s Altura Ultra Inert series targets metal-sensitive analytes and extends relevance into peptide-related applications, illustrating a move toward inertness as a performance differentiator. Waters’ expansion of MaxPeak Premier reversed-phase columns into preparative OBD formats reflects an effort to bridge analytical and purification workflows, increasing the strategic value of its column portfolio for biopharma and small molecule development. YMC’s manufacturing expansion indicates a capacity and regional responsiveness play, while GL Sciences’ alkali-resistant Hybrid-C18 column demonstrates a focus on durability and method flexibility in pharmaceutical use. Collectively, these moves suggest that leading companies are investing not just in incremental improvements but in extending the functional boundaries of their columns and reinforcing supply-side capability.
The market is likely to continue evolving along two parallel tracks. On one hand, consolidation pressure may persist among larger players seeking to broaden portfolios, streamline offerings, and capture cross-selling opportunities across analytical and purification workflows. On the other hand, specialization will remain valuable, particularly for companies that can address difficult analytes, harsh mobile phases, or highly regulated method environments with clearly documented performance. New entrants face a challenging environment because compendial listings, validation expectations, and established supplier relationships create meaningful inertia. However, opportunities exist for firms that bring genuinely distinct chemistry, demonstrable inertness, or superior lot-to-lot consistency to segments where current solutions still involve trade-offs. The competitive frontier is thus shifting from broad product availability toward proven performance, regulatory alignment, and the ability to reduce total analytical risk for the end user.
Future Trends and Commercial Opportunities
Over the next three to five years, the small molecule liquid chromatography column market is likely to be shaped by a few clear trends that carry direct commercial implications. The first is the continued premium on inertness and chemical resilience. As methods grow more demanding and analyte profiles become more varied, columns that resist metal interactions, tolerate wider pH ranges, and maintain stability across extensive use will gain preference. This creates an opportunity for suppliers to differentiate through surface engineering, packing consistency, and validation support that reduces uncertainty in method transfer and routine operation. Products positioned around durability and reproducibility can command stronger loyalty in settings where failed runs and re-analysis carry high operational costs.
A second trend is the tightening connection between column performance and regulatory and compendial expectations. As method validation becomes more central to pharmaceutical workflows, suppliers that provide robust documentation, lot consistency, and clear equivalence pathways will be better positioned to remain included in approved methods. This trend favors companies that invest in quality systems, technical support, and transparent performance data. It also opens the door for service-oriented value propositions, where column selection is paired with method development assistance, training, or workflow optimization. In effect, the commercial opportunity is shifting from selling a consumable to enabling a more predictable analytical process.
A third trend is the gradual realignment of manufacturing and supply strategies around regional demand and resilience. Expanding production capacity in key markets, improving distribution responsiveness, and stabilizing material supply can become competitive advantages, especially when paired with strong product performance. While sustainability and environmental certification are not yet primary purchasing drivers everywhere, they are increasingly part of supplier evaluation and may become more influential as laboratory sustainability programs mature. Companies that proactively address these expectations can strengthen their positioning with procurement teams and institutional customers that weigh environmental impact alongside technical merit.
PW Consulting
These trends are not without risk. Overinvestment in narrowly defined chemistries could leave suppliers exposed if application needs shift faster than anticipated. Pricing pressure may intensify in commoditizing segments, particularly where differentiation is weak. Regulatory expectations can also evolve, altering what qualifies as acceptable method support or documentation. Even so, the overall direction favors suppliers that combine technical excellence with operational reliability and clear alignment to end-user priorities. The commercial opportunity lies in turning performance into trust, and trust into recurring share in validated, high-value workflows.
Actionable Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to reinforce differentiation where it matters most to validated workflows and demanding applications. This means continuing to invest in inertness, chemical durability, and packing consistency while strengthening documentation, method support, and lot-to-lot assurance. Companies should also evaluate whether their portfolios adequately cover both analytical and preparative needs, since workflows that bridge separation and purification can increase the strategic value of a column line. Where capacity or regional responsiveness is constrained, targeted investment in production and distribution can become a meaningful competitive lever.
For investors, the most attractive exposure lies in suppliers that can demonstrate durable differentiation rather than broad but undifferentiated product lists. Focus on firms with clear technical moats, strong positions in pharmaceutical and quality control workflows, and evidence of alignment with validation and compliance expectations. Monitoring capacity expansion, product launches that extend into metal-sensitive or preparative applications, and sustainability-driven certifications can provide early signals of strategic intent. Caution is warranted in segments where price competition is eroding margins without corresponding performance gains.
For procurement and laboratory operations leaders, column selection should be evaluated through the lens of total analytical risk and workflow efficiency. Factors such as reproducibility, service and method support, column lifespan, and compatibility with validated methods can outweigh modest price differences. Building supplier relationships around performance transparency and documented reliability can reduce variability in day-to-day operations and simplify method transfer. As application requirements become more varied, maintaining flexibility in column selection while anchoring decisions in proven performance will help balance throughput goals with analytical integrity.
Sustained advantage in this market depends on staying ahead of technical, regulatory, and operational shifts before they become mainstream purchasing criteria. Detailed segment-level data, company-specific benchmarks, and tailored scenario analysis can help decision-makers translate these trends into precise strategy. Readers seeking a deeper dive into segmentation dynamics, regional demand patterns, and customized strategic recommendations are encouraged to explore the full PW Consulting report for a more comprehensive view of the opportunities and risks shaping the small molecule liquid chromatography columns market.
For detailed analysis of this topic, please visit the official page: Worldwide Small Molecule Liquid Chromatography Columns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


