



Worldwide Bread Production Line Market: How the 5.4% CAGR Signals a Quiet Shift

Strategic Trends and Commercial Opportunities in the Worldwide Bread Production Line Market
Market Overview: State of Play and Core Pressures
A Resilient Market at an Inflection Point
The global bread production line market has demonstrated steady expansion over the past five years, with total revenue climbing from approximately $1.6 billion in 2020 to an estimated $2.1 billion in 2025. The trajectory reflects a compound annual growth rate of 5.4 percent across the historical period, and forward projections suggest the market will surpass $3 billion by 2032. This growth is not merely a function of population increase; it is being driven by capacity upgrades, automation adoption, and shifting production economics across both mature and emerging markets. While the overall market remains broadly distributed among equipment manufacturers, regional food processors, and system integrators, concentration metrics indicate that the top three players command roughly 31 percent of revenue, with the top five capturing closer to 43 percent. This moderate concentration leaves meaningful room for specialized entrants and regional champions, but it also signals that scale, service networks, and technological differentiation are increasingly decisive in securing long-term contracts.
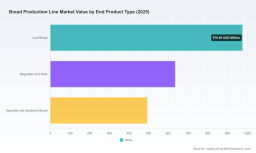
Despite the positive growth outlook, the industry is navigating a set of structural pressures that will define investment decisions over the next several years. The first is the tension between automation ambition and capital efficiency. Fully automatic production lines now account for the majority of equipment value, yet many mid-sized bakeries face constrained capex environments and uncertain demand forecasts. Upgrading to high-throughput, fully automated systems can improve consistency, reduce labor exposure, and increase throughput, but the payback period becomes longer when raw material volatility and energy costs erode margin assumptions. The second challenge is the widening gap between high-volume commodity bread production and the premium, texture-sensitive segment that includes artisan-style, specialty, and sandwich formats. Lines that excel at pan bread throughput may struggle to accommodate highly hydrated doughs or delicate shaping requirements without significant retooling, creating a strategic fork in product portfolio planning. The third challenge is geographic unevenness. Demand growth is not uniform across regions, and the economic case for new capacity depends heavily on local consumption patterns, import substitution dynamics, and the cost of building or retrofitting facilities. Producers expanding into newer markets must contend with differences in labor availability, utility infrastructure, and regulatory expectations around food safety and traceability.
Bakery Machine Market
Why This Moment Matters for Decision Makers
For executives planning capacity investments or evaluating supplier partnerships, the current environment is less about whether the market is growing and more about where value is being created and captured. The operators who will outperform are likely to be those who treat production lines not as static asset purchases but as configurable platforms that can adapt to product mix changes, labor constraints, and input cost variability. The broader trajectory favors automation and standardization, but the commercial winners will be those who align line flexibility with the realities of regional demand, raw material sourcing, and service responsiveness. Understanding these pressures is essential because they influence everything from equipment configuration choices to negotiation leverage with manufacturers and the timing of phased rollouts.
Key Drivers Shaping Market Momentum
Technology Innovation and Line Configurability
Technological progress remains the most visible driver of market evolution, particularly in the integration of dough handling, proofing, forming, and baking into coordinated systems that can be tuned for different product types. Leading manufacturers are increasingly differentiating on precision and adaptability rather than throughput alone. High-precision forming and dough processing equipment reduces waste and improves repeatability, while advanced proofing and tunnel oven systems support more consistent crumb structure and crust development across larger batches. For industrial bakeries, this matters because product consistency is no longer a secondary concern; it is tied directly to brand trust, retail slotting, and the ability to standardize across multiple plants. At the same time, equipment is becoming more configurable, allowing producers to switch between loaf bread, rolls, baguettes, and specialty formats with fewer changeover losses. This flexibility is especially valuable for bakeries that must serve both retail and food service channels or that are expanding across categories without building separate lines for each product type.
Policy, Regulatory, and Food Safety Dynamics
Regulatory expectations continue to influence equipment design and plant architecture. Food safety standards, traceability requirements, and hygiene protocols are pushing manufacturers toward equipment that is easier to clean, inspect, and validate. In many markets, this translates into more enclosed dough handling, improved surface materials, and control systems that log operating parameters for audit readiness. The regulatory environment also interacts with energy and sustainability policies. As utilities and local authorities tighten scrutiny on emissions, heat recovery, and energy intensity, production lines that incorporate more efficient baking systems or better thermal management gain a compliance and cost advantage. Producers evaluating new lines are increasingly weighing not only processing speed but also whether the equipment will support long-term regulatory alignment and reduce the risk of future retrofits. This is particularly relevant in regions where food manufacturing modernization programs are reshaping incentive structures and where larger customers expect suppliers to meet higher operational standards.
Demand-Side Shifts in Bread Consumption and Channel Mix
Consumer and customer behavior is reshaping the product profile that production lines must support. Bread consumption patterns are diversifying, with stronger interest in specialty formats, sandwich-ready products, and region-specific styles that demand more nuanced processing. At the same time, retail and food service buyers are asking for consistent availability, tighter specification control, and greater flexibility in pack sizes and formats. This combination favors lines that can produce multiple end-product types with controlled variation rather than lines optimized for a single high-volume output. Commercial bakeries are also responding to the need for faster responsiveness, especially where demand is fragmented across local preferences or where private-label growth is intensifying specification requirements. In effect, the demand side is rewarding producers who can maintain scale without sacrificing format diversity. That creates a strategic premium for production lines that balance automation with product versatility, especially in markets where bread is both a staple and a format-driven category.
Supply Chain Pressure and Input Cost Volatility
Raw material economics are a persistent source of uncertainty, and recent wheat price movements have underscored the sensitivity of bread production to upstream costs. With wheat prices rising sharply year over year in early 2026 and farm-level price forecasts signaling continued pressure, bakeries and equipment buyers are factoring input volatility more heavily into capacity planning. This environment encourages investment in lines that reduce dough waste, improve yield consistency, and allow better control over formulation changes. It also increases the importance of supplier relationships that can support faster reconfiguration when recipes or ingredient availability shift. For equipment purchasers, the cost backdrop makes it less attractive to over-specify for a single product niche if that choice limits future adaptability. Instead, there is greater interest in systems that can preserve throughput while accommodating changes in dough moisture, ingredient mix, or product dimensions. In a volatile cost environment, flexibility is not just a product feature; it is a margin management tool.
Competitive Landscape and Leading Strategies
How the Incumbents Are Positioning
The competitive field includes established European and North American system builders, precision-focused Asian manufacturers, and a growing set of specialists serving flatbread and regional product categories. AMF Bakery Systems stands out for its emphasis on complete system solutions for high-volume industrial bakeries, positioning itself as a partner for producers that need integrated lines rather than isolated unit equipment. Rademaker has built a strong reputation across the medium-to-large scale segment, with line capacities that span pan breads and highly hydrated artisanal formats, an attractive combination for producers seeking one platform for multiple bread types. Sveba Dahlen, often in cooperation with Glimek, has carved out a niche through advanced dough make-up lines, belt proofers, and tunnel ovens, with an emphasis on tailoring equipment to different bread types and production capacities. Mecatherm differentiates through automated bread production systems aimed at baguette and specialty bread processes, including proprietary offerings such as MECACRUSTY and MECAAUTHENTIK, signaling a strategy centered on format-specific precision. König Maschinen and Baker Perkins continue to play important roles in the industrial equipment space, with Baker Perkins particularly recognized for integrated mixing, dough handling, and baking systems that support complete line design. Rheon Automatic Machinery brings a strong focus on high-precision dough processing, which appeals to buyers where dough consistency and gentle handling are critical.
European Bread Market
Regional Dynamics and Emerging Entrants
The competitive map also reflects meaningful regional divergence. Turkey’s Sarmaşık represents a long-standing equipment manufacturer with a multi-decade track record, while Chinese suppliers such as Mysun and QinLi Machinery have built positions around industrial lines for toast, baguettes, buns, and customized bread formats. Their growth underscores a broader shift in which buyers increasingly evaluate credible alternatives to traditional Western equipment sources, especially when total cost of ownership, lead time, and customization matter as much as premium branding. Farhat Bakery Equipment adds another strategic angle by focusing on automated lines for pita, lavash, naan, and other flatbreads at industrial scale, illustrating how category specialization can become a competitive advantage when regional demand creates repeatable volume. MF Italy rounds out the picture with automatic lines that support variable shapes, weights, and sizes while aligning with Industry 4.0 standards, which is relevant for producers aiming to combine flexibility with data-driven process control.
Strategic Differentiation and Consolidation Signals
Across these players, differentiation is increasingly defined by three dimensions: product adaptability, integration depth, and service responsiveness. The most compelling strategic positions are emerging where manufacturers can prove that a line can handle a broader product envelope without sacrificing throughput or consistency. That requires coordination across forming, proofing, baking, and line control, not just excellence in one unit operation. Integration depth matters because bakeries are less interested in standalone equipment performance in isolation and more interested in how well the entire system reduces downtime, simplifies changeovers, and supports consistent quality. Service responsiveness is also becoming a competitive battleground, as newer automation increases the cost of unplanned stoppages and raises expectations for maintenance planning, remote diagnostics, and spare parts availability. At the same time, the market shows signs of both consolidation and fragmentation. Consolidated players benefit from broader portfolios and stronger global support networks, but fragmentation persists because regional bakeries, local bread traditions, and specialized product categories create demand for tailored solutions. New entrants are most likely to succeed where they bring a clear specialty, a credible cost position, or a differentiated approach to flexibility and automation.
Forward Outlook: Trends to Watch in the Next Three to Five Years
Broader Automation with Format-Level Flexibility
Over the next several years, the most consequential trend will be the continued spread of higher automation levels, but with an important twist: the winning lines will be those that combine scale with format-level flexibility. Purest throughput gains will still matter in high-volume segments, but demand diversification and product proliferation will push producers to invest in lines that can switch between loaves, rolls, baguettes, and specialty products with reduced changeover time and minimal quality drift. The commercial opportunity lies in equipment and service offerings that make flexible automation economically viable for mid-sized processors, not just the largest global bakeries. The risk is that some buyers overextend into automation blueprints that are optimized for narrow product assumptions, leaving them exposed if product mix shifts or if energy and labor costs alter the economics of complex changeovers.
PW Consulting
Cost Resilience Becomes a Core Equipment Selection Criterion
Input cost volatility is likely to remain a defining theme, making yield control, waste reduction, and formulation adaptability more valuable than they were in a lower-inflation environment. Equipment that supports consistent dough processing, tighter tolerance control, and faster response to recipe or ingredient changes will be prioritized because it gives producers more control over margin outcomes. The strategic opportunity for suppliers is to frame line value not only in terms of speed and capacity but also in terms of cost resilience and process stability. The downside risk is that cost pressure may delay capital spending among smaller producers, concentrating new investment among larger players and those with the strongest balance sheets or the most urgent capacity needs.
Regional Capacity Realignment and Category Specialization
A third trend is the ongoing realignment of where new capacity is added and what kinds of production lines are favored in different markets. Some regions will see investment driven by import substitution, local modernization programs, and growing domestic demand for standardized industrial bread. Others will focus on category specialization, particularly where flatbread, artisan-style products, or sandwich formats represent stronger growth than traditional loaf bread. For investors and manufacturers, the opportunity is to match equipment strategies to these divergent paths rather than assume a single global template. The uncertainty lies in the pace of regional execution: supply chain bottlenecks, utility constraints, and shifting regulatory requirements can all delay or reshape planned capacity additions.
Strategic Implications for Decision Makers
For Equipment Manufacturers and Line Integrators
Prioritize demonstrable flexibility and integration depth over headline throughput claims. The buyers who are most likely to commit to larger projects are those who see a clear path to product mix expansion, lower changeover costs, and stronger process control. Service capability, spare parts availability, and uptime support should be treated as core product attributes because they increasingly determine whether a line is viewed as a long-term asset or a risky capital outlay. Manufacturers that can align their offerings with cost resilience, hygiene compliance, and data-enabled process control will be better positioned as procurement teams evaluate total cost of ownership rather than upfront price alone.
For Investors and Strategic Buyers
The market’s moderate concentration and continuing regional fragmentation create opportunities in specialized equipment niches, service-led expansion, and category-focused production solutions. The more durable value is likely to come from businesses that can serve high-growth formats, support flexible automation for mid-market buyers, or provide reliable after-sales performance that reduces operating risk. Before committing capital, it is important to understand which product segments are expanding, which geographies are seeing genuine capacity demand versus speculative investment, and how raw material volatility is affecting buyer confidence. Detailed segment-level intelligence is essential here, because the headline market growth can obscure uneven performance across bread types, automation levels, and regions.
For Commercial Bakeries and Procurement Teams
Treat production line selection as a multi-year operating decision, not a one-time equipment purchase. Evaluate platforms based on how well they support likely future product mixes, how they perform under input cost variability, and whether the supplier can deliver localized service and faster response when disruptions occur. Where capex is constrained, phased upgrades and modular retrofitting may offer a better risk-adjusted path than large-scale replacement projects that assume stable demand and stable input costs. In parallel, procurement teams should pressure-test supplier claims against real changeover scenarios, maintenance obligations, and the operational burden of switching formulations or bread types. For organizations that need a more precise view of segment economics, regional demand patterns, and supplier positioning before finalizing investment plans, the full PW Consulting market research report provides the deeper breakdown and customized context required for high-stakes decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Bread Production Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


