



Worldwide Toluic Acid Market: Asia Pacific $117.79B Leads 4.19% CAGR Shift

Navigating the Worldwide Toluic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Global Market Trajectory and Core Challenges
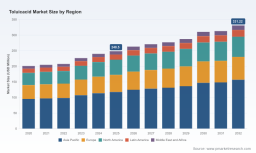
The worldwide toluic acid market has demonstrated steady, measured expansion over the past half-decade, evolving from a niche aromatic intermediate segment into a strategically positioned value chain within specialty chemicals. Starting from approximately USD 201.2 million in 2020, the market has grown to reach USD 248.5 million in 2025, reflecting an incremental yet resilient trajectory. Forward projections indicate continued upward momentum, with the market anticipated to surpass USD 263 million by 2026 and approach USD 331 million by 2032. This expansion translates to a compound annual growth rate of 4.19 percent across the forecast horizon, a figure that underscores moderate but dependable growth rather than speculative volatility. For executives and investors evaluating cyclic commodity exposure versus specialty chemical positioning, this trajectory signals a market characterized by steady demand absorption, moderate pricing power, and relatively predictable capacity utilization patterns.
Such growth characteristics are neither explosive nor stagnant; they reflect an industry operating in a mature but structurally evolving phase. The expansion is underpinned by sustained utilization in downstream manufacturing ecosystems, where toluic acid functions as a critical building block rather than a terminal consumer product. This intermediate positioning means that demand elasticity is closely tied to capital expenditure cycles, formulation shifts, and regulatory timelines in end-use sectors. While the aggregate revenue trajectory appears linear, the underlying dynamics are increasingly shaped by geographic redistribution of production capacity, isomer-specific demand divergence, and shifting cost传递 mechanisms from upstream petrochemical streams.
Three structural challenges currently define the market's inflection point. First, feedstock sensitivity remains a persistent volatility driver. Toluene, the primary oxidation feedstock for toluic acid synthesis, has experienced pronounced regional price fluctuations, with Northeast Asian benchmarks climbing toward USD 1,058 per metric ton FOB in early 2026 and broader global pricing averaging around USD 1.08 per kilogram in the same period. These movements reflect tightening supply conditions and crude-linked cost pressures that compress margins for producers operating without long-term feedstock alignment or integrated supply agreements. Second, regulatory complexity continues to reshape compliance frameworks across major trading jurisdictions. Aromatic monocarboxylic acid derivatives, including toluic acid isomers, navigate evolving chemical safety inventories, substance registration requirements, and tariff classifications that differ significantly between North American, European, and Asian customs regimes. These regulatory layers introduce administrative overhead, testing requirements, and documentation burdens that disproportionately affect mid-tier producers and emerging market exporters. Third, the industry faces a structural transition in capacity geography and competitive positioning. Production concentration has remained relatively fragmented, with no single entity commanding dominant market share, yet capital deployment patterns suggest a gradual shift toward integrated regional hubs that prioritize pharmaceutical-grade intermediate output and specialized purity standards. This dynamic creates both entry barriers for commoditized players and differentiation pathways for manufacturers that can secure certification, quality consistency, and supply reliability at scale.
Critical Drivers Shaping Market Dynamics
The expansion trajectory of the toluic acid market is not the result of isolated demand spikes but rather the convergence of technological, regulatory, demand-side, and supply chain forces that collectively redefine competitive benchmarks. Understanding these drivers provides decision-makers with a clearer view of where margin opportunities, capacity allocation decisions, and partnership strategies will yield the most durable returns.
Muconic Acid Market
Technological innovation in oxidation catalysis and process intensification has emerged as a primary efficiency driver. Traditional toluene oxidation pathways have historically balanced yield optimization against byproduct management, particularly acid recovery and isomer separation. Recent process refinements have focused on catalyst selectivity improvements, temperature control precision, and downstream purification sequences that reduce energy intensity while maintaining high-purity output standards. These advancements are particularly relevant for producers targeting pharmaceutical and fine chemical intermediate markets, where purity thresholds and batch consistency directly influence customer qualification timelines. Companies that invest in continuous processing upgrades, advanced monitoring systems, and closed-loop solvent recovery are better positioned to absorb feedstock cost fluctuations while preserving gross margin stability. The technology dimension also intersects with product differentiation, as enhanced purification capabilities enable producers to serve analytical, laboratory, and specialty-grade segments that command premium pricing relative to bulk industrial grades.
Regulatory and policy environments continue to exert structural influence across multiple dimensions. In the United States, toluic acid isomers are classified under specific harmonized tariff subheadings that shape import logistics, customs clearance timelines, and trade compliance workflows. In parallel, environmental and chemical safety frameworks in Europe require manufacturers and downstream users to adhere to substance registration protocols, safety data documentation, and workplace exposure guidelines. These regulatory layers are not uniformly restrictive; rather, they create compliance asymmetry that rewards organizations with established quality management systems, audit-ready documentation, and proactive regulatory monitoring. For market participants, the operational implication is clear: regulatory readiness has transitioned from a baseline requirement to a competitive differentiator. Firms that integrate compliance infrastructure into their production and export workflows reduce lead-time variability, minimize shipment friction, and strengthen buyer confidence in long-term supply agreements.
Demand-side behavior is undergoing a measurable shift driven by formulation requirements and intermediate utilization patterns. Agrochemical and pharmaceutical intermediate applications represent two of the most significant demand anchors in the market, each with distinct procurement cycles, purity specifications, and qualification processes. Pharmaceutical-grade intermediate consumption is particularly sensitive to manufacturing scale-up decisions, active pharmaceutical ingredient pipeline progression, and contract manufacturing organization sourcing strategies. As drug development and generic formulation activity expand in select regions, demand for consistent, high-purity toluic acid intermediates has become more structured and less susceptible to spot-market volatility. Meanwhile, specialty chemical applications, including pigment and dye synthesis as well as polymer initiator utilization, contribute steady baseline demand while offering flexibility for grade-specific sourcing. The broader implication for procurement and production strategy is that demand is increasingly segmented by quality tier, with premium applications incentivizing supply reliability and traceability over lowest-cost acquisition.
Supply chain restructuring and cost structure evolution represent the fourth critical driver. Regional feedstock pricing divergence has intensified as crude-linked cost movements, transportation constraints, and local supply-demand imbalances create uneven input cost environments. Producers operating in feedstock-advantaged locations or securing fixed-price supply arrangements are gaining relative cost competitiveness, while others are forced to pass through price adjustments or accept margin compression. This dynamic is accelerating a broader reevaluation of sourcing geography, inventory positioning, and long-term contract structures. Buyers are increasingly prioritizing multi-source qualification, regional buffer inventory, and supplier performance metrics that extend beyond price to include delivery reliability, batch consistency, and technical support capability. Simultaneously, capacity expansion decisions are being evaluated against not only capital expenditure but also logistics accessibility, export market proximity, and alignment with downstream customer clusters. A notable example of this strategic realignment occurred in early 2025, when Hanwha Chemical acquired a regional toluic acid production facility to expand capacity and strengthen its supply chain for pharmaceutical-grade intermediates, signaling that inorganic capacity deployment is being used to secure grade-specific output and supply chain resilience rather than merely increase volume.
Competitive Landscape and Strategic Positioning
The competitive architecture of the toluic acid market reflects a diverse participant base spanning regional manufacturers, export-oriented producers, and global specialty chemical suppliers. Market concentration remains moderate, with the top three participants collectively representing just over thirty percent of total revenue and the top five accounting for less than half of overall market value. This fragmentation indicates that no single entity currently exerts overwhelming pricing influence, while simultaneous underscoring that competitive advantage is derived from operational execution, grade specialization, and supply reliability rather than scale alone. The landscape is shaped by producers operating across China, India, Europe, and Japan, each pursuing distinct positioning strategies aligned with regional feedstock conditions, certification portfolios, and end-market focus.
Chinese manufacturers have established a prominent presence in the market by emphasizing production scale, isomer breadth, and cost-efficient intermediate output. Companies such as Evergreensino Chemical and Hefei TNJ Chemical Industry operate with a focus on p-toluic acid, o-toluic acid, and m-toluic acid, catering to industrial and pharmaceutical intermediate applications with an emphasis on bulk availability and consistent purity levels. Their strategic positioning typically leverages regional feedstock access, established export channels, and the ability to supply multiple isomer grades from centralized or coordinated production sites. For downstream buyers, this translates into accessible supply options and competitive pricing, though qualification and quality assurance processes remain essential when sourcing for regulated or high-specification applications.
PW Consulting
Indian producers have carved a differentiated position by emphasizing pharmaceutical and specialty chemical alignment, often supported by GMP frameworks, export-oriented quality controls, and multi-location manufacturing footprints. Kaival Chemicals, Muby Chemicals, Ottokemi, and Triveni Chemicals illustrate this approach, with product portfolios spanning para toluic acid, o-toluic acid, and m-toluic acid across purity grades suited for pharmaceutical, fragrance, laboratory, and industrial applications. Their competitive edge frequently derives from the combination of certification readiness, flexible batch sizing, and the ability to serve both bulk and precision-grade requirements. This positioning resonates with buyers who require validated quality documentation, reliable lead times, and the option to scale volumes as downstream production schedules evolve. The Indian segment's growth within the global market reflects broader trends in specialty chemical manufacturing, where regulatory compliance, export logistics, and technical grade differentiation increasingly determine supplier selection.
Global specialty suppliers, including Merck KGaA through its Sigma-Aldrich portfolio and Tokyo Chemical Industry, occupy a distinct niche focused on high-purity grades, analytical applications, and research-grade supply chains. Their strategic value lies in consistency, documentation rigor, and the ability to serve customers with stringent specification requirements. While these suppliers typically operate at lower volume scales relative to industrial manufacturers, they command pricing premiums and maintain strong customer retention in segments where specification fidelity and supply traceability outweigh cost sensitivity. Their presence in the market reinforces the multi-tier nature of toluic acid demand, where bulk industrial consumption and high-purity specialty usage coexist but follow different procurement logic.
The competitive landscape is evolving along several observable trends. Consolidation activity is emerging selectively, as demonstrated by inorganic capacity acquisitions that target pharmaceutical-grade intermediate supply chain strengthening. Such moves suggest that companies are prioritizing grade-specific capability expansion and regional supply security rather than pursuing undifferentiated volume aggregation. At the same time, market fragmentation persists, allowing nimble regional producers to compete on responsiveness, technical support, and customized grade offerings. New entrants and expanding producers face a higher bar for differentiation, as buyers increasingly evaluate suppliers on quality consistency, compliance readiness, and supply continuity rather than price alone. The resulting environment favors participants that can align production capabilities with clearly defined end-market requirements, maintain transparent documentation practices, and build supplier relationships that extend beyond transactional exchanges.
Forward Outlook: Strategic Trends for the Next Three to Five Years
Looking ahead, the toluic acid market is likely to be shaped by three interrelated trends that will influence sourcing strategies, capacity planning, and competitive differentiation. The first trend is the continued bifurcation of demand by quality tier. As pharmaceutical and specialty chemical applications expand their share of total utilization, procurement behavior will increasingly separate bulk industrial purchases from precision-grade requirements. This divergence will reward producers capable of maintaining dual-track capabilities, where standard industrial grades coexist with validated high-purity output and robust quality documentation. Buyers in regulated segments will place greater value on qualification speed, batch-to-batch consistency, and traceability, while price-sensitive industrial consumers will continue to optimize around feedstock-linked cost movements and regional availability.
The second trend is the ongoing realignment of supply chain geography around cost stability and regulatory alignment. Feedstock pricing volatility, coupled with transport and trade compliance complexity, will encourage longer-term contract structures, regional inventory buffering, and selective nearshoring or friend-shoring of intermediate supply. Capacity investments are likely to remain selective, with capital directed toward facilities that can serve specific grade profiles and downstream customer clusters rather than pursuing generalized volume expansion. This realignment will create opportunities for suppliers that can demonstrate predictable delivery performance and flexible volume scaling, particularly in markets where buyers are reducing single-source dependency.
The third trend involves incremental regulatory and compliance maturation as a competitive filter rather than a barrier. As chemical safety documentation, customs classification accuracy, and substance registration requirements become more embedded in procurement workflows, suppliers with established compliance infrastructure will experience fewer friction points and faster qualification cycles. Organizations that treat regulatory readiness as a strategic capability—integrated into production planning, export documentation, and customer communication—will be better positioned to sustain relationships in regulated downstream markets. The primary risk accompanying these trends is feedstock cost unpredictability, which can disrupt margin assumptions and alter relative competitiveness if not managed through contract design, inventory strategy, or process efficiency improvements. A secondary risk lies in qualification and documentation gaps that can delay supplier adoption, particularly for buyers operating under stringent quality and traceability expectations.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority should be aligning capacity and process investments with grade-specific demand rather than pursuing undifferentiated volume growth. Building capability across multiple purity tiers, strengthening quality documentation systems, and securing feedstock supply arrangements that reduce exposure to spot-market volatility will improve margin resilience and customer retention. Producers that can demonstrate consistent batch performance, transparent compliance practices, and responsive technical support will be better positioned to expand share in pharmaceutical and specialty chemical segments where qualification and reliability carry disproportionate weight.
Malonic Acid Market
For investors evaluating exposure to the toluic acid value chain, the most durable opportunities lie in participants with clear grade differentiation, disciplined capacity deployment, and supply chain positioning that aligns with downstream regulatory and quality requirements. Capital allocation should favor operational models that integrate feedstock risk management, compliance infrastructure, and customer qualification support rather than relying solely on scale-driven cost advantages. Monitoring regional feedstock pricing trends, capacity acquisition activity, and regulatory developments will provide early signals of competitive repositioning and margin trajectory shifts.
For procurement and sourcing leaders, the most effective strategy involves multi-source qualification, grade-specific supplier mapping, and contract structures that balance price competitiveness with delivery reliability and specification consistency. Evaluating suppliers on documentation readiness, batch traceability, and technical responsiveness will reduce qualification friction and improve supply continuity. Building buffer inventory strategies and maintaining alternative sourcing pathways will also help mitigate feedstock-linked price volatility and logistics disruption. For organizations seeking detailed segment data, regional supply analysis, and customized sourcing or investment scenarios, comprehensive market research provides the granular intelligence needed to translate these strategic directions into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Toluicacid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


