



Enzymatic Detergents Market: Why 5.45% CAGR Through 2032 Reflects Structural Shifts

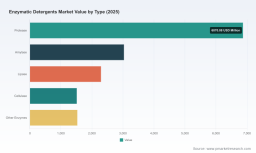
Global Enzymatic Detergents Market: Strategic Shifts and Commercial Opportunities (2026–2032)
Market Snapshot & Core Challenges
The worldwide enzymatic detergents market has demonstrated consistent upward momentum over the past half-decade, expanding from a base of approximately $11.68 billion in 2020 to an estimated $15.24 billion in 2025. This trajectory reflects a compound annual growth rate of 5.45 percent across the historical window, and forward projections indicate the sector will surpass $22.10 billion by 2032. The steady expansion is anchored in a structural pivot away from conventional surfactant-heavy formulations toward enzyme-driven cleaning architectures that deliver higher efficacy at lower temperatures and reduced chemical load. Despite the favorable baseline, the industry is navigating a set of interdependent challenges that will dictate competitive positioning over the next several years.
The first critical inflection point revolves around regulatory tightening and compliance complexity. Environmental frameworks governing detergent ingredients have moved from voluntary sustainability claims to mandatory performance benchmarks. Biodegradability thresholds, restricted substance lists, and updated authorization requirements for specific enzyme categories are no longer peripheral considerations; they are central to product approval cycles, reformulation timelines, and market access. Companies that treat compliance as a retrospective exercise are encountering costly delays, while those that embed regulatory foresight into enzyme selection and formulation design are preserving launch velocity.
A second challenge stems from raw material volatility and cost structure uncertainty. Fermentation-derived enzyme production remains sensitive to agricultural feedstock pricing, energy inputs, and logistics constraints. Recent quarters have illustrated how fluctuations in glucose-derived substrates and upstream capacity bottlenecks can compress margins or trigger price adjustments for key protease variants. This dynamic forces detergent manufacturers and enzyme suppliers to recalibrate procurement strategies, renegotiate contract structures, and evaluate alternative production pathways without compromising activity levels or formulation stability.
Industrial Enzymes Market
The third structural challenge is geographic and supply chain fragmentation. Trade policy shifts have introduced tariff exposure on imported microbial enzymes, disrupting established sourcing patterns and prompting cost reallocation across a meaningful portion of the distribution network. At the same time, regional regulatory divergence means that a formulation optimized in one market may require substantive modification to satisfy conditions elsewhere. The result is a market that rewards agility in sourcing, localized formulation capabilities, and strategic relationships with enzyme developers who can provide regulatory-grade documentation and performance consistency across jurisdictions.
Key Drivers Reshaping the Market
Technological Advancement in Enzyme Performance
Innovation in enzyme engineering continues to be the most direct catalyst for market growth. Next-generation protease and amylase variants are being designed to maintain high catalytic activity under cooler wash conditions, reduce required dosages, and improve compatibility with mixed-fabric care routines. These technical gains translate into tangible value for detergent formulators: lower active loading can reduce formulation cost while preserving or enhancing cleaning outcomes, and cold-water optimization aligns with consumer energy-conservation behaviors. Recent product introductions illustrate this trajectory, with new protease platforms specifically positioned for improved cold-water performance and upgraded amylase options targeting more efficient starch removal in eco-oriented laundry formulations.
Regulatory and Sustainability Mandates
Policy and certification landscapes are accelerating adoption of enzyme-based cleaning systems by setting clear expectations around biodegradability, phosphate-free architectures, and verified environmental claims. Updated regulatory annexes, authorization requirements for specific enzyme substances, and ecolabel recognition pathways are reshaping procurement criteria for both consumer and institutional buyers. In practice, this means enzyme suppliers that provide compliant, well-documented ingredient portfolios gain preferential access to formulators seeking to meet market entry requirements without compromising performance. Certification achievements for enzyme lines used in sustainable detergent applications have become meaningful differentiators because they reduce uncertainty in the validation process and strengthen claims credibility.
Demand-Side Behavior and Application Expansion
Consumer and commercial buyer preferences are shifting along two reinforcing axes: performance expectation and environmental accountability. Household laundry remains the dominant application driver, supported by demand for detergents that deliver stain removal and fabric care while operating effectively at lower temperatures. Beyond consumer channels, institutional, healthcare, and dishwashing applications are expanding as end-users search for cleaning protocols that balance hygiene standards, material compatibility, and reduced chemical exposure. This broadening demand base creates cross-segment opportunities for enzyme developers who can tailor activity profiles, stability characteristics, and dosage efficiency to distinct use cases rather than relying on a single generic formulation logic.
PW Consulting
Supply Chain Configuration and Cost Realities
The cost and availability of enzyme inputs are increasingly shaped by feedstock economics, regional manufacturing footprints, and trade policy exposure. As fermentation feedstock costs fluctuate and tariff structures alter the competitiveness of cross-border enzyme flows, detergent producers are re-evaluating supplier diversity, inventory planning, and regional production partnerships. This environment elevates the strategic importance of enzyme portfolios that offer consistent quality, predictable supply continuity, and the flexibility to support multiple formulation platforms. Companies that can combine technical performance with supply resilience are better positioned to manage cost volatility without sacrificing formulation integrity.
Laundry Detergent Market
Competitive Landscape and Leading Strategies
The market displays a moderately concentrated structure, with a limited number of globally active enzyme specialists accounting for a substantial share of supply. Competition is less about volume alone and more about technical differentiation, regulatory readiness, and application-specific formulation support. Leading players have built advantage through distinct strategic postures that align with the broader market drivers described above.
- Novozymes A/S has maintained a leadership position by emphasizing enzyme platforms optimized for cold-water cleaning and household detergent efficacy. Its recent launch of a next-generation protease targeting enhanced cold-water performance underscores a strategy centered on activity improvement under conditions that matter most to end-users and formulators alike.
- DuPont de Nemours, Inc., through its Genencor division, has focused on industrial-grade enzyme systems for laundry and automatic dishwashing applications. The introduction of an improved amylase variant aimed at stronger starch removal in eco-friendly detergent contexts signals continued investment in application-specific performance upgrades rather than broad product proliferation.
- DSM Nutritional Products has leaned into bio-based stain removal and fabric care solutions, using certification milestones to reinforce credibility in sustainable detergent applications. Achieving recognized ecolabel status for an enzyme line used in this segment illustrates a strategy that combines technical supply with compliance and claims support.
- AB Enzymes GmbH has positioned its enzyme portfolio around whiteness and color care outcomes, targeting detergent manufacturers seeking differentiated fabric benefits. This approach highlights how enzyme suppliers can compete by solving specific formulation goals rather than competing solely on price.
- Amano Enzyme Inc. has emphasized alkaline stability and global household cleaner compatibility, an important consideration for manufacturers operating across varied wash conditions and regional formulation norms.
- BASF SE has connected enzyme offerings to phosphate-free and sustainable laundry solutions, using established chemical-brand architecture to support broader environmental positioning within detergent systems.
The competitive evolution appears to be moving along two parallel tracks. Consolidation remains relevant among suppliers seeking to widen enzyme portfolios, strengthen regional regulatory support, and secure feedstock and manufacturing flexibility. At the same time, differentiation is intensifying through application-specific engineering, performance claims validation, and sustainability documentation. New entrants and smaller specialists can still gain traction by targeting niche formulation needs, offering superior cold-water activity, or providing enzyme systems that simplify compliance for detergent manufacturers navigating multiple regulatory regimes. The practical implication is that competitive advantage will increasingly depend on whether a supplier can deliver a credible blend of performance, documentation, supply continuity, and application coverage.
Forward Outlook: Trends Shaping 2026–2032
Over the next three to five years, the enzymatic detergents market is likely to be shaped by a combination of performance-driven formulation change, regulatory maturity, and supply chain recalibration. Three trends stand out as particularly consequential for commercial strategy.
- Cold-water and low-energy cleaning will remain a central product development priority. Enzyme variants that sustain high activity at lower temperatures will continue to be favored because they align with consumer energy habits, fabric-care expectations, and sustainability messaging. Formulators that secure reliable access to such enzymes will have an advantage in product positioning and reformulation speed.
- Regulatory and certification frameworks will harden into default procurement requirements. As updated biodegradability expectations, authorization lists, and ecolabel criteria become more established, enzyme selection will be influenced as much by compliance readiness as by technical performance. Suppliers that provide clear documentation and tested compliance pathways will reduce friction for detergent manufacturers and institutional buyers.
- Sourcing resilience will become a competitive requirement rather than a backup plan. With feedstock cost movement and trade policy exposure affecting portions of the enzyme supply chain, detergent producers and enzyme buyers will place greater weight on supplier diversification, regional manufacturing options, and contractual stability. Cost management will increasingly depend on predictability and qualification of alternative supply sources, not only on unit pricing.
These trends translate into clear commercial opportunities. Enzyme developers that can pair performance gains with regulatory documentation, regional supply flexibility, and application-specific formulation support will be well placed to capture share in both consumer and institutional channels. At the same time, uncertainty remains. Feedstock price swings may continue to pressure margins, regulatory lists may expand or shift in ways that require reformulation lead time, and tariff or trade disruptions can alter sourcing economics with limited warning. Companies that treat these variables as integral to planning rather than exceptional events will be better equipped to convert market growth into durable profitability.
Actionable Priorities for Decision-Makers
For detergent manufacturers and formulators, the immediate priority is to align enzyme selection with both performance targets and compliance readiness. Evaluating protease, amylase, lipase, and cellulase options against cold-water activity, dosage efficiency, alkaline stability, and regulatory documentation will reduce reformulation risk and support faster response to certification requirements. Building a broader qualified supplier base can also mitigate exposure to feedstock-driven cost volatility and regional sourcing disruptions.
For investors, the most relevant question is whether enzyme suppliers and detergent brands have scalable strategies for performance differentiation and regulatory navigation. Commercial value will likely concentrate among players that can demonstrate consistent supply continuity, application-specific product upgrades, and credible sustainability credentials rather than those relying on commodity positioning alone. Monitoring certification progress, product launch cadence, and sourcing flexibility offers a practical lens for assessing which organizations are positioned to convert market growth into durable margins.
For procurement and sourcing leaders, diversification and qualification should be treated as strategic levers. Expanding the approved enzyme supplier list, securing regional supply options where feasible, and embedding compliance documentation into vendor evaluation can reduce disruption risk while preserving formulation quality. In a market where trade policy and feedstock economics can shift cost structures quickly, resilience in sourcing decisions is as important as price negotiation.
Detailed segmentation data, regional revenue breakdowns, company-level profiling, and scenario modeling are essential for translating these strategic themes into execution plans. More granular intelligence on type and application splits, regional dynamics, competitive benchmarks, and supplier-level developments can be reviewed in the full PW Consulting market analysis, where the underlying figures and supporting context are laid out for practical planning use.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymatic Detergents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


