



Worldwide Industrial Kneader Market: What the 5.12% CAGR Shift Really Means

Global Industrial Kneader Market: Navigating Strategic Shifts and Emerging Opportunities Through 2032
The Worldwide Industrial Kneader Market has demonstrated steady expansion, with overall market size reaching approximately $1,280.5 million in 2025. From a base of $985.4 million in 2020, the sector has followed a consistent upward trajectory, reflecting the essential role of high-viscosity mixing equipment across diversified manufacturing ecosystems. Current projections indicate the market will advance at a compound annual growth rate of 5.12 percent through 2032, ultimately approaching $1,816.35 million. This growth pathway is neither linear nor automatic. It reflects converging pressures across technology, regulation, supply chain economics, and end-use demand that are actively reshaping procurement strategies, product roadmaps, and competitive positioning.
At present, the industry operates at a structural inflection point. First, raw material cost volatility has become a persistent margin constraint. U.S. hot rolled coil steel reached $1,002 per ton in early 2026, while Chinese benchmark steel prices climbed to 3,152 CNY per ton on April 29, 2026, marking a 3.28 percent year-over-year increase. Since kneader manufacturing relies heavily on structural steel, hardened alloys, and precision machining components, these input shifts directly pressure equipment pricing, lead times, and builder margins. Second, trade policy friction has reshaped cost architectures. The U.S. Section 232 steel tariffs increased to 50 percent effective June 2025, with certain exceptions remaining at 25 percent. This development imposes new cost layers on machinery manufacturers incorporating imported steel components or sourcing from affected jurisdictions, forcing rapid reevaluation of sourcing networks and pricing models. Third, demand composition is shifting. Historically anchored in rubber and plastics compounding, the market now faces a more fragmented application landscape where performance specifications, materials compatibility, and regulatory compliance vary significantly across sectors. These overlapping dynamics mean that static capacity expansion or generic equipment offerings no longer guarantee sustained relevance.
Market Structure and Concentration Dynamics
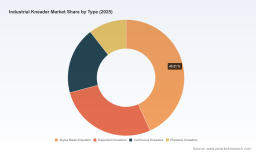
The competitive environment reflects moderate concentration, with the top three participants collectively accounting for approximately 18.45 percent of total revenue and the top five reaching 27.8 percent. This distribution signals a market where scale advantages exist but do not dominate. Regional demand is geographically dispersed, with Asia Pacific representing the largest share of activity at $515.56 million, followed by Europe at $319.86 million, North America at $278.83 million, Latin America at $103.9 million, and Mideast and Africa at $62.35 million. Application demand spans multiple end-use industries, with rubber and plastics processing at $426.24 million, chemicals and synthetics at $353.93 million, food and confectionery at $256.18 million, battery materials at $155.96 million, and pharmaceuticals and cosmetics at $88.19 million. By equipment type, sigma blade kneaders lead at $553.29 million, dispersion kneaders at $354.08 million, continuous kneaders at $238.23 million, and planetary kneaders at $134.9 million. While these figures outline the current allocation of activity, the real strategic question is how these splits will migrate as application requirements, capacity utilization, and regional manufacturing footprints evolve.
Industrial Mixer Market
Key Drivers Reshaping the Industrial Kneader Landscape
The trajectory of the industrial kneader market is no longer dictated by a single catalyst. Instead, four interlocking drivers are redefining equipment requirements, competitive advantage, and investment priorities. Understanding how these forces interact provides a clearer view of where durable growth will emerge and where legacy assumptions will fail.
Technological Innovation and Performance Differentation
Equipment performance is shifting from volume throughput toward precision, repeatability, and material adaptability. High-viscosity compounding demands tighter temperature control, reduced shear degradation, and consistent batch-to-batch uniformity. This has accelerated development of advanced cooling systems, intermesh rotor configurations, and continuous processing architectures that reduce downtime and improve energy efficiency. Recent industry activity reflects this shift. OTT RubberTech released a 2026 guide identifying top kneader mixer factories worldwide, explicitly noting that EV battery manufacturing is driving new kneader demand segments for electrode paste and high-viscosity compound processing. This signals that performance differentiation is expanding beyond traditional rubber and plastics applications into materials where particle dispersion, homogeneity, and contamination control carry direct downstream consequences. Manufacturers that can demonstrate validated processing outcomes, not just machine specifications, are gaining procurement preference in technically demanding segments.
Industrial Agitators Market
Regulatory and Trade Policy Pressures
Policy dynamics are reshaping cost structures and supply chain design. The increase in U.S. Section 232 steel tariffs to 50 percent effective June 2025, with certain exceptions remaining at 25 percent, has introduced new cost uncertainty for machinery builders relying on imported steel components. Combined with upward movement in global benchmark steel prices, this environment compels manufacturers to evaluate localized sourcing, alternative material grades, and pricing flexibility. At the same time, regulatory scrutiny across food, pharmaceutical, and cosmetics applications is raising the bar for surface finish, cleaning protocols, and material certification. Equipment that cannot meet documentation, compliance, or validation requirements faces extended sales cycles or exclusion from qualified vendor lists. The regulatory layer thus operates as both a cost pressure and a qualification filter, rewarding manufacturers with established quality systems and traceable component sourcing.
PW Consulting
Demand-Side Evolution and Application Diversification
End-use demand is broadening in both scale and technical complexity. Battery materials processing is emerging as a distinct demand pocket, driven by electrode slurry mixing, high-viscosity compound handling, and specialized formulation requirements. Simultaneously, chemicals and synthetics applications continue to seek continuous and semi-continuous kneading solutions that support higher throughput and reduced batch variability. Food and confectionery processors prioritize hygiene, easy cleaning, and material compatibility, while pharmaceutical and cosmetics manufacturers emphasize contamination control and validated processing environments. This diversification means that equipment suppliers must navigate overlapping but distinct specification sets. Procurement teams are increasingly evaluating total cost of ownership, maintenance accessibility, and integration with existing line architecture rather than relying solely on upfront equipment price. The shift favors suppliers that can map application requirements to equipment configuration with clear operational and compliance rationale.
Supply Chain and Cost Structure Reconfiguration
Input cost volatility is compelling a broader rethinking of manufacturing and delivery models. Steel price movements, combined with tariff impacts, are pressuring builders to optimize component design, standardize platforms, and selectively localize sourcing where possible. At the same time, logistics complexity and lead-time variability are influencing customer expectations around delivery reliability and aftermarket support. Suppliers that can offer modular configurations, predictable lead times, and transparent cost structures are gaining advantage in procurement negotiations. The broader implication is that cost competitiveness is increasingly defined by design efficiency, sourcing agility, and service integration rather than by labor arbitrage alone. Recent industry participation at events such as the Tire Technology Expo, where Wuxi Double Elephant Rubber & Plastics Machinery Co., Ltd. exhibited kneader products, and cooperation outreach by TF Kneader during the 2026 Spring Canton Fair, reflects ongoing efforts to align product offerings with regional demand and supply chain realities.
Competitive Landscape and Strategic Positioning
The industrial kneader market features a diverse set of established and regional participants, each pursuing distinct positioning strategies. The moderate concentration level indicates that no single player controls the market, but differentiation in technology, application focus, and service capability is increasingly decisive.
Profile of Key Participants and Strategic Orientation
Kneader Machinery Co., Ltd., based in Taiwan, has specialized since 1981 in dispersion kneaders, including standard, heavy duty, super cooling, and intermesh models tailored for rubber and plastics processing. Its long operating history and model variety position it around application-specific dispersion requirements. Farrel Pomini, operating across the USA and UK, offers internal and continuous mixers for tire, technical rubber, and high-viscosity compounding applications with capacities from 10 to 600 L, emphasizing scale flexibility and compounding precision. HF Mixing Group, headquartered in Germany, provides advanced mixing solutions including Banbury mixers and kneaders for the rubber processing industry, focusing on materials spanning high to low viscosity ranges, which aligns with performance-driven compounding markets. Kobelco, based in Japan, manufactures internal kneaders and mixing equipment for rubber and elastomer processing with emphasis on precision and durability, appealing to customers prioritizing equipment longevity and consistent mechanical performance.
Buss AG, headquartered in Switzerland, specializes in kneader technology for high-viscosity compounding in plastics, rubber, and chemical applications, targeting technically demanding processes where dispersion quality and process control are critical. Charles Ross & Son Company, based in the USA, produces kneader extruders, tilt kneaders, and sigma blade mixers for chemicals, pharmaceuticals, plastics, adhesives, and food products using German AMK technology, reflecting a cross-application portfolio supported by established engineering heritage. B&P Littleford, also USA-based, designs continuous kneaders and mixers for plastics mixing, carbon paste, and high-viscosity compounding in rubber and plastics industries, aligning with throughput and continuity requirements. Winkworth Machinery, operating in the UK since 1924, manufactures Z blade sigma kneader mixers and stainless steel industrial mixers for doughs, pastes, and high-viscosity materials, with a focus on food-grade and hygienic processing environments. Lleal, based in Spain, offers industrial kneaders for automating and optimizing kneading processes across chemical, pharmaceutical, and food sectors, emphasizing process automation and consistency. Well Shyang Machinery Co., Ltd., located in Taiwan, produces various types of kneader mixers, extruders, and pellet making machines for rubber and plastics applications, combining mixing and downstream processing capabilities. INOUE MFG., INC., based in Japan, manufactures kneading machines supporting various industries with over 100 years of experience in mixing equipment, leveraging long-standing process knowledge. PerMix, operating across USA and China, supplies sigma kneader-mixers with Z arm configuration for high-viscosity mixing in pharmaceutical, food, chemical, and other industries since 1954, positioning around cross-sector versatility and established mixer design.
Differentiation Levers and Competitive Evolution
Across this participant set, differentiation is increasingly defined by application alignment, materials expertise, and service integration rather than by equipment presence alone. Leading positions tend to emerge where suppliers can demonstrate repeatable outcomes for specific viscosity ranges, temperature profiles, and material sensitivities. Continuous and semi-continuous architectures are gaining strategic relevance as processors seek reduced batch variability and higher throughput consistency, while dispersion and sigma blade configurations remain essential where batch flexibility and wide material compatibility are required. The market is simultaneously experiencing consolidation pressure among regional players seeking broader application coverage and new entry activity from manufacturers responding to specialized demand pockets such as battery materials and high-purity processing. Recent external developments illustrate this dynamic: OTT RubberTech’s 2026 guide highlighted EV battery manufacturing as a new demand driver, while trade show participation and factory visit programs by companies such as Wuxi Double Elephant and TF Kneader reflect active efforts to expand commercial reach and technical engagement. The net effect is a landscape where technological credibility, sourcing resilience, and application-specific validation are becoming the primary filters for procurement decisions.
Forward Trends and Strategic Implications Through 2032
Looking ahead three to five years, the industrial kneader market will likely be shaped by three interconnected trends. First, demand will continue migrating toward application-specific and higher-compliance configurations. Battery materials, pharmaceutical, and food-grade processing environments are expanding specification requirements around material compatibility, cleaning validation, and process repeatability. Equipment that can meet these requirements with documented performance will capture premium positioning, while generic offerings may face margin compression. Second, continuous and semi-continuous processing is expected to gain broader adoption where throughput stability, energy efficiency, and labor optimization are prioritized. This shift will not replace batch architectures entirely but will reshape the mix of equipment types deployed across high-utilization production environments. Third, cost and sourcing resilience will remain central to competitiveness. Steel price volatility and tariff-driven cost changes will continue influencing design efficiency, platform standardization, and regional sourcing strategies. Suppliers that can balance performance, delivery predictability, and transparent cost structures will be better positioned to sustain margin health.
These trends create clear commercial opportunities for manufacturers that invest in application validation, modular design, and service integration, as well as for procurement leaders that prioritize total cost of ownership and compliance readiness. However, uncertainty remains. Demand pace in battery materials could shift with broader EV market dynamics and manufacturing scale-up patterns. Trade policy adjustments may alter cost structures further, creating winners and losers across sourcing networks. Input cost volatility and logistics variability could pressure lead times and pricing flexibility. Market participants will need to monitor these variables closely and maintain configuration agility rather than committing exclusively to narrow product assumptions.
Actionable Implications for Decision-Makers
The current trajectory suggests that strategic advantage will come from readiness, not reaction. For equipment manufacturers, the priority is to strengthen application-specific validation, optimize platform commonality to manage input cost variability, and align sourcing networks with tariff and steel price realities. Investing in continuous or semi-continuous capabilities and high-compliance configurations can open access to faster-growing, higher-specification demand pockets while reducing exposure to commoditized competition. For investors and strategic planners, the focus should be on distinguishing durable application-driven growth from cyclical capacity expansion. Segments tied to battery materials, high-viscosity chemical compounding, and hygiene-sensitive food and pharmaceutical processing warrant closer evaluation for their specification intensity and potential margin resilience, while exposure to input cost volatility and trade policy shifts should be modeled explicitly in scenario planning.
For procurement and operations leaders, the more effective evaluation framework moves beyond upfront price toward total cost of ownership, maintenance accessibility, compliance documentation, and integration compatibility. Equipment selection should weigh validated processing outcomes, cleaning and material compatibility requirements, and service responsiveness alongside throughput expectations. In an environment where raw material costs and trade conditions remain dynamic, procurement strategies that build in configuration flexibility, service coverage, and transparent cost structures are better equipped to manage uncertainty. For organizations seeking deeper segmentation data, regional procurement patterns, and tailored scenario analysis, the complete research report offers expanded detail on equipment type trajectories, application-specific growth pathways, and company-level positioning insights to support more precise strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Kneader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


