



Worldwide Vanadium Slag Market: Why 7.52% CAGR Redefines Steel & Energy Storage

Strategic Trends and Commercial Opportunities in the Global Vanadium Slag Market
Market Landscape and Core Challenges
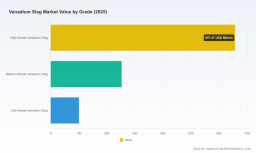
The worldwide vanadium slag market has demonstrated consistent expansion over the past half-decade, with revenue scaling from approximately $684 million in 2020 to over $1,011 million in 2025. This trajectory reflects a compound annual growth rate of roughly 7.5 percent across the period, positioning the segment at approximately $1,030 million in the current base year and projecting further growth toward $1,681 million by 2032. The market's expansion is fundamentally anchored in its role as the dominant feedstock for global vanadium production, accounting for more than seventy percent of supply. Co-production models in major steelmaking hubs, particularly those processing vanadium-bearing titanomagnetite ores, have continuously augmented feedstock availability. As downstream demand diversifies beyond traditional metallurgy, the slag segment has gained renewed strategic importance, functioning both as a cost-efficient raw material pipeline and as a byproduct stream increasingly subject to targeted recovery and value-addition initiatives.
Despite the favorable growth momentum, the industry operates at a critical inflection point shaped by several structural challenges. The first revolves around feedstock concentration and geographic dependency. A disproportionate share of vanadium slag generation is tied to titanomagnetite processing in specific metallurgical corridors, making supply vulnerable to localized policy shifts, environmental restrictions, or operational disruptions at integrated steel plants. The second challenge stems from evolving regulatory frameworks that are actively reshaping material flows. Import restrictions enacted in major producing jurisdictions have redirected domestic processing toward locally generated slag, compelling producers to optimize domestic recovery infrastructure rather than relying on cross-border feedstock arbitrage. The third challenge involves cost and efficiency pressures. Traditional slag recovery routes face margin compression as energy costs fluctuate, processing complexity rises with lower-grade residues, and environmental compliance requirements tighten. Producers that fail to upgrade separation technologies, integrate circular recovery systems, or secure reliable downstream offtake agreements risk being squeezed between volatile primary vanadium pricing and increasingly stringent operational standards.
These challenges are not purely headwinds; they are actively restructuring how value is captured across the value chain. Companies that treat slag as a low-priority byproduct are finding their cost structures and supply reliability tested, while those that integrate advanced recovery, secure offtake channels, and align processing capabilities with end-market specifications are converting a traditional waste stream into a strategically positioned revenue line. The market's next phase will likely reward operators that can navigate regulatory divergence, optimize material recovery, and synchronize production planning with downstream demand cycles.
Key Drivers Shaping Market Dynamics
Technological innovation in slag processing has become a decisive competitive lever. Advanced physical separation, hydrometallurgical leaching, and integrated zero-waste system trials have materially improved recovery efficiency while reducing tailings volume. Industry pilots have demonstrated recovery rate improvements of approximately eighteen percent when modernized separation sequences are applied to vanadium-bearing residues, directly lowering unit processing costs and expanding the economically viable portion of lower-grade streams. These technical gains are shifting the economics of slag utilization, enabling producers to profitably extract value from materials that previously carried high disposal burdens. The trend is especially relevant given that vanadium pentoxide pricing in recent periods has reflected supply dynamics rooted in slag-derived recovery, making process efficiency a direct determinant of margin resilience.
Vanadium Redox Battery (VRB) Market
Policy and regulatory divergence is simultaneously reshaping feedstock routing and investment priorities. Import restrictions on vanadium slag in major producing markets have accelerated the localization of processing capacity, forcing domestic steel and vanadium operators to treat slag recovery as an in-house strategic priority rather than a tradable commodity play. At the same time, tariff adjustments on related vanadium products and by-product materials into key consuming markets have altered cross-border flow patterns, nudging producers to reconsider destination markets, offtake structuring, and regional processing footprints. These regulatory shifts are not static; they create both constraints and opportunities for operators that can align their material flows with evolving compliance requirements while maintaining supply flexibility for downstream customers.
Demand-side behavior is expanding beyond traditional steel and alloy applications. While metallurgical consumption remains the dominant demand pool, energy storage systems and chemical catalyst production are increasingly drawing on vanadium derivatives that trace back to high-efficiency slag recovery. The broadening application base introduces new specification requirements, delivery reliability expectations, and quality consistency demands that directly influence how slag is processed, refined, and commercialized. Buyers in storage and catalyst segments are progressively prioritizing supply continuity and traceability, which incentivizes producers to invest in controlled recovery pathways and cleaner output streams rather than relying on ad hoc residual collection.
Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market
Cost structure evolution is reinforcing the strategic value of integrated sourcing. Because vanadium slag is largely a co-product of steelmaking operations using titanomagnetite ores, its economics are interlocked with steel production cycles, ore grade variability, and downstream ferrovanadium or chemical conversion capacity. Producers that can synchronize slag handling with steel mill throughput, optimize residue blending, and secure downstream conversion capacity are able to buffer against raw material price volatility more effectively than standalone processors. Recent operational disclosures illustrate this dynamic: producers continue to report V2O5 equivalent outputs tied to ore and residue handling, while offtake arrangements increasingly cover high-grade slag streams linked to dedicated processing facilities. Such structures reduce market risk for both sellers and buyers, stabilizing cash flows and enabling more deliberate capacity expansion decisions.
Taken together, these drivers point to a market where value creation is shifting from volume alone toward processing sophistication, regulatory alignment, and demand diversification. Operators that invest in recovery efficiency, align with localized feedstock policies, and build credible bridges to emerging application segments are positioned to capture a larger share of the value embedded in each tonne of slag.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by concentrated leadership alongside a broad base of region-specific producers, with the top three players accounting for roughly fifty-eight percent of market share and the top five approaching seventy-two percent. This concentration reflects the capital intensity of integrated slag processing, the importance of securing reliable titanomagnetite-linked feedstock, and the advantage of coordinating steelmaking operations with vanadium recovery. At the same time, the market is not monolithic; geographic positioning, processing philosophy, and downstream integration strategies create meaningful differentiation among leading operators.
Leading Chinese producers, including major groups operating in vanadium-titanium magnetite regions, derive strategic advantage from large-scale co-production within established steel complexes. Their differentiation lies in feedstock availability, integrated operations, and the capacity to treat slag recovery as a routine part of the production cycle rather than a separate commercial venture. This model supports consistent supply volumes and provides a natural hedge against slag market volatility, since slag generation is tied to ongoing steel output. Some of these operators are also advancing zero-waste system approaches, improving recovery rates while reducing environmental liabilities, which strengthens their positioning with regulators and downstream customers seeking more sustainable sourcing options.
PW Consulting
Outside China, significant producers rely on integrated mining, processing, and downstream ferrovanadium or chemical conversion capabilities. A prominent Russian steel and ferrovanadium operator illustrates the value of linking ore processing with vanadium product conversion, enabling more direct control over grade consistency and downstream specification alignment. In the Americas, specialized processors have carved out positions by focusing on residues, ashes, and slag streams for ferrovanadium and high-purity chemical production, with particular strength in spent catalyst recycling that yields vanadium products and reduces dependence on primary ore-linked slag alone. This recycling-linked model provides a differentiated feedstock base and can offer greater flexibility when titanomagnetite-derived slag flows shift.
Canadian-aligned operations with Brazilian processing assets emphasize primary vanadium production from dedicated mining assets, while also managing associated slag and by-product streams. Their strategic emphasis has been on stabilizing primary output, optimizing residue handling, and exploring expanded opportunities linked to slag-derived material flows. Recent production reports highlight consistent V2O5 equivalent output and continued attention to ilmenite and associated residue streams, signaling that even primary producers see slag and byproduct management as integral to overall asset efficiency. South African producers tied to Bushveld Complex operations and Central European manufacturers generating aluminothermic slag alongside ferrovanadium further illustrate the diversity of feedstock routes and processing philosophies across the market.
Recent commercial activity underscores how the landscape is evolving. Offtake term sheets covering one hundred percent of high-grade vanadium-bearing slag from proposed processing plants illustrate a move toward tightly structured supply agreements that reduce uncertainty for both producers and downstream converters. Such arrangements are especially relevant for new or expanded facilities that need committed demand to justify capital deployment. Alongside these offtake developments, ongoing production disclosures from integrated operators show that consistent output and disciplined byproduct handling remain central to maintaining competitive positioning. The trend suggests a market in which secure supply relationships, grade assurance, and processing reliability are becoming as important as raw volume.
Market structure appears to be moving through both consolidation and fragmentation pressures simultaneously. Concentration at the top reflects scale advantages in integrated steel-linked slag generation and downstream conversion, which favors larger operators that can absorb regulatory complexity, maintain processing technology upgrades, and serve demanding downstream specifications. At the same time, fragmentation persists through specialized recyclers, regional processors, and new project developers targeting particular slag grades or geographic markets. New entrants are most likely to succeed where they can offer differentiated feedstock access, advanced recovery performance, or credible offtake partnerships rather than competing purely on commodity volume.
Future Trends and Commercial Opportunities
Over the next three to five years, the vanadium slag market is likely to be shaped by three interconnected trends, each carrying clear commercial implications. The first is the continued localization of processing capacity in response to import restrictions and shifting tariff dynamics. As more jurisdictions prioritize domestic slag recovery, investment will increasingly flow toward upgraded separation lines, cleaner output streams, and integrated waste-reduction systems. Commercial opportunities will arise for technology providers, engineering partners, and operators capable of deploying modular or scalable recovery solutions that improve recovery rates while meeting local compliance requirements.
The second trend is demand diversification into energy storage and catalyst segments, which will place greater emphasis on product consistency, traceability, and specification control. While steel and alloy production will remain the largest demand base, the growth of vanadium-linked storage applications creates incremental pull for high-quality derivatives that originate from well-managed slag streams. This opens opportunities for processors that can guarantee grade stability, maintain reliable delivery schedules, and align recovery outputs with downstream refining needs. Suppliers that position themselves as consistent sources for both metallurgical and non-metallurgical channels can broaden their revenue base and reduce exposure to any single demand cycle.
The third trend is the growing strategic importance of offtake-linked project structuring and integrated supply planning. As high-grade slag streams become more closely tied to dedicated processing facilities and contracted downstream conversion, the market will reward operators that can combine production reliability with commercial certainty. This creates opportunities for partnerships that link slag producers, converters, and end users in coordinated supply frameworks, reducing price and volume uncertainty while enabling more disciplined capacity investments. At the same time, potential risks remain: regulatory changes can redirect flows suddenly, tariff adjustments can alter destination economics, and technology adoption may be uneven across regions. Feedstock variability from titanomagnetite operations and energy cost volatility can also challenge margin stability, making operational flexibility and scenario planning essential.
Actionable Insights for Decision-Makers
For manufacturers and processors, the priority is to treat slag recovery as a strategic capability rather than a residual cost center. Investing in separation efficiency, recovering more value from lower-grade streams, and building reliable offtake agreements can improve margin resilience and supply security. Aligning processing upgrades with evolving regulatory expectations also reduces compliance risk while strengthening positioning with customers that increasingly value sustainable sourcing.
For investors, the most compelling opportunities lie in businesses that combine feedstock access, processing differentiation, and credible downstream linkages. Capital deployment should favor operators with clear recovery technology roadmaps, integrated conversion pathways, or structured offtake coverage, since these attributes provide greater visibility into revenue stability and scale potential. Project-stage initiatives should be evaluated not just on resource potential but on the quality of commercial anchoring and the ability to navigate regional regulatory shifts.
For procurement and supply chain leaders, securing multi-source access and prioritizing suppliers with consistent grade performance will become increasingly important as demand diversifies and regulatory divergence affects material flows. Long-term agreements, specification alignment, and transparency around recovery and processing practices can mitigate supply disruption risk while supporting broader sustainability objectives.
Given the pace of regulatory change, evolving demand patterns, and shifting competitive dynamics, detailed segment-level intelligence remains essential for precise planning. A comprehensive research report can provide deeper breakdowns of regional dynamics, grade-specific supply behavior, application-side demand signals, and tailored scenario analysis to support more confident strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Slag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


