



Roasted Pyrite Market 2026: Why 3.86% CAGR and Asia Pacific Growth Signal Repricing

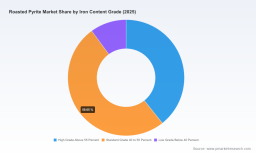
Roasted Pyrite Market: Strategic Trends and Commercial Opportunities (2025–2032)
The roasted pyrite market has entered a phase of measured expansion, shaped by steady demand from heavy industry and evolving processing standards. Over the past five years, the sector has grown from a base of roughly 402 million USD in 2020 to an estimated 486 million USD in 2025. Looking ahead, the market is projected to reach approximately 633 million USD by 2032, translating to a compound annual growth rate of 3.86 percent across the forecast window. This trajectory reflects a maturing commodity market where volume growth is increasingly tied to efficiency gains, regulatory compliance, and shifting end-use priorities rather than raw demand expansion alone.
For decision-makers evaluating exposure to roasted pyrite, the headline numbers mask a more nuanced reality. Growth is neither uniform nor automatic. The market is navigating a series of structural pressures that will determine which participants capture value and which face margin compression. Understanding these pressures is essential for shaping procurement strategies, capital allocation, and long-term positioning.
Sulphur Bentonite Market
Current Market Profile
The market's footprint is heavily concentrated in a few key application streams, with steel and iron production accounting for the largest share of consumed roasted pyrite, followed by cement manufacturing, paint and pigments, and glass and ceramics. This distribution underscores the material's role as both a chemical input and a functional additive across foundational industrial sectors. Regionally, Asia Pacific dominates consumption, reflecting the scale of metallurgical and cement operations in the area, while Europe, North America, the Middle East and Africa, and Latin America collectively represent more diversified but smaller demand pools. The market structure remains moderately consolidated, with the top three participants holding roughly 42.5 percent of overall share and the top five accounting for 58.3 percent. Such concentration suggests that scale, processing capability, and supply reliability continue to differentiate leading suppliers from smaller or more regionally focused players.
Core Challenges and Inflection Points
Despite the outward growth trajectory, the industry faces several interlocking challenges that will define competitiveness over the next cycle.
Sulphur Recovery Market
- Cost volatility and margin sensitivity. Raw material pricing for pyrite and related sulfur-bearing minerals has shown notable swings, with export benchmarks for roasted iron pyrites from key origins rising sharply in periods of tight supply. For downstream buyers, particularly in sulfur-dependent processes, these fluctuations translate directly into cost unpredictability and pressure on procurement planning.
- Quality standardization and impurity management. As end-use applications demand more consistent performance, the tolerance for variable iron content and residual sulfur has narrowed. Lower-grade material remains commercially relevant in certain segments, but high-purity requirements in specialized applications are pushing producers and buyers alike toward tighter specification control and more advanced beneficiation.
- Regulatory and environmental scrutiny. Roasting processes inherently involve emissions control, heat recovery, and residue management. Continued operational legitimacy depends on demonstrable efficiency in sulfur capture, energy recovery, and cinder utilization. Facilities that cannot meet evolving expectations around residual sulfur levels and process cleanliness face both compliance risk and reputational exposure.
These challenges are not merely operational inconveniences; they are reshaping the logic of market participation. Companies that treat roasted pyrite as a commoditized bulk input may find themselves exposed to price swings and specification gaps, while those that align sourcing and processing with quality, compliance, and reliability are better positioned to secure long-term contracts and steadier margins.
Key Drivers Shaping the Roasted Pyrite Market
The market's trajectory is being pulled forward by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, creating a environment where efficiency, consistency, and supply security carry disproportionate strategic weight.
Technology Innovation and Processing Breakthroughs
Advances in roasting technology are transforming how pyrite is converted into usable industrial materials. Fluid bed roasters capable of high throughput have become a reference point for producers seeking to balance capacity with heat recovery and sulfur capture. Alongside these established systems, flash roasting approaches are drawing attention for their ability to reduce residual sulfur in cinder to very low levels, supporting cleaner downstream acid production and more versatile cinder utilization. Such improvements matter because they directly affect both economics and environmental performance. Lower residual sulfur means less reprocessing, higher product acceptability, and reduced waste handling costs. For buyers, access to roasted pyrite produced through advanced methods can translate into more predictable yields and fewer processing interruptions.
At the product level, recent launches of higher-purity roasted pyrite concentrates illustrate how processing refinements are opening new application pathways. By lowering impurity levels and improving processing efficiency, these grades enable sulfuric acid producers and other users to operate with greater consistency and less downtime. The broader implication is that technology is not only expanding what can be produced but also raising the performance bar that market participants must meet to remain competitive.
Policy and Regulatory Environment
Regulatory dynamics continue to shape the operating context for roasted pyrite. Environmental expectations around emissions, energy recovery, and residue management are becoming more entrenched rather than receding. This is particularly relevant for sulfuric acid-related applications, where roasting remains a niche but active pathway supported by heat recovery systems and low-residual-sulfur cinder outputs. In practical terms, regulatory pressure is acting as both a constraint and a filter: it raises the cost of noncompliant operations while rewarding producers who can demonstrate credible efficiency and environmental controls.
Trade and export patterns also reflect the influence of policy and market structure. Leading export flows of roasted iron pyrites have come from a relatively concentrated set of origins, indicating that trade access, shipping logistics, and origin-specific quality reputations play a meaningful role in how supply reaches end markets. For importers and downstream manufacturers, this means supply diversification strategies must account not only for price but also for origin reliability, quality consistency, and the regulatory posture of source regions.
Demand-Side Shifts in End-Use Industries
Demand for roasted pyrite is closely tied to the operating rhythms of steel, cement, and specialty chemical sectors. In steel and iron production, the material's role as a sulfur and iron source keeps it embedded in core metallurgical workflows. Cement manufacturing represents another significant demand pillar, where pyrite derivatives contribute to process chemistry and product characteristics. Meanwhile, more specialized applications in paints, pigments, glass, and ceramics provide additional demand threads, often with higher specification requirements.
What is changing on the demand side is not necessarily the volume of material consumed in every segment, but the emphasis on quality and predictability. As industrial operators face tighter operating margins and more complex compliance obligations, they increasingly prefer supplied materials that reduce variability in downstream processing. This shift favors suppliers that can offer consistent grades, transparent quality data, and reliable delivery rather than those competing solely on lowest headline price. It also encourages end users to lock in longer-term arrangements with trusted sources, particularly where feedstock security is linked to production continuity.
Supply Chain and Cost Structure Dynamics
The cost structure of roasted pyrite is influenced by a chain of factors that extend from mining and beneficiation through roasting, logistics, and export. Recent periods have shown how quickly raw material economics can shift, with sulfur and pyrite input costs feeding into higher acid price levels in major consumer regions. In one major Asian market, average prices for concentrated sulfuric acid reached elevated levels during the year, reflecting both input cost pressure and regional supply dynamics. Such movements highlight how sensitive downstream industries are to upstream cost changes and why procurement teams monitor pyrite pricing trends as part of broader input cost management.
Supply chain resilience is becoming a strategic priority in its own right. Major restructuring activity, including acquisitions designed to secure roasted pyrite feedstock and expand downstream roasting capacity, signals that market participants are treating feedstock access as a critical asset. Partnerships focused on co-developing roasting capacity and sulfuric acid production further illustrate the trend toward integrated arrangements that reduce exposure to spot-market volatility. At the same time, new plant startups processing pyrite by-products from mining operations demonstrate how feedstock availability can be reshaped by broader mining and metals activity, creating both opportunities and dependencies for roasted pyrite supply.
Competitive Landscape and Leading Strategies
The competitive environment in the roasted pyrite market is defined by a mix of established multinational players, specialized industrial mineral suppliers, and regionally concentrated producers. Rather than competing purely on volume, leading companies are increasingly differentiating through processing capability, application know-how, and supply reliability.
Strategic Positioning of Key Players
Several companies illustrate distinct competitive approaches within the market.
- Equipment and process technology providers. Metso has built a reputation around pyrite roasting plant technology, with offerings that span sulfuric acid production, heat recovery, and metals recovery from roasted material. Its emphasis on high-capacity fluid bed roasters points to a strategy centered on enabling producers to scale efficiently while capturing energy and sulfur value. In a market where processing quality and recovery efficiency are increasingly important, technology-enabled positioning can create stickiness with customers seeking to upgrade or expand capacity.
- Industrial mineral processors and distributors. Washington Mills and Hickman, Williams & Company represent players with strong ties to industrial applications such as abrasives, metallurgy, foundry, and chemical sectors. Their relevance lies in the ability to position roasted pyrite within broader material supply chains, linking product quality to end-use performance. By serving multiple industrial segments, these companies can balance demand variability across applications and maintain relevance even when one sector softens.
- Regional producers with integrated reach. Veneta Mineraria and Chinese manufacturers such as Foshan Pyrite Mineral Materials, Tongling Weight Mineral Products, and UrbanMines reflect the importance of regional production bases with varying degrees of processing depth. UrbanMines, for example, emphasizes high-purity pyrite products delivered in roasted or calcined forms for applications including resulfurization, abrasives, and wastewater treatment. Such positioning shows how product specification and application breadth can serve as differentiation tools in a market where grade consistency and purity are increasingly valued.
Market Consolidation and Evolving Dynamics
The market's moderate concentration suggests room for both consolidation and specialization. Recent corporate activity underscores this direction. A major acquisition valued at approximately 320 million USD brought together a large group and a minerals entity to secure roasted pyrite feedstock and expand downstream roasting capacity. This type of move signals a strategic intent to control more of the value chain, reduce feedstock uncertainty, and strengthen supply credibility with downstream customers.
Partnerships are also reshaping competitive dynamics. A strategic cooperation between a leading tin company and a regional engineering partner to co-develop roasted pyrite roasting capacity and sulfuric acid production highlights how feedstock, processing, and acid output can be aligned to create mutually reinforcing assets. Similarly, the startup of a new pyrite-based plant in Indonesia, processing pyrite ore from a copper mining by-product stream to produce substantial volumes of sulfuric acid, illustrates how by-product utilization can unlock new supply and add scale to the broader ecosystem.
Taken together, these developments point to a market where competitive advantage is increasingly tied to integration, feedstock security, and process quality. New entrants and expanding regional producers can still find space, particularly where they bring specialized grades, reliable logistics, or cost-effective processing. However, long-term positioning will likely favor organizations that can combine supply reliability with verifiable quality and applicable technical support.
Forward Outlook: Trends for the Next Three to Five Years
Based on current market structure and recent developments, several trends are likely to shape the roasted pyrite market through the early part of the next decade.
Trend 1: Purity and Specification Upgrading as a Competitive Baseline
As downstream users seek to reduce variability and improve process efficiency, higher-purity roasted pyrite grades are expected to gain incremental importance, especially in applications where impurity control affects yield, emissions, or product quality. This does not mean lower-grade material will disappear; it will continue to serve cost-sensitive segments. However, the strategic center of gravity is shifting toward grades that offer predictable performance and lower residual sulfur. Companies that can reliably supply such grades, supported by consistent processing and testing, are well placed to capture premium positioning and longer-term contracts.
PW Consulting Chemical & Energy Research Center
Trend 2: Feedstock Security Driving Integration and Partnerships
The combination of raw material cost volatility and the strategic importance of continuous downstream operations is likely to sustain interest in feedstock security. Acquisitions, partnerships, and by-product utilization projects are natural responses to this pressure. Over the next several years, more market participants may pursue integrated arrangements that link sourcing, roasting capacity, and downstream output such as sulfuric acid or specialty iron-rich intermediates. For buyers, this trend could improve supply reliability in some channels while also concentrating supply access among better-integrated players.
Trend 3: Environmental Efficiency as a Commercial Requirement
Roasting technologies that improve heat recovery, reduce residual sulfur, and support cleaner cinder utilization are likely to become more central to commercial discourse. Environmental performance is increasingly intertwined with operational economics, since efficient sulfur capture and energy recovery can lower effective processing costs and improve product acceptability. Firms that invest in demonstrable efficiency gains will be better positioned to meet regulatory expectations and customer preferences, while those that lag may face both cost and market access disadvantages.
Risks and Uncertainties
These trends are not guaranteed paths. Raw material price swings can disrupt procurement plans and compress margins, particularly for buyers with limited flexibility. Regulatory shifts in key regions could alter the cost of compliance or change the attractiveness of certain roasting pathways. Demand conditions in steel, cement, and chemical sectors can also shift with macroeconomic cycles, construction activity, and metals markets. In addition, trade dynamics and export concentration mean that supply disruptions in a few origins can have outsized effects on certain import markets. Anticipating these risks requires active monitoring rather than static assumptions.
Strategic Implications and Actions for Decision-Makers
For executives, planners, and investors weighing exposure to roasted pyrite, the market's evolution suggests several practical priorities.
For Manufacturers and Industrial Buyers
Prioritize specification consistency and supply reliability over short-term price minimization. Where possible, align procurement with suppliers that can demonstrate controlled processing, clear quality parameters, and reliable delivery. Consider longer-term arrangements with credible sources to reduce exposure to spot volatility, especially if roasted pyrite is a critical input to continuous processes. Evaluate how advances in roasting technology and higher-purity grades could improve your own downstream efficiency, and factor those benefits into sourcing decisions.
For Investors and Capital Allocators
Focus on value chain positioning and feedstock security. Companies that combine reliable sourcing with scalable, efficient roasting capacity and clear downstream offtake pathways are more likely to sustain value through cycles. Pay attention to integration signals, such as acquisitions and partnerships that strengthen feedstock control or expand acid and specialty product output. Also assess regional exposure carefully, since demand concentration and export patterns can influence both growth potential and vulnerability to trade or regulatory changes.
For Procurement and Strategy Teams
Build a more dynamic view of the supply base. Track not only pricing but also origin reliability, quality trends, technology upgrades, and corporate activity that may reshape supply access. Develop contingency options for feedstock disruption, including alternative origins and specification adjustments where feasible. In a market where moderate consolidation and integrated moves are becoming more common, early awareness of structural changes can improve negotiating position and reduce surprise.
The roasted pyrite market is moving toward a landscape where quality, efficiency, and supply security matter as much as volume. For organizations that need a sharper view of segment-level dynamics, regional supply patterns, pricing context, and company-specific positioning, the full research report provides deeper segmentation data and tailored analysis to support more precise planning and timing decisions.
For detailed analysis of this topic, please visit the official page: Roasted Pyrite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


