



Worldwide Vibrating Wire Weir Monitor Market: 6.12% CAGR Signals 2032 Buy

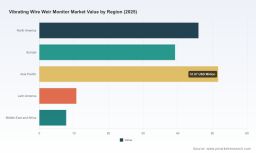
Strategic Trends and Commercial Opportunities in the Global Vibrating Wire Weir Monitor Market
Market Overview and Core Challenges
The global vibrating wire weir monitor market has demonstrated consistent growth over the past five years, with total revenue expanding from approximately USD 115.42 million in 2020 to an estimated USD 155.4 million in 2025. This trajectory reflects a compound annual growth rate of 6.12 percent through the forecast period extending to 2032, when market size is projected to reach USD 235.52 million. The measured expansion is not merely a function of incremental demand but rather a structural shift driven by aging infrastructure, heightened regulatory scrutiny, and the broader transition toward automated, data-rich monitoring systems in water management and geotechnical applications.
Despite the upward momentum, the sector operates under several persistent constraints that shape commercial strategy and investment timing. First, the market remains moderately concentrated, with the top three players accounting for roughly 38 percent of total revenue and the top five capturing just over half. This concentration indicates established competitive moats around technical validation, long-term deployment records, and relationships with dam safety and mining operators, but it also leaves room for specialized entrants who can differentiate on application-specific engineering or regional service capability. Second, the product landscape is dominated by a handful of standardized configurations, with V-notch designs representing the largest share of type-specific demand, followed by rectangular and trapezoidal variants. While this maturity reduces integration risk for end users, it also compresses differentiation opportunities for generic offerings and pushes competition toward ancillary services such as calibration, data integration, and lifecycle maintenance. Third, procurement cycles in core application areas—dam and reservoir monitoring, mining operations, landfill and industrial site management, and broader water resource programs—tend to be long, specification-driven, and heavily influenced by institutional procurement rules and engineering consultants. These dynamics create entry barriers but also reward suppliers who can align product capabilities with recognized standards and demonstrate measurable operational value over multi-year deployments.
Together, these conditions define a market that is growing steadily but rewards disciplined positioning, technical credibility, and close alignment with end-user operational priorities rather than broad-based price competition.
Key Demand Drivers and Structural Shifts
Several interconnected forces are shaping the next phase of market development, and each carries distinct implications for manufacturers, investors, and procurement teams.
Technology performance and signal integrity. Vibrating wire sensing architecture continues to anchor the segment because it offers stable, low-drift measurements over long cable runs and in environments where temperature variation, electrical noise, or remote placement would degrade alternative sensor types. Technical documentation from leading suppliers underscores that these monitors can detect small changes in water level with high resolution while maintaining long-term stability, a combination that is especially valuable in seepage monitoring and dam safety programs where data continuity is critical. The practical consequence is that engineering teams increasingly view vibrating wire weir monitors not as isolated instruments but as integral components of automated monitoring chains, where reliable signal quality reduces false alarms, lowers inspection overhead, and supports more confident decision-making.
Vibration Monitoring Equipment Market
Regulatory and standardization pressure. Dam safety instrumentation expectations in major markets emphasize durability, reliability, and compatibility with long-term automated systems, and vibrating wire sensors are frequently referenced in that context because of their performance profile in weir and piezometer applications. At the same time, V-notch weir configurations used for flow measurement in safety-critical programs are commonly specified with reference to established standards for accurate open-channel and reservoir seepage monitoring. These expectations do not merely create compliance requirements; they influence specification language, procurement preferences, and the pace at which operators replace legacy instrumentation. Suppliers that can map their product documentation, calibration practices, and installation support to recognized standards are better positioned to participate in institutional tenders and multi-year monitoring programs.
Application expansion beyond traditional hydrology. While dam and reservoir monitoring remains the largest demand pool, mining operations and landfill or industrial site management represent substantial and growing usage areas. In mining, water level and seepage monitoring intersects with operational safety, closure planning, and environmental compliance, which encourages operators to standardize on instrumentation that can be deployed across multiple sites and integrated into centralized data workflows. In landfill and industrial contexts, monitoring needs are often tied to containment integrity and regulatory reporting, where robust hardware and predictable maintenance cycles matter more than marginal cost differences. This broadening application base diversifies revenue exposure and gives suppliers additional pathways to scale without relying solely on large dam and reservoir programs.
PW Consulting
Materials, integration, and total cost of ownership. The core hardware typically relies on high-grade stainless steel for the force transducer, cylindrical weight, and housing components to maintain corrosion resistance and long-term stability in submerged or wet environments. That material emphasis is not cosmetic; it directly affects service life, calibration intervals, and replacement frequency, which in turn shape total cost of ownership for operators managing remote or hard-to-access installations. At the same time, the growing availability of automation interfaces and data acquisition options is shifting purchasing criteria from unit price toward integration capability, remote readability, and support responsiveness. In practice, this means competitive advantage increasingly depends on how well a monitor can be installed, maintained, and incorporated into existing telemetry or asset management environments, rather than on sensor performance alone.
Competitive Positioning and Landscape Evolution
The market is defined by a small group of established manufacturers that compete on technical reputation, application-specific refinement, and long deployment pedigrees. Several patterns distinguish the leading positions.
Precision, stability, and specification alignment. Companies such as GEOKON, based in Lebanon, New Hampshire, have built their positioning around precision water level monitoring systems that use vibrating wire force transducers with cylindrical weights tailored for weirs, tanks, streams, and reservoirs. The commercial strength of this approach lies in the combination of high resolution, stable long-term performance, and clearly documented measurement ranges, which helps engineering teams specify equipment with confidence in safety-critical environments. In the United Kingdom, Geosense has emphasized its VWM-2000 design as part of dam safety programs, using a vented vibrating wire force transducer and cylindrical weight to support accurate monitoring in weirs, streams, reservoirs, and tanks. That program-oriented framing reflects a broader competitive trend: suppliers are not only selling sensors, but also positioning them as components of institutional safety and compliance workflows. Soil Instruments has taken a somewhat different angle with its V-notch weir monitor, emphasizing robust, low-cost water level monitoring with cylindrical weight suspension from a force transducer and support for automation through data acquisition. This configuration appeals where durable performance and straightforward integration are prioritized over premium feature sets.
Regional specialization and application tailoring. In Australia, both HMA Group and Geomotion have focused on vibrating wire weir monitoring for geotechnical and open-channel applications. HMA Group supplies monitors commonly installed in V-notch weirs using vibrating wire force transducers for highly stable and sensitive water level monitoring in geotechnical settings, while Geomotion offers systems that combine stainless steel V-notch weir plates with vibrating wire water level sensors for precise seepage flow measurement in dams, rivers, streams, and open channels, including automation options. This regional concentration matters because local experience with site conditions, installation practices, and client expectations can become a durable advantage in markets where field reliability and after-sales support weigh heavily in purchasing decisions.
Worldwide Surface Water Measuring Instrument Market
Consolidation pressure and differentiation pathways. Because the top five participants already account for a majority of revenue, future consolidation is likely to come less from dramatic share grabs and more from targeted acquisitions, distribution partnerships, or capability expansion into adjacent monitoring segments such as piezometers, tiltmeters, or automated data platforms. At the same time, the market is not closed to new entrants who can bring genuine differentiation. Potential entry points include application-specific designs for harsh or specialized environments, stronger native integration with remote telemetry and analytics, improved calibration and service models that reduce lifecycle cost, and regional service networks that shorten response times for remote installations. Conversely, suppliers that compete primarily on price without clear evidence of performance, durability, or integration benefits face increasing pressure, especially as end users become more sophisticated about total cost of ownership and long-term data reliability.
The landscape is therefore evolving toward a dual structure: entrenched incumbents competing on proven stability, standards alignment, and institutional trust, alongside specialized players seeking advantage through integration, service, and tailored engineering.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the market’s direction and shape commercial opportunity.
Automation and remote data integration will become default expectations rather than optional upgrades. As dam safety programs, mining operations, and industrial site monitoring increasingly rely on centralized data workflows, weir monitors that can connect cleanly to acquisition systems and support remote reading will gain preference. The commercial implication is that hardware alone will be less differentiated; suppliers will need to demonstrate installation simplicity, signal compatibility, and support for ongoing data management.
Demand will continue to broaden across application verticals, with mining and containment monitoring gaining relative importance. Even though dam and reservoir programs remain the largest single demand pool, growth in mining and landfill or industrial site use cases adds diversification and creates opportunities for suppliers that can adapt configurations to different site constraints and reporting requirements. This spread also reduces dependence on any single procurement pipeline, which can soften cyclical risk for manufacturers with balanced portfolios.
Standards-aligned specification language will increasingly gate market access. Where procurement teams and engineering consultants reference recognized standards for flow measurement and instrumentation durability, products that can clearly document conformance and long-term performance will enjoy an advantage in bidding and specification processes. Over time, this favors suppliers that invest in documentation, testing, and service transparency, and it raises the stakes for newcomers who must prove credibility quickly.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of steady market growth, expanding application use, and rising expectations for automation creates space for companies that can deliver reliable hardware with strong integration and service support. On the risk side, long procurement cycles, concentrated incumbency, and sensitivity to material and installation costs mean that entry timing, regional coverage, and lifecycle economics matter as much as product performance. Macroeconomic pressure on infrastructure spending, changes in dam safety funding, or shifts in mining capital expenditure could slow demand in specific regions or segments, even as the broader trajectory remains positive.
Strategic Implications for Decision Makers
For manufacturers, the priority is to reinforce differentiation beyond base sensor performance. That means investing in automation-friendly interfaces, clear standards-aligned documentation, and service models that reduce total cost of ownership over the installation life. Suppliers that can show measurable reliability in remote or corrosive environments, and that can support calibration and data integration without heavy customization, are better positioned to defend margin and win specification-driven bids.
For investors, the most relevant signal is that moderate concentration and steady growth do not automatically translate into easy expansion. Value creation is likely to come from targeted capability builds—regional service strength, integration with monitoring platforms, or product extensions into adjacent geotechnical instrumentation—rather than from undifferentiated scale alone. Due diligence should focus on deployment track records, specification win rates, and the extent to which a company’s offering is tied to long-term institutional programs versus shorter, price-sensitive purchases.
For procurement and engineering teams, the practical lesson is to evaluate weir monitors as part of a longer lifecycle equation. Signal stability, compatibility with existing data acquisition, corrosion-resistant construction, and supplier support responsiveness should carry as much weight as initial purchase price, especially in remote or safety-critical deployments where downtime and re-installation costs can quickly outweigh hardware savings.
Detailed segmentation data, company-level positioning, and application-specific demand profiles can sharpen these decisions further. The full PW Consulting market study provides deeper breakdowns and customized strategic guidance for organizations that need to translate these macro trends into operational choices.
For detailed analysis of this topic, please visit the official page: Worldwide Vibrating Wire Weir Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


