



Concentrated Tomatoes Market: Why 5.6% CAGR and 34% Europe Share Redefine 2032 Growth

Strategic Trends and Commercial Opportunities in the Worldwide Concentrated Tomatoes Market
Market Overview: Scale, Trajectory, and Critical Inflection Points
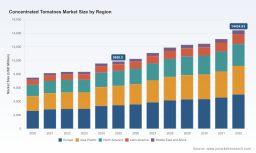
The global concentrated tomatoes market has established itself as a foundational pillar of modern food processing and retail supply chains, driven by the dual demands of convenience, shelf stability, and consistent flavor delivery. With a revenue trajectory that reflects steady expansion through the early 2020s and into the mid-2020s, the sector demonstrates resilience amid shifting agricultural conditions and evolving industrial procurement patterns. The market crossed the nine-billion-dollar threshold in the base year and is projected to maintain a compound annual growth rate of 5.6 percent through the early 2030s, signaling a broadening of application channels, sustained industrial demand, and gradual geographic diversification. This growth trajectory suggests that concentrated tomato products are transitioning from commodity-style bulk inputs toward strategically positioned ingredients where quality, traceability, and processing consistency increasingly dictate purchasing decisions.
Beneath the headline expansion, the industry is navigating several structural inflection points that will redefine competitive positioning over the next five years. Climate volatility has begun to exert measurable pressure on processing-grade tomato yields and harvest windows, particularly in traditional production zones where water availability and temperature extremes are constraining grower output. At the same time, the cost structure of raw material procurement remains a central pressure point for processors seeking to stabilize margins without compromising product specifications. These agricultural and cost variables are intersecting with a broader operational shift: manufacturers are re-evaluating sourcing dependencies, inventory models, and ingredient-formulation strategies to safeguard volume consistency while responding to tighter commercial timelines from food-service and industrial buyers. The confluence of supply-side uncertainty and demand-side expectation escalation means that the market is no longer driven purely by volume expansion, but increasingly by reliability, quality differentiation, and compliance readiness.
Another defining feature of the current landscape is the growing complexity of regional trade dynamics and sourcing arithmetic. Trade measures, tariff structures, and compliance requirements have introduced new considerations for buyers evaluating cross-border supply, while producers juggle capacity allocation decisions between domestic industrial channels and export markets. This environment favors suppliers that can demonstrate transparent sourcing documentation, consistent batch profiles, and operational flexibility. The market is also witnessing a subtle re-rating of ingredient specifications: as food manufacturers seek to streamline formulations and reduce supply-chain variability, concentrated tomato products are being positioned not merely as cost-effective bulk inputs, but as stabilized ingredient platforms that can support cleaner labels, reduced processing steps, and more predictable flavor profiles. These intersecting pressures mark a transition period where operational efficiency, sourcing resilience, and specification leadership will increasingly determine which participants capture disproportionate value as the market advances toward the end of the decade.
Coffee Concentrates Market
Key Drivers Reshaping Market Dynamics
Technological innovation continues to serve as a powerful lever for competitive differentiation across the concentrated tomatoes sector. Processing operations are increasingly integrating precision sorting, controlled concentration techniques, and aseptic preservation technologies that improve consistency while reducing dependency on extensive post-processing intervention. Beyond equipment-level upgrades, there is growing adoption of digital agronomy and supply-chain visibility tools that enable producers to align crop intake with factory throughput, improve yield utilization, and minimize variability between harvest batches. These enhancements are especially valuable for manufacturers supplying industrial food processors, where specification stability and repeatable viscosity, color, and flavor profiles directly influence downstream production efficiency. Innovation is also extending into product design: concentrated derivatives with tailored solids content, reduced sodium intensity, and cleaner processing footprints are gaining relevance as formulators search for ingredient systems that can simplify label declarations while preserving organoleptic performance.
The regulatory environment is simultaneously reshaping sourcing strategies, documentation requirements, and trade flows. Compliance expectations are intensifying around supply-chain traceability and environmental due diligence, with obligations such as the EU Deforestation Regulation requiring structured oversight of agricultural supply chains beginning in late 2025. For concentrated tomato suppliers, this translates into a need to strengthen provenance data, map supplier networks more systematically, and prepare documentation that can withstand scrutiny across multiple jurisdictions. Regulatory initiatives are not confined to environmental compliance. Food safety oversight remains a persistent operational priority, as allergen control, contamination prevention, and recall readiness continue to influence procurement standards across food service, retail, and industrial channels. In practice, regulatory pressure is accelerating a shift toward suppliers that can provide verifiable sourcing narratives and consistent quality assurance systems, because non-compliance risks increasingly carry commercial consequences beyond the immediate cost of a disruption.
On the demand side, purchasing behavior is being reshaped by both end-consumer expectations and corporate procurement priorities. Food manufacturers and food-service operators are prioritizing consistency, convenience, and formulation flexibility, which sustains demand for concentrated formats that deliver reliable performance with fewer processing steps. At the same time, premiumization is gaining traction among retailers and consumer-facing brands seeking differentiation through regional origin, varietal character, and processing intensity. This dual trajectory creates a market where volume-driven industrial applications coexist with specification-sensitive premium demand, each rewarding different sourcing and production models. The household and retail channel, while smaller in scale than industrial processing, is becoming an important arena for brand-led positioning, where packaging, origin storytelling, and perceived quality can justify differentiated price points and support repeat purchase behavior. These demand-side shifts encourage suppliers to think beyond bulk volume and invest in ingredient-grade positioning, batch traceability, and application-specific product design.
Supply-chain and cost structure dynamics complete the picture by reinforcing the importance of sourcing resilience and capacity strategy. Raw material pricing for processing tomatoes has reflected the realities of regional growing conditions, labor availability, and seasonal output variability, making procurement planning more complex for processors that rely on concentrated supply. In major producing regions, total crush volumes and grower pricing trends serve as leading indicators of how tightly supply will match industrial requirements in a given season. At the same time, cross-border trade measures, including antidumping duties affecting select origins, have altered the cost competitiveness of certain import pathways and encouraged buyers to diversify sourcing footprints or renegotiate allocation structures. These dynamics increase the value of suppliers that can offer dependable volume commitments, flexible contract terms, and transparent pricing logic. Where producers can combine agronomic planning, logistical reliability, and processing adaptability, they are better positioned to sustain margin stability even as input-cost volatility and trade friction persist.
Competitive Landscape and Leading Strategies
The competitive structure of the concentrated tomatoes market is defined by a mix of large-scale processors, premium-positioned producers, and regionally focused exporters, each pursuing distinct strategies to protect relevance in a market that rewards both scale efficiency and specification clarity. Leading participants are generally competing on three fronts: supply reliability, product-grade differentiation, and geographic reach. Companies with substantial processing capacity and established relationships with industrial buyers tend to emphasize volume consistency, contract stability, and the ability to serve high-volume food-processing requirements with predictable specification profiles. At the same time, other strong players differentiate through varietal selection, regional sourcing narratives, and premium presentation, positioning concentrated tomato products as ingredients that contribute not only functional performance but also brand value for end users seeking quality and origin authenticity.
Strategic positioning varies significantly by operational model. Large independent producers focused on processing tomatoes typically build advantage through integrated handling of crop intake, concentration efficiency, and logistics coordination, allowing them to serve broad industrial demand while managing seasonal supply fluctuations. Their differentiation often rests on scale, factory throughput, and the ability to offer multiple concentrate grades suited to industrial formulation needs. By contrast, producers associated with premium Italian tomato traditions emphasize varietal character, controlled processing methods, and origin-linked quality narratives. These companies often target retail, food service, and premium industrial applications where label distinctiveness and taste consistency support higher-value positioning. Cooperative structures and regional manufacturers also play an important role by combining local grower relationships with export capability, enabling them to connect regional production bases with international demand while maintaining closer oversight of raw material sourcing.
The market landscape is gradually evolving through a combination of consolidation pressure and segmentation intensification. On one side, scale advantages remain meaningful for participants handling large volumes, meeting industrial service requirements, and absorbing the fixed costs associated with compliance documentation, quality assurance, and supply-chain traceability. On the other side, segmentation is becoming more pronounced, with increasing separation between industrial commodity-style procurement and specification-sensitive premium demand. This divergence encourages some suppliers to specialize, either by reinforcing their industrial supply credentials or by investing in premium-grade product development and brand-facing positioning. New and expanding entrants are also reshaping regional supply patterns, particularly where domestic production growth or export-oriented capacity creation enables alternative sourcing routes. At the same time, trade measures and tariff structures introduce friction that can limit certain cross-border flows and reinforce regional sourcing preferences in specific markets, indirectly supporting suppliers with local or tariff-advantaged supply positions.
Recent operational and market signals further illustrate the emphasis on resilience and compliance readiness across the competitive field. As sourcing documentation expectations rise and trade pathways are reshaped by tariff and regulatory conditions, competitive advantage increasingly depends on the ability to demonstrate transparent supply chains, maintain consistent processing quality, and adapt capacity allocation across domestic and export channels. Suppliers that can combine operational discipline with product differentiation are better positioned to navigate both cost pressure and specification expectations. Over time, the market appears headed toward a structure in which scale, compliance maturity, and grade-specific value proposition will collectively determine competitive strength rather than volume leadership alone.
Future Outlook: Three Trends That Will Shape the Next Phase
Looking ahead to the next three to five years, one central trend will be the continued alignment of concentrated tomato supply with traceability and compliance expectations. As due-diligence requirements expand and food safety standards continue to influence procurement decisions, suppliers that invest early in documentation systems, supplier mapping, and quality verification will gain a structural advantage in buyer selection. This shift will likely elevate the importance of transparency as a commercial asset, making provenance and process discipline part of the value proposition rather than a back-office function. For buyers, this trend means that sourcing decisions will increasingly weigh compliance readiness alongside price and volume reliability.
Worldwide Citrus Concentrate Market
A second trend will be the growing differentiation between industrial-grade volume channels and premium specification channels. Industrial food processing will remain a major demand base, but the premium end of the market is expected to strengthen as brands and food service operators seek ingredient positioning that supports cleaner labels, origin storytelling, and taste consistency. This divergence will reward producers capable of operating both ends effectively, or those that commit strategically to one lane with clear product architecture. Opportunities will emerge for suppliers that can offer application-tailored concentrate profiles, adaptable solids levels, and consistent sensory performance, especially where food manufacturers want to reduce processing complexity without sacrificing quality.
A third trend will be the reconfiguration of sourcing geography and supply-chain buffers in response to climate variability, trade measures, and cost volatility. Buyers are likely to place greater emphasis on multi-origin sourcing, contractual flexibility, and visibility into seasonal supply status. Suppliers with strong agronomic planning, diversified intake channels, and responsive logistics will be better equipped to secure dependable volume allocation. The main risk in this environment is that climate-driven yield variability, combined with trade friction in specific corridors, could create periods of tight supply or uneven pricing. Participants that treat sourcing resilience as a strategic capability rather than a procurement tactic will be better positioned to manage those disruptions while preserving commercial relationships.
Actionable Insights for Decision Makers
For manufacturers and processors, the most immediate priority is to align product architecture with the dual reality of industrial volume demand and premium specification expectations. That means evaluating whether concentrate grades, solids ranges, and processing methods are adequately matched to key end-use segments, while also strengthening quality consistency and documentation capabilities. Investment in traceability infrastructure, batch-level control, and application-specific product development can help protect margin stability and improve the ability to serve buyers who increasingly require verifiable sourcing and predictable ingredient performance. Capacity planning should also account for seasonal supply variability, because operational agility will matter as much as scale when harvest outcomes and input costs fluctuate.
PW Consulting
For investors, the opportunity lies in identifying participants that combine sourcing discipline with clear positioning in high-growth value segments. Companies with demonstrable compliance readiness, resilient raw-material relationships, and the ability to serve either industrial or premium channels with consistency are likely to benefit disproportionately as the market rewards reliability and specification leadership. Due diligence should examine not only revenue trajectory and capacity, but also the strength of supply-chain documentation, exposure to trade friction, and the degree to which product differentiation supports pricing flexibility. In a market expanding at a steady mid-single-digit pace, long-term value creation will depend on whether a company can convert operational maturity into competitive insulation from cost volatility and compliance pressure.
For procurement and supply-chain leaders, the practical imperative is to treat sourcing resilience as a strategic variable rather than a transactional one. Diversifying supply bases, clarifying specification requirements early, and establishing procurement terms that account for seasonal variability and documentation needs can reduce exposure to disruption. At the same time, procurement teams should engage suppliers with a clearer view of compliance expectations and quality consistency, since these factors are becoming integral to supplier selection. In this environment, detailed segment intelligence, regional sourcing assessments, and tailored scenario planning can provide a meaningful advantage in negotiating allocation, evaluating alternative origins, and anticipating cost shifts before they affect production schedules.
The concentrated tomatoes market is moving into a phase where scale alone is no longer sufficient to secure durable advantage. The next layer of competition will be defined by traceability maturity, specification relevance, and the ability to maintain dependable supply under changing agronomic and trade conditions. Decision makers who build strategies around these priorities will be better positioned to capture the commercial opportunities embedded in the market’s ongoing expansion. For organizations seeking deeper segmentation data, competitive benchmarking, and region-specific sourcing scenarios, a fuller research assessment can provide the level of detail needed to translate these strategic themes into operational decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Concentrated Tomatoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


