



Probiotic Ingredients for Animal Use: The Real Drivers Behind the 8.2% CAGR to 2032

Global Probiotic Ingredients for Animal Use Market: Strategic Trends and Commercial Opportunities
Market Overview and Critical Challenges
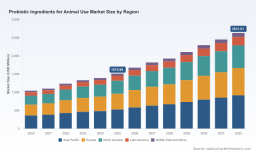
The worldwide market for probiotic ingredients designed for animal applications has entered a sustained growth trajectory, reflecting a fundamental shift in how livestock producers approach animal health and performance. Between 2020 and 2025, the market expanded from approximately $1.05 billion to $1.52 billion, establishing a compound annual growth rate of 8.21 percent through the forecast period extending to 2032. By the end of the projection window, revenue is expected to surpass $2.63 billion. This expansion is not merely a function of volume increases but represents a structural reallocation of spending within animal nutrition portfolios, as producers replace traditional input models with microbiome-focused interventions.
Market distribution reveals clear regional and application patterns. The Asia Pacific region commands the largest revenue share, followed by Europe and North America, highlighting how intensive production systems in densely populated agricultural economies drive early adoption of gut health solutions. The poultry segment consistently leads consumption, with swine and ruminants forming substantial secondary demand pools, while aquaculture and companion animal applications represent smaller but rapidly expanding niches. In terms of formulation, bacteria-based probiotics dominate the ingredient mix, with yeast and fungi-based alternatives occupying a meaningful secondary position. Industry concentration metrics indicate that the top three participants capture just under 39 percent of total revenue, while the top five command slightly more than half, suggesting a moderately consolidated landscape with meaningful room for specialized and regional players.
Despite the clear growth momentum, three structural challenges define the current market inflection point. First, the regulatory environment for feed additives increasingly demands strain-specific safety and efficacy validation. Manufacturers must now produce detailed dossiers that demonstrate performance under commercial production conditions rather than controlled laboratory settings. This requirement raises barriers to market entry and rewards companies with robust clinical data and established regulatory relationships.
Second, technical performance during feed manufacturing remains a persistent constraint. Probiotic viability through steam pelleting, high-temperature conditioning, and extended storage continues to differentiate products in the field. Not all strains survive processing equally, and the gap between laboratory stability and real-world shelf life has become a decisive commercial factor. Spore-forming organisms have gained advantage in this context, but delivery formats, microencapsulation, and postbiotics are actively reshaping how formulators think about survivability.
PW Consulting
Third, antibiotic growth promoter restrictions continue to reshape demand, but the transition is uneven. In some jurisdictions, the removal of in-feed antibiotics has accelerated probiotic adoption; in others, lingering regulatory ambiguity or economic pressures have slowed substitution. The net effect is that demand is real and durable, but pricing power and volume growth depend heavily on local policy clarity and on whether probiotic solutions can demonstrate measurable returns in feed conversion, mortality reduction, or veterinary cost savings.
Key Drivers of Market Change
Technological Innovation and Strain Performance
The competitive center of gravity in this market has shifted from generic microbial suspensions to strain-engineered, application-specific solutions. Bacteria-based probiotics remain the dominant category because of their broad use across poultry, swine, and aquaculture, but leadership increasingly belongs to companies that can articulate strain-level benefits and deliver consistent performance under real production conditions. Spore-forming Bacillus strains, for example, have gained traction in poultry, swine, and aquaculture because their natural stability supports pathogen mitigation and gut microbial balance in environments where storage and feed processing impose stress on more fragile organisms. This technical reality has pushed formulators and producers to evaluate probiotics not just by genus or species, but by survivability, onset speed, and interaction with existing feed programs.
Recent product activity illustrates this direction. In November 2025, Evonik Industries AG showcased an enhanced version of its Ecobiol probiotic with an optimized outgrowth profile designed to support a faster onset of activity in poultry production. Earlier in the year, in August 2025, International Flavors and Fragrances Inc. introduced Enviva DUO, a direct-fed microbial solution combining two bacterial strains to support poultry gut health during challenging conditions. These moves are not isolated product updates; they reflect a strategic pivot toward faster activity, dual-strain synergy, and condition-specific formulations. For commercial buyers, this means the evaluation criteria are expanding beyond price per kilogram to include time-to-effect, resilience under disease pressure, and compatibility with feed processing and water delivery systems.
Policy and Regulatory Environment
Regulatory momentum continues to be one of the most durable demand catalysts for probiotic ingredients in animal use. Restrictions on antibiotic growth promoters have accelerated interest in natural alternatives that support gut health and performance without relying on antimicrobial mechanisms. This policy-driven shift is especially relevant in regions where resistance concerns, consumer expectations, and export market requirements are all pushing producers toward non-antibiotic strategies.
At the same time, the regulatory bar for market access is rising. Strain-specific approvals and efficacy dossiers are becoming standard expectations for entry into major regional markets. In 2025, the European Food Safety Authority evaluated the safety and efficacy of multiple Lactobacillus and Bifidobacterium strains as feed additives for various animal species, reinforcing the broader trend toward evidence-based approvals. This pattern matters commercially because it rewards companies that already maintain validated performance data, established strain libraries, and the capability to navigate multi-jurisdiction registration. It also means that supply commitments and commercial partnerships increasingly depend on documented regulatory status, not just the availability of microbial cultures.
Demand-Side Behavioral Change
Demand is being shaped by more than regulation. Producers are under sustained pressure to improve feed efficiency, reduce mortality, and limit veterinary interventions while maintaining animal welfare standards. In poultry and swine operations particularly, the gut is increasingly treated as a performance interface: a system where microbial balance, nutrient absorption, and pathogen resistance directly affect margin. This mindset encourages procurement teams to view probiotics as functional inputs rather than optional additives.
At the same time, downstream consumers and retail channels are exerting indirect influence. Product claims around reduced antibiotic use, improved animal health, and more sustainable production methods create commercial incentives for producers to adopt gut-health solutions that can be credibly supported. This pressure does not always translate into immediate premium pricing, but it does strengthen the willingness to invest in solutions that have a defensible performance narrative. Yeast and fungi-based probiotics and postbiotic innovations are finding traction in this context, especially where producers want alternatives or complements to bacterial strains, or where specific applications benefit from the functional properties of non-bacterial microorganisms.
Supply Chain and Cost Structure
Cost dynamics are becoming a more important part of the probiotic sourcing conversation. Feed ingredient volatility, processing energy costs, and the economics of specialized fermentation and stabilization all affect the final landed price of probiotic ingredients. Equally important is the cost of technical support. In a market where strain selection, dosing strategy, and integration with feed formulation matter, the total cost of adoption includes service, technical validation, and consistency of supply.
This environment favors suppliers that can offer not only viable microorganisms but also technical reliability across batches and geographies. It also encourages consolidation of capabilities around strain development, industrial-scale fermentation, stability engineering, and application support. For buyers, the practical implication is that procurement decisions are increasingly tied to supply continuity and technical competence rather than short-term price movements. Companies that can maintain performance consistency through pelleting, storage, and on-farm use are better positioned to sustain relationships in a cost-conscious environment.
Competitive Landscape and Leading Strategies
The competitive field in global probiotic ingredients for animal use is defined by a mix of large, diversified nutrition and biosolutions companies, specialized microbial experts, and regional suppliers with strong local application knowledge. The top five participants together account for a modest majority of revenue, but the relatively fragmented structure below that tier creates opportunity for differentiation based on strain portfolio, formulation technology, and segment focus.
A useful way to understand the landscape is through strategic positioning. Some leaders compete on breadth and integration. Firms such as ADM, Cargill, and dsm-firmenich sit within broader animal nutrition and specialty feed additive ecosystems, allowing them to bundle probiotic solutions with other gut health, performance, and nutrition inputs. This integration can be attractive to large producers seeking streamlined sourcing and consolidated technical support. Their advantage lies in the ability to align probiotics with overall feed strategy, offer multi-species portfolios, and leverage existing commercial infrastructure.
Other incumbents compete on microbial specialization and documented strain performance. Novonesis, Kemin Industries, Kerry Group, Church and Dwight Co., and Huvepharma each emphasize particular strengths, whether that is a recognized Bacillus-based program, direct-fed microbial products with pathogen control intent, or strain-specific offerings that target gut morphology, intestinal flora balance, and performance outcomes. Lallemand and Lesaffre extend this specialization into yeast and bacterial solutions, giving them flexibility across animal nutrition and feed applications. Alltech and Phibro Animal Health Corporation maintain strong positioning around natural gut health messaging and direct-fed microbial products, including options that serve specific certification or market-access needs. Life Products Inc. represents a longer-tenured, application-focused profile, with probiotic and microbial feed additive experience across dairy, poultry, swine, cattle, and aquaculture.
What separates stronger competitors from the rest is increasingly not the organism itself in isolation, but the surrounding system: strain selection logic, stability through processing, delivery format, and application support. In poultry, for instance, some companies emphasize Bacillus-based spore-forming stability and pathogen mitigation, while others build differentiation around multi-strain blends or condition-specific formulations. In aquaculture and ruminants, the value proposition often depends on survivability, handling practicality, and the ability to deliver consistent outcomes in more variable production settings. The technical reality that certain Bacillus strains demonstrate superior survival compared with Lactobacillus during steam pelleting is not a minor detail; it shapes product design, sales claims, and ultimately customer adoption.
The market structure appears to be evolving along two paths at once. One is gradual consolidation among participants seeking scale in fermentation, regulatory capacity, and global distribution. Another is continued differentiation among specialists targeting high-value niches such as aquaculture, companion animals, or strain-specific programs with strong clinical backing. New entrants are likely to succeed most readily when they bring a clear technical advantage, such as faster onset, improved viability, dual-strain synergy, or a delivery format that solves a known processing or storage problem, rather than attempting to compete on commodity pricing alone. The recent activity from Evonik and IFF reinforces this point: the most visible product moves center on performance optimization and challenge-specific support, not broad-market commoditization.
Forward Outlook: Trends shaping the next three to five years
Several trends are likely to define the coming half-decade for probiotic ingredients in animal use. The first is the continued shift from generic probiotic inputs toward strain-specific, application-validated solutions. As regulatory expectations and commercial proof requirements rise, products that can document performance in target species and production systems will capture disproportionate attention. The implication for commercial opportunity is that value will concentrate around organizations that can connect strain science to on-farm results and communicate that linkage credibly to procurement and technical teams.
Worldwide Aquaculture Probiotic Clarifier Market
The second trend is the widening of the solution set beyond conventional bacterial probiotics. Postbiotics, yeast and fungi-based probiotics, and blended direct-fed microbial programs are expected to gain relevance where buyers want complementary mechanisms, improved stability, or solutions tailored to specific stress conditions. This diversification will create opportunities for suppliers with strong formulation and stability capabilities, and it will give buyers more options for fitting probiotics into existing feed programs without disrupting processing or performance.
The third trend is increasing technical scrutiny of delivery and survivability. Steam pelleting, storage conditions, and on-farm handling will continue to determine whether a product performs as promised. As a result, differentiation around microencapsulation, spore-forming stability, water-soluble formats, and faster activity onset is likely to become more commercially important than simple organism naming. The risk side is equally clear: where efficacy claims outpace documentation, adoption will stall. In addition, regulatory timing, regional policy divergence, and feed cost volatility can all slow or reshape demand, creating uneven growth across geographies and species segments.
For businesses evaluating this space, the commercial opportunity lies in aligning product capabilities with the where and why of procurement decisions. Poultry and swine will likely remain the largest demand centers, but higher-margin growth may emerge from segments where performance improvement is harder to achieve and where technical service adds disproportionate value, such as aquaculture, ruminants, and companion animals. Companies that can demonstrate repeatable outcomes, maintain supply consistency, and support customers through integration will be better positioned to convert demand into durable share.
Strategic Actions for Decision-Makers
For manufacturers and ingredient suppliers, the priority is to strengthen strain-level differentiation and make performance claims defensible. Investment in stability through processing, faster-onset formulations, and blended or condition-specific programs can create meaningful separation in a market where organism names alone are increasingly insufficient. Equally important is the ability to support customers with technical validation, dosing guidance, and supply reliability across geographies.
Animal Feed Ingredients Market
For investors, the market offers growth supported by durable demand drivers, but value capture will depend on execution quality. Preference should be given to participants with documented efficacy, credible regulatory positioning, and a clear route to species or application specialization. Broad commodity exposure is less attractive than focused capabilities in strain development, stabilization, and application support, especially as customer expectations shift toward proven outcomes and consistent delivery.
For procurement and operations leaders in animal production, the practical task is to evaluate probiotics as system inputs rather than catalog items. Selection should account for survivability through feed processing, compatibility with delivery methods, compatibility with existing nutrition programs, and the quality of technical support behind the product. Where possible, decisions should be grounded in species-specific performance evidence and in the supplier's ability to maintain consistency across batches and seasons.
Given the pace of product evolution, regulatory activity, and regional demand variation, organizations that want to act with confidence should seek detailed segment-level intelligence before committing to long-term sourcing or investment plans. A fuller research report can provide the deeper segmentation, company positioning detail, and regional pathway analysis needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Probiotic Ingredients for Animal Use Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


