



Worldwide School Assessment Tools Market: Why 13.65% CAGR Changes Everything

Worldwide School Assessment Tools Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
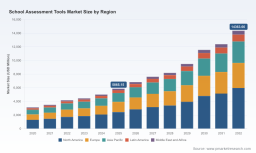
The global market for school assessment tools has entered a phase of accelerated expansion, driven by a fundamental shift in how educational institutions measure student progress, allocate resources, and personalize instruction. From 2020 to 2025, the sector moved from a baseline of approximately $3.1 billion to roughly $5.9 billion, reflecting a compound annual growth rate of 13.65 percent. Projections through 2032 indicate sustained momentum, with the market expected to surpass $14.3 billion in the final forecast year. This trajectory is not merely a function of enrollment growth or regulatory compliance; it represents a structural reorientation of assessment from a periodic, end-of-cycle event to an ongoing, data-rich feedback mechanism embedded in daily instruction. The scale of adoption, combined with broadening use cases across K-12 and early higher education segments, has turned assessment platforms into critical infrastructure for school networks, district administrations, and curriculum publishers alike.
Despite the favorable growth backdrop, the market is navigating several structural tensions that will shape competitive outcomes over the next decade. First, data privacy and regulatory compliance have become non-negotiable design constraints rather than peripheral legal considerations. In the United States, more than 121 state laws now extend student privacy protections beyond federal FERPA requirements, with California's SOPIPA imposing explicit restrictions on how EdTech vendors collect, use, and share student data. In parallel, COPPA violations for platforms serving children under 13 can trigger penalties reaching $51,744 per affected child, compelling vendors to embed strict data minimization, consent workflows, and retention controls into their product architecture. In the European Union, GDPR mandates explicit consent for most processing of children's data and requires data protection impact assessments for platforms serving EU students or international schools. These frameworks are fragmenting compliance requirements across jurisdictions, raising the cost of market entry, and forcing vendors to build privacy-by-design capabilities that smaller or less-resourced competitors cannot easily replicate.
Second, the market is experiencing a tension between customization and standardization. Schools increasingly demand assessments that align tightly with local curricula, multilingual populations, and differentiated instructional models, yet large-scale comparability, accountability reporting, and cross-district benchmarking still require standardized measurement frameworks. This divergence pressures vendors to offer modular, configurable assessment engines that can accommodate local pedagogical needs without sacrificing psychometric rigor or reporting consistency. The operational burden of maintaining multiple assessment variants, scoring rubrics, and data pipelines is substantial, and the firms that can balance flexibility with reliability will capture disproportionate share.
PW Consulting
Third, cost structures and deployment economics are shifting as cloud adoption matures. While cloud-based delivery has become the dominant model, the economics of large-scale educational software deployments remain sensitive to compute, storage, and data egress costs. Typical cloud waste rates in the 27 to 32 percent range mean that even mature operations can face margin pressure if FinOps discipline and architecture optimization are not embedded early. Vendors and district procurement teams alike are scrutinizing total cost of ownership more closely, favoring platforms that demonstrate measurable efficiency gains, predictable scaling, and clear alignment between assessment data and instructional action. These dynamics are compressing the window for undifferentiated point solutions and rewarding platforms that integrate assessment, analytics, and curriculum delivery into coherent workflows.
Key Drivers of Market Change
Technology Innovation and Adaptive Assessment Capabilities
Technology advancement is the most visible catalyst reshaping the assessment landscape. Computer-adaptive testing, once confined to specialized interim and large-scale programs, is increasingly embedded in formative and diagnostic workflows, allowing schools to measure student knowledge with greater precision while reducing testing time and fatigue. The shift toward digitally based assessment is not limited to multiple-choice formats; it increasingly incorporates interactive tasks, scenario-based performance items, and real-world applications that capture higher-order skills such as reasoning, problem-solving, and application. Recent initiatives by the National Center for Education Statistics advancing digitally based assessment for NAEP illustrate how even federal-level measurement programs are moving toward tasks that simulate authentic contexts, signaling a broader expectation that modern assessments should evaluate what students can do, not just what they can recall.
Assessment Services Market
Under the hood, the infrastructure enabling these capabilities is becoming more sophisticated and more accessible. Scalable assessment authoring and delivery platforms allow publishers, school networks, and third-party developers to build, deploy, and analyze assessments without reconstructing the underlying technology stack for every program. This democratization of assessment technology lowers the barrier for new content and assessment formats, while simultaneously raising expectations for interoperability, data quality, and analytics. The practical implication is that assessment is no longer a standalone product category; it is increasingly a data layer that feeds instructional decision-making, resource allocation, and personalized learning pathways. Vendors that can connect assessment outputs to actionable insights, and that can integrate those insights with existing instructional ecosystems, are gaining a durable advantage.
Policy, Accountability, and the Regulatory Environment
Policy dynamics continue to shape demand, but the nature of that influence is evolving. Accountability frameworks have historically driven demand for standardized, summative assessments, yet many education systems are rethinking how assessment data is used to balance accountability with instructional support. The result is a broader portfolio of assessment types gaining traction, including formative tools that guide day-to-day teaching, diagnostic instruments that identify learning gaps early, and interim measures that track progress between major accountability cycles. This diversification is expanding the addressable use cases for assessment vendors beyond compliance-driven procurement, creating opportunities for products that demonstrate clear instructional value rather than mere reporting capability.
At the same time, the regulatory environment is becoming more rigorous and more fragmented. FERPA permits schools to disclose education records to service providers under the school official exception when there is legitimate educational interest, but it requires oversight through contracts that specify data use limitations. This means procurement processes increasingly hinge on the strength of data governance agreements, transparency around data handling, and the vendor's ability to demonstrate compliant architecture. In parallel, state-level privacy laws and international data protection regimes are layering additional obligations onto vendors operating across multiple markets. For providers, this is not merely a legal exercise; it is a competitive differentiator. Organizations that can offer clear consent management, localized data handling options, and auditable compliance documentation are better positioned to win enterprise-level district contracts and cross-border deployments.
Demand-Side Shifts in School Behavior and Procurement
Schools and districts are reevaluating what they expect from assessment tools. The longstanding model of purchasing disconnected testing products is giving way to expectations for integrated ecosystems where assessment data flows directly into curriculum planning, intervention targeting, and progress monitoring. Educators want tools that reduce administrative burden, provide timely feedback, and support differentiation without requiring extensive manual data reconciliation. This demand is especially acute in reading and mathematics, where diagnostic precision and ongoing progress monitoring are central to closing learning gaps and meeting instructional goals. Platforms that combine assessment with aligned instructional pathways, or that integrate seamlessly with widely used core curriculum systems, are therefore capturing stronger adoption momentum.
Procurement behavior is also shifting toward ecosystem fit and total value rather than isolated feature comparisons. District decision-makers are increasingly evaluating whether assessment platforms can interoperate with existing learning management systems, curriculum delivery tools, and data warehouses. Integration partnerships are becoming a strategic lever, because they reduce implementation friction, accelerate time-to-value, and create stickier workflows for teachers and administrators. At the same time, schools are more sensitive to implementation complexity and professional development requirements, favoring solutions that are intuitive, well-supported, and demonstrably linked to improved instructional outcomes. This environment rewards vendors that invest in user experience, integration breadth, and evidence of impact, while challenging those that rely on legacy feature sets without meaningful workflow integration.
Cost Structure Evolution and Cloud Economics
The economics of delivering assessment at scale are changing as cloud infrastructure becomes the default and as vendors and customers alike become more disciplined about utilization. Cloud-based deployment dominates current delivery models, reflecting the advantages of scalability, faster updates, and broader access across device types and geographies. However, scale introduces cost 관리의 complexity. Compute and storage pricing for educational software environments remains relatively granular, and without careful architecture and FinOps practices, organizations can absorb significant inefficiency. This reality is pushing vendors to optimize data pipelines, assessment delivery engines, and reporting workloads to keep marginal costs aligned with growth. It is also pushing district procurement teams to evaluate pricing models that reflect real usage patterns rather than flat, undifferentiated licensing structures.
For vendors, the strategic implication is that cloud economics are no longer a back-office concern; they are a product and pricing design issue. Assessment platforms that can handle spikes in testing demand efficiently, store and process data without unnecessary redundancy, and offer transparent scaling models are better positioned to maintain margin integrity while competing on price and value. For customers, the opportunity lies in selecting platforms that demonstrate operational efficiency and predictable cost behavior, especially as assessment programs expand in frequency and scope. The firms that treat cost efficiency as a product attribute, rather than an afterthought, will have more room to invest in innovation and customer success.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with a handful of large, well-established players holding meaningful share and a broader set of specialized providers competing on differentiation, integration, and regional reach. The market structure favors firms that can combine psychometric credibility, scalable technology, and strong ecosystem positioning. Rather than competing solely on assessment content, leading companies are increasingly competing on data utility, workflow integration, and the ability to connect assessment signals to concrete instructional actions. This is a meaningful shift because it expands the basis of competition beyond test quality into the broader value chain of teaching, learning, and decision support.
Renaissance Learning illustrates the integration strategy clearly. Its Star Assessments are positioned as adaptive, data-rich tools that support K-12 instruction, but the company's recent moves emphasize connectivity with core curriculum providers rather than standing alone as a testing product. The rollout of Star assessment data integration with Great Minds' Eureka Math Squared curriculum, along with an earlier core curriculum integration with the Savvas Realize platform, signals a deliberate effort to embed assessment insights directly into the instructional materials that teachers already use. In parallel, McGraw Hill's integration of Pearson's PRoPL assessment tool into its core curriculum products reflects a similar logic: assessment becomes more valuable when it is tied to curriculum delivery and classroom workflows. Pearson itself continues to offer a broad portfolio, including digital testing platforms and large-scale K-12 assessments, positioning itself as a provider that can span both instructional and measurement needs.
Curriculum Associates has built a strong position around diagnostic and progress monitoring in reading and mathematics through its i-Ready platform, an approach that aligns closely with the demand-side shift toward early identification and ongoing monitoring. NWEA's MAP Growth and other computer-adaptive interim assessment tools have become widely used in U.S. and international schools, benefiting from a reputation for comparability and growth measurement that supports both instructional decision-making and accountability contexts. Educational Testing Service brings deep assessment development expertise and scoring services, which supports custom program development and large-scale testing needs. These players demonstrate that credibility in measurement, combined with strong product execution, remains a foundational requirement, even as integration and data utility become decisive differentiators.
A second competitive dynamic is the rise of platforms and technology providers that enable assessment ecosystems rather than delivering end-to-end branded assessment programs. Instructure offers Mastery and Canvas-based assessment solutions spanning formative, interim, and predictive use cases across K-12 and higher education, leveraging its learning platform footprint to embed assessment into broader teaching workflows. Kahoot! uses game-based formative assessment and quiz tools to drive engagement and real-time feedback, expanding the definition of assessment into more interactive, low-stakes classroom experiences. Edmentum provides online assessment and instructional tools, including Study Island and Exact Path, with a focus on personalized learning pathways. Learnosity supplies scalable assessment authoring and delivery technology that powers many school and publisher assessment platforms, representing a critical infrastructure role in the market. Open Assessment Technologies offers the TAO open-source assessment platform for customizable school and large-scale testing, appealing to organizations that want flexibility and control over their assessment environment.
The strategic implications of this landscape are clear. First, integration and interoperability are becoming decisive. Vendors that can connect assessment data to curriculum platforms, learning management systems, and analytics environments reduce friction for schools and increase the practical value of their tools. Second, there is room for both integration and specialization, but the specialization must be meaningful. Niche providers can thrive by dominating a specific assessment type, subject area, or regional market, but they increasingly need to articulate how their solution fits into broader data and instructional workflows. Third, the market is likely to see continued consolidation pressure, as larger players acquire or partner to expand integration breadth, content coverage, and analytics capability, while nimble specialists compete by serving unmet needs in adaptive diagnostics, multilingual assessment, and scenario-based performance measurement. New entrants with strong technology execution can still gain traction, but only if they solve a clearly defined workflow problem and demonstrate compliance, scalability, and measurable instructional value from the outset.
Future Trends and Strategic Implications
Over the next three to five years, several trends are likely to shape the market's direction and the distribution of commercial opportunity. One major trend is the continued expansion of adaptive and digitally based assessment into everyday instruction, rather than reserving adaptive technology for periodic interim or large-scale tests. As assessment engines become more embedded in formative routines, the value proposition shifts from measurement accuracy alone to speed, usability, and the ability to translate results into immediate instructional adjustments. This creates opportunities for tools that support teachers with clear, actionable recommendations, and for vendors that can demonstrate measurable improvements in teaching efficiency and student progress.
A second trend is the growth of interoperable assessment ecosystems. Schools are unlikely to standardize on a single isolated testing product; they are more likely to assemble stacks that include assessment tools, curriculum platforms, learning management systems, and data analytics layers. This favors vendors that invest in open integration, standards-based data exchange, and flexible deployment models. It also favors technology providers that power assessment authoring, delivery, and analytics for multiple brands and programs, because the underlying infrastructure becomes a strategic bottleneck and a long-term moat. Companies that can serve as reliable assessment technology partners across multiple customers and content providers are positioned to benefit from ecosystem growth even if they do not own the end-user brand.
A third trend is the tightening link between assessment, privacy compliance, and trust. As regulatory expectations rise and procurement processes become more rigorous, compliance capability will increasingly function as a market access condition and a differentiator. Vendors that can offer clear data governance, consent management, regional data handling options, and strong auditability will be better positioned for district-wide and cross-border deployments. The opportunity here is not just risk avoidance; it is the ability to win confidence in environments where data sensitivity is high and the consequences of missteps are severe. At the same time, this trend introduces uncertainty. Regulatory fragmentation can slow cross-market scaling, and overly rigid compliance postures can constrain product innovation if not managed carefully. Firms will need to balance protective design with usable, efficient assessment experiences.
A fourth trend worth noting is the rising importance of evidence and impact. As procurement teams become more sophisticated and budgets face scrutiny, tools that can show a credible connection between assessment use and improved instructional outcomes will gain advantage. This does not require every vendor to produce academic-grade impact studies, but it does favor organizations that can articulate clear usage models, provide transparent reporting, and support implementation in ways that make results observable. The commercial risk for vendors that cannot demonstrate value beyond feature checklists is growing, especially as alternatives multiply and integration expectations rise.
Actionable Guidance for Decision-Makers
For assessment and curriculum providers, the priority is to strengthen integration capacity and data utility while maintaining psychometric and compliance rigor. Product roadmaps should treat interoperability, privacy-by-design, and workflow fit as core features rather than optional enhancements. Partnerships with curriculum platforms, learning management systems, and assessment technology providers can accelerate adoption and increase the practical value of assessment data. Pricing and packaging should reflect real usage patterns and total cost of ownership, because procurement teams are increasingly sensitive to efficiency and predictable scaling. Differentiation will come less from adding more test formats and more from making assessment data immediately useful within existing instructional environments.
Education Software Market
For investors, the market's growth trajectory is attractive, but the dispersion of outcomes will widen. Capital should favor companies with scalable technology architecture, credible measurement expertise, and a clear integration or ecosystem strategy. Interest in infrastructure-oriented providers that power multiple assessment programs, as well as in specialists with strong positioning in adaptive diagnostics or high-demand subject areas, is likely to remain justified. At the same time, due diligence should scrutinize compliance readiness, cloud cost discipline, implementation complexity, and the strength of evidence linking product use to instructional value. Growth alone is not enough; the winners will be those who convert adoption into durable workflow dependency and efficient operations.
For school administrators and procurement teams, selection criteria should expand beyond assessment content to include integration fit, data governance, implementation support, and the clarity of actionable reporting. The most effective platforms are those that reduce burden, connect to existing systems, and help teachers act on results without extensive manual work. Even so, many decisions will benefit from deeper, segmented intelligence on adoption patterns, pricing dynamics, regional compliance requirements, and the relative strengths of competing platforms in specific use cases. Access to more granular market data and customized scenario analysis can substantially improve procurement strategy, partnership choices, and long-term technology planning.
For detailed analysis of this topic, please visit the official page: Worldwide School Assessment Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


