



Flashcard App Market: How 13% CAGR & Platform Shifts Redefine Growth Through 2032

The Flashcard App Market: Strategic Trends and Commercial Opportunities as the Industry Enters a High-Growth Phase
Market Reality at a Crossroads: Size, Momentum, and Structural Challenges
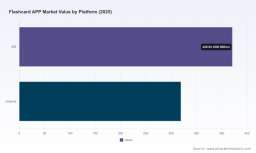
The flashcard application sector has evolved from a niche study utility into a decisive component of the broader digital learning ecosystem. Recent trajectory data shows the market expanding from approximately $385.4 million in 2020 to roughly $740.15 million in 2025, with a projected climb toward $1.74 billion by 2032. This translates into a compound annual growth rate of 13.0 percent across the forecast period, a pace that signals durable demand rather than a temporary pandemic-era surge. The growth story is anchored in habit formation, portability, and the proven cognitive benefits of spaced repetition and active recall. Learners increasingly expect study tools that integrate seamlessly into mobile routines, support collaborative workflows, and adapt to individual pacing. As a result, the category now serves K-12 classrooms, higher education programs, professional certification candidates, and language learners in parallel, each with distinct usage patterns but overlapping expectations for reliability and intelligence.
Despite the headline momentum, the market is navigating several structural pressures that will shape competitive outcomes over the next five years. First, user acquisition costs are rising while retention remains difficult. The low barrier to entry for basic flashcard functionality encourages abundant free alternatives, compressing monetization pathways for standalone apps. Developers must therefore justify premium pricing through differentiated pedagogy, adaptive algorithms, or workflow integration that transcends rote memorization. Second, data governance and cross-border compliance are adding meaningful operational complexity. Educational platforms routinely process personal identifiers, usage telemetry, and in some cases performance records tied to minors or institutional programs. Managing this data under evolving privacy frameworks raises storage and processing overhead, and it forces product teams to reconcile regional requirements with globally distributed user bases. Third, the value proposition is shifting from static card creation toward intelligent, context-aware study experiences. Users increasingly expect generated content, auto-summarized materials, and study flows that connect to notes, documents, and classroom systems. Apps that treat flashcards as isolated objects risk being outpaced by tools that embed memorization into broader knowledge management.
Worldwide Comic Book App Market
These dynamics are also exposing the limits of fragmented ecosystems. Many learners juggle multiple tools for note-taking, flashcard creation, collaboration, and progress tracking, which fragments attention and reduces the perceived ROI of any single app. At the same time, institutional procurement is becoming more deliberate. School districts and universities increasingly weigh accessibility, data residency, integration with learning management systems, and evidence of learning outcomes before adoption. That raises the bar for vendors seeking to move beyond consumer-led growth into structured B2B and institutional channels.
For decision-makers, the implication is clear: the category is large enough to support multiple winners, but growth will accrue to products that can balance open, familiar study mechanics with stronger intelligence, privacy maturity, and institutional integration. Scale alone is not sufficient. The winners will be defined by how well they resolve the tension between low-friction utility and differentiated value.
Key Drivers Reshaping Demand, Product Design, and Margins
Several converging forces are pushing the flashcard app market beyond incremental growth into a phase of product reconstruction. The most visible is the rapid infusion of artificial intelligence into study workflows. Rather than simply digitizing paper cards, leading tools now support automatic conversion of notes, slides, and readings into structured study sets, adaptive scheduling of review items, and contextual hints that reduce friction during practice. This shift matters commercially because it changes the unit economics of content creation. When generation and curation become AI-assisted, the cost of building high-quality decks falls, and the value moves toward curation quality, pedagogical tuning, and trust in the output. It also raises the stakes for differentiation: apps that can reliably turn messy personal materials into usable study assets gain a practical advantage over those that rely entirely on user-built libraries.
At the same time, the regulatory environment is reshaping how apps design data flows and pricing models. Privacy and data-handling requirements for educational tools have increased average storage and processing costs meaningfully for firms that manage personal user data, and they have also introduced cross-jurisdiction compliance considerations for U.S.-based providers operating in European contexts. These dynamics do not just affect legal teams; they influence product architecture, consent design, international rollout sequencing, and the feasibility of certain business models. Companies that treat compliance as a design constraint early gain speed later, while those that retrofit privacy controls face rework and potential delays in expansion. A related infrastructure factor is the expectation of neutral, non-discriminatory access to educational traffic by internet providers. Predictable delivery and low-latency syncing remain important for study apps that depend on frequent, small interactions and real-time collaboration, especially in regions with variable connectivity.
On the demand side, learner behavior is changing in ways that reinforce the category while changing how it is used. Students and professionals increasingly treat flashcards not as isolated memorization aids but as part of an integrated study loop that includes reading, note-taking, self-testing, and review scheduling. This is especially pronounced in higher education and professional certification preparation, where the volume of material is large and the cost of ineffective study is high. In language learning, the appeal lies in repeated exposure and spaced practice, but users also expect content that reflects real-world usage rather than static vocabulary lists. Corporate training and professional upskilling add a third demand vector: learners want short, repeatable practice sessions that fit around work schedules and tie back to measurable competency. Together, these behaviors push vendors to support multiple learning modes, progress tracking, and collaborative deck sharing, rather than a single generic review screen.
Supply-Side and Cost Structure Shifts
On the supply side, development costs are being redistributed. The marginal cost of building a basic flashcard engine has fallen, but the cost of maintaining reliable syncing, moderating community content, ensuring accessibility, and delivering AI features with consistent quality has risen. Open-source roots and community ecosystems can reduce development risk and accelerate trust, but they also require strong stewardship to keep quality and sustainability aligned. Proprietary platforms can move faster on integrated experiences and monetization, but they face higher expectations for polish, support, and data stewardship. In parallel, cloud infrastructure, compliance-related processing, and ongoing content moderation all contribute to a cost base that favors vendors with scale, disciplined product scope, and efficient moderation workflows. The result is that competitive advantage increasingly comes from operational discipline as much as from feature novelty.
Taken together, these drivers point to a market where value is shifting from the presence of flashcards to the quality of the study system surrounding them. The apps that capture durable share will be those that can combine intelligent content workflows with credible privacy practices, dependable performance, and a pedagogy that users can feel working in day-to-day practice.
Competitive Landscape: Strategy, Positioning, and the Shape of Market Evolution
The competitive field is defined by a mix of established study platforms, open-source-rooted tools, and newer entrants focused on AI-enabled content generation. A small group of leaders currently accounts for a majority of market share, reflecting the category’s maturity in consumer adoption and the advantage of scaled content libraries, brand recognition, and institutional relationships. Concentration of this kind is typical in education technology, where network effects in user-generated content and classroom adoption reinforce incumbency. Yet the landscape is not static, because the value frontier is moving toward integration, intelligence, and stewardship rather than raw library size alone.
PW Consulting Information & Electronics Research Center
Quizlet illustrates one dominant playbook: scale through community-generated content paired with product-led classroom workflows and AI features that reduce study setup time. Its recent expansion into an integrated experience inside conversational AI environments reflects a strategy of meeting learners where they already work, turning prompts, notes, and documents into study materials with minimal friction. The strategic logic is straightforward. If creation and retrieval become easier, usage frequency rises, and the platform becomes a default study layer rather than one tool among many. Brainscape takes a more pedagogy-forward posture, emphasizing confidence-based spaced repetition and structured decks designed for long-term retention. Its differentiation rests on the claim that better scheduling and clearer self-assessment produce more efficient learning, which appeals to exam preparation and disciplined self-study. Anki and the broader ecosystem around it occupy a different position: highly customizable, offline-capable, and supported by a strong add-on culture. That model has sustained a loyal user base among learners who want control over card structure, review logic, and local data. The recent transition of day-to-day operations and open-source stewardship to AnkiHub signals a broader pattern in which community-driven projects seek sustainable governance without abandoning openness. AnkiHub’s collaborative deck platform and premium syncing services show how a community-backed tool can evolve toward paid support and shared content while preserving its core value proposition.
Tablet Pc Note App Market
Emerging Hybrids and New Entrants
Newer entrants are exploring a different middle ground. Knowt exemplifies the AI-first content path, focusing on converting existing notes and documents into study sets with spaced repetition features. RemNote blends note-taking and flashcard creation into a single interconnected system, appealing to learners who want their reading, notes, and review loops to belong to one workspace. These hybrids matter because they address a real pain point: study tools often fail when content creation is disconnected from note capture or when review is isolated from the material being learned. By collapsing those steps, hybrid tools reduce setup cost and create more coherent learning workflows.
The market is therefore evolving along two simultaneous axes. On one axis, consolidation incentives are strong: large platforms with broad libraries, classroom integrations, and AI capabilities can pull usage into a single environment and monetize through premium subscriptions, institution-level contracts, and enhanced productivity features. On the other axis, specialization and open ecosystems remain viable, particularly for users who value customization, data locality, and transparent methods. Importantly, new entrants are not just competing on features; they are competing on trust, workflow coherence, and the credibility of their pedagogical claims. That means the next round of competitive differentiation will likely come from evidence of learning impact, reliability of generative outputs, privacy design, and the ability to integrate into broader knowledge workflows rather than from card-making alone.
Forward View: Three Trends That Will Define the Next Three to Five Years
One of the most consequential trends is the shift from flashcard creation to automated study-system assembly. Over the next few years, the most-used tools will likely be those that can ingest notes, slides, and readings, then produce structured review sequences with minimal manual effort. This trend opens commercial opportunities for vendors that can differentiate on curation quality, discipline-specific content templates, and confidence in generated materials. The opportunity is not simply generating more cards; it is reducing the time from raw material to effective review while maintaining accuracy and pedagogical coherence. Companies that nail that workflow can increase engagement and justify premium tiers based on time savings and outcomes rather than simple access.
A second trend is the deepening of privacy, compliance, and trust as competitive differentiators rather than back-office concerns. As expectations around data handling rise and as educational apps continue to operate across jurisdictions, platforms that offer transparent data practices, predictable storage architectures, and clear consent models will gain an advantage in institutional sales and in cautious consumer segments. This is particularly relevant for tools used by K-12 learners and in regulated academic environments, where procurement teams scrutinize data residency, retention, and access controls. The commercial implication is that trust can become a moat: it reduces friction in enterprise procurement, supports international expansion sequencing, and lowers the risk of costly retrofits later.
A third trend is the movement toward integrated knowledge workflows that connect memorization with note-taking, collaboration, and performance tracking. The apps most likely to capture durable share are those that let learners move smoothly from reading to note capture to self-testing to review scheduling, without exporting content between disconnected tools. This favors hybrid architectures and platform-level integrations, especially where classrooms and institutions already rely on collaborative systems. The opportunity lies in becoming the connective tissue for study, not just a card repository. At the same time, this trend carries uncertainty. AI-generated content can introduce quality variability, institutional adoption can slow if evidence of outcomes is thin, and rising compliance costs may pressure margins for smaller players. The market will likely reward disciplined operators who can balance automation with quality assurance and who can prove that their workflows improve retention and throughput rather than simply adding features.
Actionable Implications for Decision-Makers
For product and platform leaders, the priority is to strengthen the study loop end to end. That means investing in content ingestion and generation that is accurate and discipline-aware, refining spaced repetition logic so it feels effective in daily use, and ensuring that syncing, accessibility, and support are dependable enough to underpin institutional confidence. Differentiation should be anchored in workflow coherence and trust, not in the number of card formats alone. For investors, the attraction is in platforms that combine scalable content workflows with credible monetization paths, whether through premium consumer tiers, institutional contracts, or value-added features that reduce learner time-to-results. Due diligence should focus on retention economics, content quality controls, compliance readiness, and the defensibility of integrations that tie study tools into broader learning environments. For procurement and education leaders, the selection process should weigh evidence of learning impact, data governance, and the ability to fit within existing classroom or enterprise systems, since the cost of tool sprawl and data risk can outweigh the appeal of feature richness.
The strategic stakes are rising as the category scales toward broader adoption and more demanding users. Detailed segmentation data, company-level profiles, and scenario-dependent projections can sharpen planning by revealing where growth is most concentrated, which business models are gaining traction, and where compliance or workflow gaps may slow expansion. Readers seeking a deeper dive into segment dynamics, competitive positioning, and tailored strategic options can find the full research report through the reference link below.
For detailed analysis of this topic, please visit the official page: Flashcard APP Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


