



Mechanical Chucks Market: Why 4.4% CAGR and Packaging Demand Redefine Growth

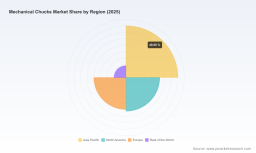
Mechanical Chucks Market: Strategic Trends and Commercial Opportunities Through 2032
The global mechanical chucks market has demonstrated consistent expansion over the past half-decade, with valuations climbing from approximately 601.12 million USD in 2020 to 742.5 million USD in 2025. Looking ahead, the sector is projected to reach the 1 billion USD threshold by 2032, supported by a compound annual growth rate of 4.4 percent across the 2026 to 2032 forecast period. This trajectory reflects sustained capital expenditure in precision manufacturing, steady replacement cycles for aging workholding equipment, and incremental but meaningful technology migration across industrial workshops worldwide. The market remains moderately fragmented, with the top five suppliers accounting for roughly 27.12 percent of revenue and the top three holding approximately 18.45 percent. This concentration profile indicates that while scale players command meaningful share, substantial value remains distributed among specialized and regional manufacturers capable of delivering application-specific solutions.
Beneath the headline growth figures, the industry is navigating a series of transition points that will define competitive outcomes over the next several years. First, the pricing and availability of structural raw materials have introduced renewed margin pressure. Steel continues to serve as the dominant input for mechanical chucks used in machine tool workholding, with United States prices stabilizing in the low-to-mid 800 dollars per short ton range into early 2026 amid moderate volatility. Tool steels such as D2 and H13, critical for high-precision chuck components, command elevated relative pricing due to the stringent performance demands of demanding machining applications. Manufacturers must balance input cost resilience with the need to preserve competitive pricing in cost-sensitive segments. Second, trade policy has become a more prominent cost variable. Elevated Section 232 steel tariffs, increased to 50 percent in 2025 for certain imports, have affected the landed cost of imported machine tool components including chucks, reshaping sourcing strategies for distributors and end-users in tariff-exposed markets. Third, the demand environment is shifting from volume-driven replacement toward performance-driven specification. Increasing demand for automation and precision in manufacturing is driving adoption of advanced mechanical chucks featuring equalising jaws, high gripping strength, and integrated coolant delivery. This shift rewards suppliers that can demonstrate measurable gains in workpiece security, cycle stability, and setup flexibility rather than those competing primarily on unit price.
These dynamics converge on a central reality: the mechanical chucks market is moving from a mature, commodity-leaning category toward a more specification-led, value-differentiated segment. Companies that can align product engineering with regional cost structures, navigate trade-related input pressures, and articulate clear productivity benefits will be best positioned to capture share as the market scales toward the next billion-dollar milestone.
Key Drivers Reshaping Demand and Competitive Value
Technological Innovation and Precision Workholding
Advances in chuck design are redefining what manufacturers expect from workholding. Equalising master jaws, high-gripping strength mechanisms, and integrated coolant pathways have moved from niche features to baseline expectations in many machining environments. These capabilities reduce workpiece deflection, improve surface finish consistency, and enable secure clamping of large rough castings and forgings that previously required multiple setup adjustments. The broader trend toward automation and precision in manufacturing is accelerating this transition, as producers seek chucks that integrate cleanly with programmed workflows and reduce operator-dependent variability. Suppliers that engineer for repeatability, rigidity, and ease of changeover are gaining preference in segments where setup time and clamping reliability directly influence throughput.
Mechanical Presses Market
Policy and Trade Environment: Cost, Sourcing, and Regionalization
Trade policy has become a structural factor in chuck procurement and production planning. The increase in Section 232 steel tariffs to 50 percent in 2025 for certain imports has raised the cost base for imported machine tool components, prompting decisive shifts in sourcing footprints. Some end-users and machine tool builders are reweighting procurement toward domestic or tariff-advantaged supply, while others are recalibrating bill-of-materials choices to offset higher input costs. At the same time, regional export strength from Taiwan and Japan in high-precision power and mechanical chucks has remained robust, with manufacturers actively showcasing solutions at major industry events. This combination of tariff pressure and established export capabilities is encouraging a more geographically diversified supply base, with procurement teams weighing total cost of ownership, lead-time reliability, and specification fit rather than relying on a single sourcing lane.
Demand-Side Shifts in Packaging, Metalworking, and Web Processing
End-use demand is evolving across multiple verticals, creating differentiated growth pockets. Packaging and converting continues to anchor a substantial share of chuck demand, driven by high-speed line requirements, core handling precision, and rolls handling safety. Metalworking and machine tools remain a core application base, with turning and milling operations seeking workholding that supports tighter tolerances and heavier cuts. In parallel, printing and textiles, along with paper and pulp manufacturing, sustain steady demand for core chucks and roll-handling solutions that emphasize safe unwind, rewinding, and shaft-less core management. Across these applications, the common thread is a move toward equipment that reduces downtime, improves operator safety, and maintains grip integrity under variable load conditions. Manufacturers that tailor mechanical solutions to the operational rhythms of each vertical are finding stronger retention and more favorable specification positioning.
Supply Chain and Cost Structure Considerations
Input volatility and logistics complexity continue to shape how chuck manufacturers structure their cost bases. Steel price stabilization in the low-to-mid 800 dollars per short ton range has provided some predictability, yet tool steel premiums and periodic swings still require active inventory and hedging discipline. Beyond raw materials, the cost equation increasingly includes compliance with evolving safety expectations, engineering for energy efficiency, and the operational expense of serving custom and standard product lines simultaneously. Companies that streamline design-for-manufacturing, standardize common interfaces across product families, and maintain selective vertical integration for critical components are better able to protect margins while remaining responsive to custom specification requests.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is anchored by a mix of precision-focused European manufacturers, high-capability Asian exporters, and specialized North American and European workholding specialists. This diversity is a defining strength of the market, as it allows end-users to select suppliers based on application fit, regional service proximity, and the balance between standard and custom offerings. Leadership in this environment is less about sheer scale and more about the ability to deliver repeatable precision, engineering responsiveness, and reliable integration with broader machine tool and production systems.
Several incumbent groups illustrate the strategic paths that are currently shaping the market. Global leaders in clamping devices have built reputations around comprehensive mechanical lathe chuck and drill chuck portfolios, pairing broad application coverage with high-precision standards for machine tools. Their advantage lies in catalogue depth, consistent quality, and the ability to serve a wide range of standard and semi-custom requirements across multiple regions. In turning applications for demanding machining environments, long-established specialists emphasize decades of experience and rugged mechanical and power chuck solutions designed for stability under heavy cutting loads. These firms differentiate through application know-how, robust component engineering, and service networks that reduce downtime for operators running high-utilization workflows.
On the heavy-machining side, manufacturers offering power and mechanical chucks with equalising capabilities are expanding their addressable scope for large rough castings and forgings. Recent product extensions, including new models with equalising master jaws engineered for secure gripping of large workpieces, illustrate how incumbents are pushing into higher-value applications that reward clamping security and setup flexibility. Taiwanese and Japanese suppliers continue to strengthen their export positions in high-precision power and mechanical chucks, leveraging active participation in major trade events and a focus on features such as ultra-thin rotary cylinders, large compound chucks for vertical lathes, and custom jaw solutions that emphasize energy efficiency and operator safety. These companies are competing not only on price but on engineering specifics that matter to machine tool builders and end-users seeking to optimize footprint, cycle time, and handling safety.
Regional specialists add further texture to the landscape. In the United States and Europe, workholding-focused manufacturers provide custom and standard mechanical chucks designed for milling, CNC, and industrial applications, often emphasizing gripping strength, rigidity, and coolant delivery for demanding use cases. Precision scroll and independent mechanical chuck producers serve metalworking customers that value manual and power options with reliable, time-tested geometries. In web processing, mechanical core chuck specialists deliver solutions for roll handling, unwinding, and rewinding, focusing on safety and precision for shaft-less unwinders and rewinders as well as air-assisted and mechanical core chucks for winding systems. The presence of these application-oriented players indicates that the market is unlikely to consolidate into a single dominant model; rather, differentiation by application, region, and service model will remain the primary axes of competition.
Looking at structural evolution, the market is likely to see continued specialization alongside selective consolidation. Larger players may pursue targeted acquisitions to broaden application coverage or strengthen regional service capabilities, while smaller specialists will compete by deepening domain expertise and offering tailored solutions that generalist catalogues cannot easily replicate. New entrants are most likely to succeed by focusing on underserved application niches, improving integration with automation workflows, or delivering cost-competitive precision through disciplined manufacturing and design standardization. Trade dynamics and input cost conditions will continue to influence where production and sourcing are located, reinforcing the value of a flexible, multi-node supply strategy.
PW Consulting
Forward Outlook: Three Trajectories Shaping the Next Three to Five Years
The first trajectory is the continued migration toward specification-led purchasing. As manufacturers pursue automation and precision gains, mechanical chucks with equalising jaws, high gripping strength, and application-specific features will see stronger adoption in metalworking, heavy machining, and high-speed converting environments. The commercial implication is clear: suppliers that can quantify the productivity impact of advanced clamping features will gain preference in bids where setup reliability and workpiece security are decisive. This trend favors engineering transparency, application benchmarking, and close collaboration with machine tool builders and line designers.
The second trajectory is a more deliberate regionalization of supply and sourcing. Trade policy effects and input cost variability are encouraging procurement teams to diversify supply bases, nearshore where feasible, and prioritize total cost of ownership over lowest unit price. For chuck manufacturers, this means that regional service capacity, inventory positioning, and the ability to offer tariff-advantaged configurations will increasingly influence purchasing decisions. Companies that can support local lead times without sacrificing precision standards are likely to capture incremental share from single-source dependency models.
The third trajectory is the widening role of safety, energy efficiency, and operator-centric design. Recent industry showcases have highlighted features such as ultra-thin rotary cylinders, large compound chucks for vertical lathes, and custom jaw solutions that reduce handling risk and improve energy efficiency. As workforce availability and operating cost pressures intensify, these attributes will move from differentiators to requirements in many purchasing decisions. The opportunity lies in packaging these features into standard families that simplify specification while preserving the flexibility needed for custom applications. Potential risks include continued raw material volatility, tariff escalation on specific import categories, and uneven demand recovery across regions and verticals, which could pressure margins for suppliers with limited cost flexibility or over-reliance on a single application channel.
Strategic Actions for Decision-Makers
For manufacturers and machine tool builders, the priority is to align product and sourcing strategies with the transition toward precision-led specifications and tariff-aware procurement. This includes evaluating design standardization opportunities that lower cost while preserving performance, securing input supply for critical tool steels and steel grades, and building regional service and inventory capabilities that reduce lead-time risk. Suppliers should also invest in demonstrating measurable productivity outcomes from advanced clamping features, since specification decisions are increasingly tied to setup stability, cycle consistency, and operator safety.
For investors, the market’s moderate concentration and diversified application base suggest value in companies with clear engineering differentiation, disciplined cost management, and exposure to resilient demand channels such as packaging and converting, metalworking machine tools, and web processing. Due diligence should weigh not only revenue growth but also margin resilience under raw material and trade-policy variability, the breadth of standard-versus-custom product mix, and the strength of regional service and export capabilities. Companies that can scale precision solutions into higher-value applications while maintaining cost discipline are best positioned to translate market growth into durable profitability.
For procurement and operations leaders, the practical imperative is to evaluate chuck suppliers on total cost of ownership, specification fit, and reliability under real production conditions rather than on headline price alone. This means prioritizing clamping security, ease of changeover, and safety features that reduce downtime and handling risk, while also mapping supply continuity against tariff exposure and lead-time volatility. Engaging suppliers early in machine design or line configuration can unlock more efficient workholding architectures and avoid costly retrofits later. In a market that is growing steadily but changing in how value is created and captured, timely access to detailed segmentation data, regional pricing dynamics, and supplier benchmarking will be essential to sharpen sourcing decisions and investment prioritization. For those seeking a deeper look at segment-level dynamics, regional nuances, and tailored scenario planning, the full PW Consulting market research report provides the granular data and structured recommendations needed to act with confidence.
Electrostatic Chucks for Wafer Market
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Chucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


