



Worldwide Ice-phobic Coating Market Surging Past 13% CAGR: Key Demand Shifts by 2032

Navigating the Global Ice-Phobic Coating Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global ice-phobic coating market has undergone substantial transformation over the past five years, expanding from approximately USD 98.45 million in 2020 to USD 168.22 million in 2025. This trajectory reflects a compound annual growth rate of 13.38 percent, with projections indicating the market will reach USD 405.46 million by 2032. Such sustained expansion underscores a broader industrial shift toward passive ice protection solutions that reduce reliance on energy-intensive de-icing systems and mitigate operational disruptions caused by ice accumulation across critical infrastructure.
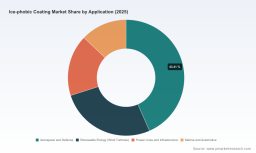
Behind these headline figures lies a market characterized by uneven maturity levels across application verticals and geographic regions. Aerospace and defense applications continue to command the largest revenue share, driven by stringent safety requirements, harsh operating environments, and the high cost of operational downtime. Renewable energy, particularly wind turbine blade protection, represents the fastest-growing application segment as operators seek to maintain power output and blade integrity in cold climates. Power lines and infrastructure, alongside marine and automotive use cases, demonstrate steady but more fragmented adoption patterns shaped by localized weather risks and varying regulatory mandates.
Several structural challenges define the current inflection point for industry participants. First, durability and environmental degradation remain persistent technical hurdles. Ice-phobic coatings must withstand UV exposure, thermal cycling, abrasion, and chemical exposure while maintaining low ice adhesion over multi-year service intervals. Coatings that degrade prematurely force costly reapplication cycles, eroding the total cost-of-ownership advantage that drives procurement decisions. Second, the regulatory landscape is tightening around fluorinated chemistries. Many traditional low-surface-energy formulations rely on perfluorinated compounds, and growing scrutiny of persistent chemicals is pushing developers toward PFAS-free or fluorocarbon-free alternatives without sacrificing performance. This transition introduces formulation complexity, re-validation costs, and in some cases, trade-offs between repellency and mechanical durability. Third, certification pathways for aviation and critical infrastructure applications remain lengthy and capital-intensive. Validating ice adhesion reduction, wear resistance, and performance under operational thermal conditions requires extensive laboratory and field testing, creating barriers that favor established players with existing qualification relationships while slowing the commercialization cadence of newer entrants.
These dynamics create both pressure and opportunity. Companies that can deliver durable, certifiable, and environmentally compliant formulations at scale are positioned to capture premium market segments, while those dependent on legacy chemistries or lacking validation infrastructure face erosion in competitive positioning. The market is not merely growing; it is re-segmenting around performance reliability, regulatory alignment, and application-specific engineering.
Key Drivers Shaping Market Trajectory
Several interconnected forces are accelerating adoption and reshaping competitive priorities across the ice-phobic coating landscape. Understanding these drivers is essential for anticipating where demand will concentrate and which capabilities will differentiate winners.
Technological Innovation and Performance Breakthroughs
Advances in material science are expanding the performance envelope of ice-phobic coatings beyond simple hydrophobicity. Nanocomposite formulations incorporating silica nanoparticles, silicone-based matrices, and hybrid organic-inorganic architectures are delivering improved ice adhesion reduction alongside enhanced resistance to erosion, corrosion, and UV degradation. One-part and moisture-cured systems are gaining traction because they simplify application on complex geometries such as wind turbine blades, aircraft leading edges, and power line components. At the same time, slippery liquid-infused porous surface technologies are pushing the boundaries of ultra-low ice adhesion, offering self-healing characteristics and repellency across a broader range of environmental conditions. These innovations are shifting the value proposition from basic ice shedding to multifunctional surface engineering that also addresses fouling, soiling, and signal interference.
Anti-Fog Coatings Market
Regulatory and Environmental Pressures
Environmental compliance is emerging as a decisive market force. The industry trend toward PFAS-free and fluorocarbon-free formulations reflects both regulatory momentum and customer ESG requirements, particularly in aerospace, defense, and publicly regulated infrastructure. Formulators are responding with solvent-based hybrid systems, epoxy-based composites, and surface treatments that maintain low surface energy without relying on long-chain fluorinated compounds. However, regulatory transitions are not uniform across regions or applications, and aviation coatings must still satisfy rigorous certification regimes that validate durability, adhesion, and thermal performance. This regulatory complexity increases development costs but also creates a protective moat for manufacturers that can navigate qualification processes efficiently.
Demand-Side Shifts in Critical Infrastructure and Energy
Operational resilience is driving procurement behavior across multiple sectors. Wind turbine operators in cold-climate regions are increasingly prioritizing passive ice protection to sustain energy yield, reduce blade fatigue, and defer mechanical de-icing capital expenditure. In aerospace, operators seek coatings that reduce ice accumulation on wings, propellers, sensors, and engine components while minimizing weight and maintenance burden. Utility and infrastructure managers face growing pressure to mitigate ice loading on transmission lines and critical assets during extreme weather events. These demand-side shifts are not cyclical; they reflect long-term exposure to colder operating environments, higher availability expectations, and the rising cost of unplanned downtime. As a result, procurement decisions are increasingly evaluated on total lifecycle value rather than upfront coating cost alone.
Supply Chain and Cost Structure Evolution
Raw material selection and application logistics are reshaping cost structures. Common feedstocks such as fluoropolymers, polydimethylsiloxane, silica nanoparticles, and perfluorinated or alkoxysilane precursors influence both formulation performance and supply risk. Manufacturers are balancing the performance benefits of fluorinated chemistries against supply volatility and regulatory exposure, while exploring alternative architectures that can be applied by brush, spray, or wipe without specialized equipment. Application certification programs and scalable production methods are becoming differentiators, particularly for wind turbine and infrastructure markets where field application consistency directly affects performance outcomes. Companies that streamline application workflows and secure reliable feedstock pipelines are better positioned to scale without compromising quality or margin.
Competitive Landscape and Leading Strategies
The market features a mix of specialized materials developers, application-focused coating suppliers, and research-driven innovators. Competitive positioning is increasingly defined by formulation architecture, certification track record, application scalability, and environmental compliance rather than price alone.
Strategic Positioning Among Leading Participants
Several companies illustrate the breadth of strategic approaches shaping the market. NEI Corporation has built a commercial presence around nanocomposite anti-ice coatings that combine reduced ice adhesion with hydrophobic properties and UV protection, targeting aerospace, wind, power line, and marine applications across multiple substrate types. The emphasis on one-part formulations and flexible application methods reflects a strategy centered on ease of deployment and broad substrate compatibility.
Aerospace & Advanced Composites GmbH represents a strong focus on fluorocarbon-free and PFAS-free systems, offering solvent-based and hybrid SLIPS formulations designed for extreme cold, heat, and moisture conditions. Its product architecture targets ultra-low ice adhesion while maintaining hydrophobic and easy-clean characteristics, appealing to industrial and aerospace customers seeking to align performance with environmental standards.
NanoSonic, Inc. emphasizes durability in harsh operational settings, with hybrid nanocomposite coatings validated for corrosion, erosion, abrasion, and UV resistance. Targeted at naval superstructures, military drones, and similar extreme environments, the company's single-component moisture-cured formulations highlight a strategy built around robustness and application simplicity for defense and marine use cases.
Cytonix LLC continues to develop fluorochemical-based ice-repellent and superhydrophobic coatings for antennas, radomes, marine, and general surface protection. Its smooth, low-surface-energy formulations are oriented toward signal preservation and operational reliability in adverse weather, reflecting a niche where functional performance in telecommunications and marine settings creates a distinct value proposition.
Super Hydrophobic Nano Coating Market
Elemental Coatings has concentrated on durable anti-icing and anti-scaling solutions for aerospace, transportation, energy, marine, and consumer applications, with an emphasis on low ice adhesion and scalability for large surfaces. Public funding relationships for aircraft-related applications illustrate how endorsement and validation can accelerate credibility in high-assurance sectors.
PW Consulting
Adaptive Surface Technologies has commercialized SLIPS-based platforms for icephobic, foul-release, and repellent applications across aviation, marine, industrial, and medical markets. Its focus on ultra-low ice adhesion and self-healing properties, along with public funding support for aircraft anti-icing, underscores a technology-led strategy aimed at high-performance use cases where repellency and resilience are critical.
Aculon, Inc. develops nanoscale hydrophobic and oleophobic surface treatments with icephobic relevance across optics, electronics, metals, and industrial substrates. Its thin, durable, PFAS-free options reflect a strategy oriented toward precision applications where surface finish and chemical compliance intersect.
Phazebreak Coatings has built a notable commercial footprint in wind turbine blade protection, with its icephobic coating installed on a substantial number of blades globally since its launch. The company's focus on passive ice protection, applicator certification programs, and variants tailored to warmer climates demonstrates a market-specific strategy that prioritizes field validation, application quality control, and climate-adapted product segmentation.
Market Structure Evolution
The competitive landscape is evolving along multiple axes. On one hand, consolidation potential exists as larger materials and coatings players seek to acquire specialized ice-phobic capabilities to broaden their surface engineering portfolios. On the other hand, market fragmentation persists because application requirements vary dramatically across substrates, climates, and certification environments, making single-formulation dominance difficult. New entrants continue to emerge from academic and national laboratory research pipelines, bringing advanced architectures such as dynamic epoxy-based composites, nanostructured surfaces, and photothermal approaches into commercialization pathways. Public funding mechanisms and small business innovation programs are playing a meaningful role in bridging early-stage development and field validation, particularly in aerospace and defense.
The practical implication is that competitive advantage will increasingly depend on three capabilities: the ability to deliver certifiable, durable performance in target applications; the capacity to formulate compliant chemistries without sacrificing repellency; and the operational competence to ensure consistent field application at scale. Companies that integrate product development with application training, qualification support, and climate-specific product variants are likely to capture greater share in high-value segments.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define market direction and shape commercial opportunity.
Accelerated Adoption in Renewable Energy and Infrastructure
Wind turbine blade protection and power line infrastructure are expected to drive a disproportionate share of incremental growth. As cold-climate wind deployment expands and operators seek to protect asset longevity and revenue consistency, demand for field-validated, scalable ice-phobic solutions will intensify. Commercial opportunity will center on coatings that balance ice adhesion reduction with erosion resistance, enable reliable field application, and integrate with existing maintenance workflows. Variants tailored to different climate bands will become more important as manufacturers serve geographically diverse fleets.
Regulatory-Driven Chemistry Transitions
The shift toward PFAS-free and fluorocarbon-free formulations will move from a compliance exercise to a competitive requirement in many segments, particularly where public procurement, environmental permitting, or customer ESG expectations influence purchasing. This transition will reward formulators that can demonstrate comparable durability and ice repellency without relying on regulated chemistries. At the same time, it may create short-term friction in applications where fluorinated materials have historically delivered the best balance of performance and robustness. Organizations that invest early in alternative chemistries and validation will be better positioned to capture procurement cycles as standards tighten.
Certification as a Strategic Bottleneck and Moat
Certification and field validation will remain both a barrier and a competitive advantage. Aviation and critical infrastructure applications require demonstration of durability under thermal cycling, wear, and operational stress. The organizations that can efficiently manage testing, documentation, and qualification relationships will gain a structural edge in high-assurance markets. Commercial opportunity lies not only in coating performance but in the surrounding service model: application protocols, operator training, quality assurance, and post-application monitoring. In this context, certification-capable suppliers may command premium positioning even when alternative products are technically feasible.
Risks and uncertainties remain. Durability gaps in demanding environments could lead to reapplication costs that weaken economic justification. Regulatory timelines and substance restrictions may evolve unevenly across jurisdictions, complicating global product strategies. Supply chain volatility for specialty nanoparticles and silane precursors could affect formulation consistency and margin. Finally, overpromotion of performance claims without robust field validation may erode buyer trust and slow adoption in risk-averse procurement environments. Companies that manage these uncertainties through disciplined testing, transparent performance data, and conservative commercialization pacing will be better positioned to sustain growth.
Strategic Implications for Decision Makers
The evolving ice-phobic coating market presents distinct implications depending on organizational role and strategic objective.
For coating manufacturers and materials developers, the priority is to align formulation roadmaps with the twin demands of performance durability and environmental compliance. Investing in PFAS-free or fluorocarbon-free systems, validating long-term adhesion and erosion resistance under realistic thermal and mechanical conditions, and building application protocols that ensure field consistency will separate credible suppliers from commodity competitors. Where relevant, pursuing qualification pathways and public funding mechanisms can accelerate credibility in high-assurance sectors such as aerospace and defense. Diversification into climate-specific variants and multi-substrate compatibility can broaden addressable markets without diluting core technical strengths.
For investors, the most attractive opportunities lie where adoption drivers are structural rather than cyclical. Renewable energy ice protection, aviation anti-icing, and infrastructure resilience all reflect long-term exposure to operational risk, availability expectations, and extreme weather frequency. Due diligence should focus on durability validation, certification readiness, feedstock supply resilience, and the company's ability to scale application processes rather than on marketing claims alone. Companies with defensible qualification relationships, clear compliance strategies, and demonstrated field deployments are more likely to sustain premium positioning as the market matures.
For procurement and asset operators, the decision framework should move beyond unit price toward total cost of ownership and risk reduction. Evaluating ice adhesion performance under relevant environmental conditions, expected service life, reapplication frequency, application complexity, and certification status provides a more accurate basis for supplier selection. Where operational downtime is costly or safety-critical, partnering with suppliers that offer application certification, quality control support, and climate-adapted product variants can materially improve outcome reliability. Procurement teams should also monitor regulatory trends that may affect chemical compliance over the service life of coated assets.
For organizations seeking a structured assessment of segmentation dynamics, regional demand patterns, competitive positioning, and tailored commercial recommendations, the full market research report provides the detailed data and scenario analysis needed to translate these trends into actionable strategy. The complete study examines revenue trajectories, application-specific adoption drivers, regional nuances, and company-level benchmarks in greater depth, supporting more precise planning across product development, investment allocation, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Ice-phobic Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


