



Consumer Electronics Accessories Market: Why 6.57% CAGR Reshapes Growth Through 2032

Strategic Trends and Commercial Opportunities in the Worldwide Consumer Electronic Accessories Market
Market Overview and Core Challenges
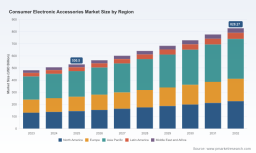
The worldwide consumer electronic accessories market has demonstrated resilient growth, expanding from 482.17 billion USD in 2023 to approximately 530.5 billion USD in 2025. This trajectory reflects a compound annual growth rate of 6.57 percent through 2032, positioning the sector to reach 828.27 billion USD by the end of the forecast period. Such expansion is not merely a function of population growth or rising disposable income; it is structurally tied to the deepening integration of accessories into primary device ecosystems. As smartphones, tablets, laptops, and personal audio devices become longer-lived capital investments, consumers and enterprises increasingly allocate spend toward protection, power management, connectivity, and audio enhancement. The sheer scale of demand, however, masks underlying friction points that will define competitive outcomes over the next several years.
One foundational challenge lies in the shifting balance between ecosystem lock-in and cross-platform compatibility. Accessories have historically benefited from brand-specific optimization, where proprietary connectors, magnetic alignment systems, and software-tuned audio profiles create repeat purchase behavior. At the same time, regulatory pressure and consumer fatigue around walled gardens are accelerating interoperability mandates and universal charging standards. Companies that rely exclusively on closed-loop accessory strategies face margin compression as third-party alternatives mature in performance and aesthetics, while those that invest in certified compatibility, adapter ecosystems, and software-adjacent features are finding new room to differentiate. The market is thus entering a phase where technical parity is increasingly common, and the real contest shifts to trust, lifecycle durability, and ecosystem integration.
A second challenge is the reconfiguration of supply chain geography and its impact on cost predictability. For years, concentrated manufacturing hubs provided scale efficiencies, but tariff adjustments, compliance complexity, and geopolitical risk have prompted importers to diversify sourcing. This diversification improves resilience but also fragments volume commitments, raises coordination costs, and temporarily disrupts the price advantage that low-cost manufacturing once delivered. Forward-looking operators are responding by blending regional assembly, qualifying alternative component suppliers, and redesigning accessories for modular sourcing rather than single-origin fabrication. Those that treat supply chain flexibility as a design parameter, rather than a back-office procurement issue, are better positioned to stabilize pricing and protect gross margins.
Worldwide E-commerce of Consumer Electronics Products Market
A third challenge is intensifying compliance and sustainability reporting. Electronic accessories are increasingly subject to product safety certification updates, substance restrictions, and material traceability expectations. The operational burden is no longer limited to final assembly; it extends into component documentation, eFiling processes, and product-level transparency. Firms that treat compliance as a reactive checkpoint often encounter shipment delays and re-certification costs, whereas those that embed documentation workflows and material data collection into product development cycles reduce time-to-market risk and create a defensible compliance posture. In this environment, the ability to evidence conformity and sustainability claims is becoming a commercial asset, not just a regulatory requirement.
Key Drivers of Market Change
Several interconnected forces are shaping the direction of the market. The most immediate is the rapid maturation of charging and power management technology. Gallium nitride and related wide-bandgap semiconductor materials have enabled chargers and power banks that are smaller, run cooler, and support higher wattage outputs without a proportional increase in size or heat. This shift is changing consumer expectations: portable power is no longer an afterthought but a primary purchase criterion for travelers, remote workers, and mobile-first users. The growth of fast-charging protocols and the gradual alignment of interoperability standards are also reducing the penalty of using non-proprietary accessories, which expands the addressable market for multi-brand compatible solutions while raising the performance bar for entrants.
Policy and regulatory dynamics are exerting a second, equally powerful influence. Product safety certification processes are becoming more digitized and stringent, with mandatory electronic filing of compliance certificates for consumer products including electronic accessories. These changes increase the administrative precision required from importers and manufacturers, especially those selling across multiple jurisdictions. At the same time, regional sustainability frameworks are advancing material-level transparency requirements that will affect electronics accessories, prompting companies to track substances, recovery pathways, and lifecycle information with greater rigor. For market participants, this means compliance capability is increasingly part of the product strategy, influencing component selection, supplier qualification, and packaging decisions well before launch.
PW Consulting
Consumer behavior is evolving in ways that reinforce accessory spend even as primary device upgrade cycles lengthen. Users are retaining phones and tablets for longer periods, which paradoxically increases demand for protective cases, screen protection, battery support, and audio upgrades that restore or extend the experience of aging hardware. There is also a pronounced preference shift toward products that combine durability with aesthetics; rugged protection is no longer sufficient on its own when consumers expect slim profiles, refined finishes, and brand-compatible design cues. In entertainment and gaming contexts, audio accessories are becoming more specialized, with users seeking improved comfort, directional sound characteristics, and microphone performance that supports both leisure and communication use cases. These behavioral trends reward companies that can deliver accessory solutions tuned to specific usage scenarios rather than generic, one-size product lines.
Supply chain and cost structure changes are reshaping where and how accessories are produced. Regional sourcing patterns have shifted markedly, with certain Southeast Asian manufacturing centers now supplying a larger share of U.S. consumer electronics imports by value than traditional sources. This transition reflects a blend of cost optimization, diversification strategy, and proximity considerations for specific components and assembly steps. At the same time, tariff adjustments on selected electronic inputs and continuing trade policy variability have increased landed cost uncertainty for some categories. The practical effect is that companies with diversified sourcing, multi-region assembly capability, and clear visibility into component-level cost exposure are gaining an operational advantage. Accessory design that anticipates component substitution and regional manufacturing flexibility is becoming a competitive differentiator as much as a cost strategy.
Competitive Landscape and Leading Strategies
The competitive field is wide and increasingly layered, ranging from ecosystem-anchored brands to specialized third-party players and value-oriented multi-brand suppliers. Apple exemplifies ecosystem integration, with accessories designed to align tightly with proprietary charging, magnetic alignment, and device-specific compatibility. This approach creates strong brand affinity and repeat purchase behavior among users already committed to the platform, and it allows the company to bundle accessory value into the broader device experience. The strategic implication is clear: ecosystem alignment can command premium positioning, but it also concentrates risk if consumer adoption of third-party alternatives accelerates under interoperability pressure.
Samsung and Sony illustrate complementary approaches within large device ecosystems. Samsung extends its device relationship through audio, protective cases, power banks, and fast-charging accessories that are optimized for its smartphone and tablet lineup, reinforcing ecosystem retention while maintaining broad retail visibility. Sony focuses more narrowly on premium audio accessories, leveraging brand strength in sound and consumer electronics to compete on performance perception and user experience rather than ecosystem bundling. Both strategies show that scale and brand recognition can be leveraged either broadly across categories or deeply within a specialty segment, depending on where the company wants to own the value proposition.
Charging and power specialists such as Anker and UGREEN highlight the potency of multi-brand compatibility combined with performance and design leadership. By focusing on chargers, cables, power banks, hubs, and docking solutions that work across major device brands, these companies address the growing consumer desire for versatile, travel-friendly power solutions without being tied to a single device maker. Their recent product introductions around high-capacity fast-charging models and expanding hub and cable portfolios reflect a broader industry move toward compact, high-output power products that serve hybrid work, travel, and multi-device environments. Their strategic advantage lies in solving a universal pain point—power access across devices—while maintaining flexibility to adapt to changing connector standards and protocol requirements.
Protective and lifestyle-oriented accessory brands, including Belkin, Spigen, OtterBox, and Baseus, demonstrate the importance of positioning around specific consumer expectations. Belkin emphasizes compatibility with widely adopted charging and connectivity standards and maintains strong retail and accessory categories that pair protection with charging solutions. Spigen and OtterBox compete on durability, fit, and visual style, targeting users who prioritize physical protection without sacrificing design appeal. Baseus broadens reach through value-oriented accessories that emphasize compatibility and affordability across a wide device base. The common thread among these players is that protection and daily-use accessories are increasingly judged on a combination of reliability, aesthetics, and compatibility rather than on ruggedness alone.
The market is evolving along two simultaneous tracks. On one track, larger device and audio brands continue to use accessories as retention and experience-enhancement tools, reinforcing integrated ecosystems and cross-selling opportunities. On the other, specialized third-party players are gaining share by offering cross-compatible performance, faster innovation cycles, and category depth in charging, audio, and protection. This dynamic is encouraging both consolidation among retailers and distributors seeking broader assortment efficiency and fragmentation at the product level, where niche use cases create room for focused innovation. New entrants that can demonstrate superior materials, clearer compatibility, or stronger user-experience design are finding pathways into the market, especially where legacy offerings lag in compactness, heat management, or multi-device utility.
Future Trends to Watch
Over the next three to five years, the market is likely to be shaped by three converging trends. The first is the continued normalization of compact high-performance power solutions as a baseline expectation rather than a premium feature. As faster charging, improved thermal management, and multi-port utility become more common, consumers will increasingly expect power accessories that are both travel-ready and capable of supporting multiple device types. Commercial opportunities will accrue to companies that can deliver these capabilities in slim form factors while maintaining reliability and safety documentation that meets evolving import requirements.
The second trend is deeper compatibility and interoperability, supported by consumer demand and regulatory direction. Accessories that rely on universal charging approaches, adaptable mounting or alignment systems, and clear cross-device performance will gain relevance as users reduce their tolerance for fragmented standards. This creates opportunities for brands and private-label suppliers to build portfolios around compatibility, modular adapters, and product lines that can pivot more easily when connector or protocol preferences shift. The risk for product strategies that assume long-lived proprietary advantage is rising, especially where compliance and interoperability expectations continue to tighten.
Power Tool Accessories Market
The third trend is sustainability and traceability becoming part of the purchasing and sourcing calculus. Material-level reporting, certification digitization, and growing buyer sensitivity to end-of-life and component transparency are likely to influence assortment decisions and supplier selection. Companies that can substantiate material claims, manage documentation efficiently, and design for easier recovery or component substitution will be better positioned to navigate compliance and to meet procurement requirements in more demanding channels. The uncertainty here lies in the pace and scope of regulatory implementation across regions, which may require flexible reporting and material data capabilities rather than one-time certification efforts.
Actionable Guidance for Decision-Makers
For manufacturers and product developers, the priority is to design accessory portfolios around compatibility, thermal and size performance, and supply chain modularity. Treating compliance documentation, material traceability, and alternative sourcing as integral to product architecture reduces launch risk and supports faster adaptation to standard changes. Teams should also assess which accessory categories are best positioned for ecosystem-aligned premium offerings versus cross-brand compatible volume plays, and allocate innovation resources accordingly.
For investors and strategic planners, the clearest value creation is likely to come from companies that combine multi-device compatibility with credible performance in power, protection, or audio, and that demonstrate disciplined compliance and sourcing exposure management. Observers should track category-level momentum in compact fast-charging products, audio specialization, and durability-plus-design protective accessories, while monitoring how import compliance and tariff variability influence margin structures and sourcing shifts. Diversification of revenue across compatible accessories and ecosystem-linked categories can reduce dependency on any single device cycle.
For procurement and channel leaders, the focus should be on supplier resilience, clear compatibility claims, and documented compliance readiness. Supplier selection criteria that include regional sourcing flexibility, eFiling and certification process maturity, and product-level transparency will help minimize disruption and protect assortment continuity. Evaluating accessory partnerships through the lens of lifecycle durability, documentation capability, and multi-device utility will support more durable category performance.
For detailed segmentation data, regional dynamics, and tailored scenario analysis, readers may refer to the full PW Consulting research report on the worldwide consumer electronic accessories market, which expands on the trends and strategic considerations outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Electronic Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


