



Mental Health Counseling Service Market: Why 8.12% CAGR Changes Everything

Navigating the Mental Health Counseling Service Market: Strategic Trends and Commercial Opportunities
Market Snapshot: Scale, Growth, and Structural Realities
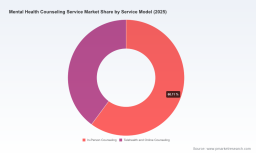
The global mental health counseling service market has entered a period of sustained expansion, driven by shifting societal attitudes, institutional adoption, and systemic healthcare pressures. Valued at approximately $10.2 billion in 2020, the market crossed $14.8 billion by 2024 and reached $16.5 billion in 2025. Forward projections indicate continued momentum, with revenue expected to approach $17.8 billion in 2026, $20.7 billion by 2028, and $28.5 billion by 2032. This trajectory reflects a compound annual growth rate of 8.12 percent, signaling that demand is not cyclical but structural. The expansion is broad-based, spanning multiple delivery formats, demographic segments, and geographic regions. However, growth alone does not guarantee commercial viability, and the market’s underlying architecture reveals several inflection points that will shape competitive outcomes over the next five years.
One of the most defining characteristics of the sector is its fragmented nature. The top three players collectively account for only 8.5 percent of total revenue, while the top five hold 12.2 percent. This dispersion suggests a market that remains highly accessible to regional providers, specialized practices, and technology-enabled entrants, rather than one dominated by a single platform or national chain. At the same time, fragmentation masks intense operational pressure. Practitioners, clinics, and digital care networks are all wrestling with workforce scarcity, reimbursement variability, and the logistical complexity of scaling consistent care quality across channels. For decision-makers evaluating market entry, partnership, or investment, the macro narrative is clear: demand is robust, but execution risk is elevated.
Several structural challenges are currently reshaping the industry’s trajectory. First, the workforce gap remains a binding constraint on capacity. Even as reimbursement frameworks and public awareness expand, the availability of licensed counselors, therapists, and psychiatric support staff has not kept pace with service demand. This imbalance affects wait times, clinician burnout, and the economics of care delivery, particularly in regions where recruitment and retention are already difficult. Second, the sustainability of insurance reimbursement and public funding continues to create uncertainty. Shifts in coverage policies, grant allocations, and payment schedules introduce volatility for providers who rely on a mix of commercial, public, and out-of-pocket revenue. Third, the market is navigating a delivery-model transition that is still maturing. While digital and remote counseling has moved from a supplementary option to a core channel, many organizations are still aligning operational workflows, clinical protocols, and customer experience standards across both physical and virtual settings. These factors together create a market that rewards scale, efficiency, and differentiated service design, while penalizing fragmented or operationally heavy providers.
PW Consulting Information & Electronics Research Center
Key Drivers: Technology, Policy, Demand, and Cost Architecture
The expansion of mental health counseling services is not occurring in isolation. It reflects converging forces across technology, regulation, consumer behavior, and cost structures. Understanding how these forces interact is essential for identifying where durable advantage can be built.
Technology innovation is fundamentally altering how counseling services are discovered, delivered, and scaled. Digital platforms have reduced friction in patient access, enabling text-based, audio, and video-based care across time zones and schedules. More importantly, technology is becoming embedded in clinical operations. Scheduling automation, matching algorithms, outcome tracking, and asynchronous communication tools are improving throughput and patient engagement while reducing administrative burden. The next wave of differentiation is likely to come from systems that combine clinical quality with operational efficiency: platforms that can connect patients to appropriate clinicians more quickly, retain them through structured care pathways, and capture outcome data that supports both clinical and commercial decisions. Technology-enabled providers that can demonstrate measurable engagement and continuity of care are gaining an advantage in both direct-to-consumer and enterprise contexts.
Policy and regulatory developments are simultaneously shaping the incentives that underpin service delivery. In the near term, reimbursement frameworks for outpatient psychological services are being adjusted, with modest updates to payment rates increasing the commercial attractiveness of insured counseling pathways. At the same time, legislative activity is focused on improving access and reimbursement parity for a broader set of provider types, including mental health counselors, marriage and family therapists, and clinical social workers. These policy shifts matter because they influence who can be paid, at what rate, and through which channels. In parallel, telehealth policy remains a central enabler for behavioral health delivery, with continued support for access-oriented remote care. However, the regulatory environment is not uniformly favorable across all programs and geographies. Some public grant and funding mechanisms have contracted, placing additional pressure on community-based providers and smaller organizations that depend on discretionary support. As a result, the policy landscape is creating both tailwinds and headwinds, rewarding organizations that can adapt to reimbursement complexity and diversify funding sources.
On the demand side, the most significant shift is the broadening normalization of mental health care as a routine component of personal wellness and organizational health strategy. Consumers are no longer treating counseling as an emergency-only service; they are seeking ongoing support for stress, relationship challenges, workplace burnout, and broader emotional well-being. Employers and institutions are increasingly incorporating mental health benefits into broader employee value propositions, recognizing that access to counseling and therapy influences retention, productivity, and overall workforce stability. This demand evolution is expanding the total addressable market beyond traditional clinical referral pathways and encouraging providers to design services that are easier to access, faster to start, and more aligned with varied use cases. The commercial implication is that patient acquisition, retention, and engagement are becoming as important as clinical capability alone.
Cost structure dynamics are also changing. Labor is the dominant operating expense in counseling services, and workforce scarcity has a direct impact on pricing power, margin stability, and scalability. Providers that can improve clinician productivity without compromising care quality—through better caseload design, integrated admin support, or hybrid delivery models—are better positioned to manage this pressure. At the same time, reimbursement and funding variability push organizations toward more balanced revenue mixes. Those relying heavily on a single payer type or grant program face greater exposure to policy shifts. The most resilient operators are increasingly building workflows that can serve insured, self-pay, and employer-sponsored populations with flexible care pathways while keeping fixed costs disciplined. In this environment, operational design is becoming a competitive lever, not just a back-office function.
Competitive Landscape and Leading Strategies
The competitive field in mental health counseling services reflects a wide spectrum of business models, from clinician networks anchored in physical clinics to digital-first platforms serving direct consumers and employer-sponsored markets. What distinguishes leaders is not simply the choice of channel, but the clarity of their value proposition and the consistency with which they execute it at scale.
Intellectual Disabilities Service Market
Large behavioral health organizations that operate across both outpatient clinics and telehealth are building strength through breadth of access and integrated care offerings. By combining therapy, psychiatry, and counseling within a single network, these players can serve a wider range of clinical needs and manage patient pathways across levels of intensity. Their advantage often lies in clinician recruitment capacity, geographic coverage, and the ability to support both insured and direct-to-consumer demand with a unified operational backbone. Where they succeed, they reduce fragmentation for patients and create a more seamless experience across care settings.
Digital counseling and telehealth platforms have pursued a different strategic path, emphasizing convenience, lower barriers to entry, and scalable service design. Some have grown directly with consumers by offering asynchronous messaging, video sessions, and flexible subscription models. Others have expanded their role within employer and health plan channels by positioning mental health care as part of a broader benefits ecosystem. The key differentiator for these platforms is typically access speed, user experience, and the ability to match patients with appropriate clinicians quickly. In a crowded digital care environment, platforms that can demonstrate high engagement, retention, and perceived quality have a stronger foundation for sustainable growth than those competing primarily on price.
A third strategic orientation is emerging among providers that combine in-person accessibility with online extensions and large clinician networks. These organizations aim to capture demand from patients who prefer face-to-face care but still want the convenience of online scheduling, flexible appointment availability, and continuity with the same provider when needed. Their positioning often emphasizes short time-to-appointment, localized access, and caregiver breadth. This model is especially relevant in markets where in-person trust remains important, but digital convenience is now an expected baseline rather than a premium feature.
A related area of strategic differentiation is the integration of digital self-care tools, meditation, and structured mental wellness content alongside counseling and therapy. This approach broadens the service ladder, allowing organizations to serve users at different levels of need and intensity. For employers and health-focused buyers, bundled wellness-plus-care offerings can be attractive because they address prevention and ongoing mental fitness in addition to clinical intervention. The commercial logic here is retention and ecosystem value: users who engage with multiple touchpoints are more likely to remain within a platform and benefit from a more continuous care relationship.
Employer-sponsored mental health benefits represent a distinct competitive space. Several providers have built their models around care navigation, personalized matching, and access to therapy or counseling through organizational partnerships. In this context, success depends less on direct consumer marketing and more on demonstrating measurable access, usage, and outcomes that employers and benefits administrators can trust. Providers that can translate clinical services into a clear organizational value proposition—lower barriers to care, improved employee experience, and structured support—are gaining traction in the enterprise segment. This channel also offers more predictable demand flows when contracts and utilization management are well designed.
Recent market activity illustrates how these strategies are evolving in practice. Strategic partnerships are being used to extend clinical depth and care coordination, particularly in areas such as psychiatric evaluation and medication management. Facility expansion efforts are reinforcing in-person capacity in specific regions, signaling that digital access does not eliminate the need for localized crisis and rehabilitation services. Meanwhile, educational and workforce programs are beginning to address the clinician supply pipeline directly, including apprenticeship-style models designed to create new pathways into mental health counseling. Across these developments, the broader pattern is one of hybridization: organizations are combining delivery formats, clinical disciplines, and partnership structures to build more resilient service networks rather than relying on a single channel or business model.
The competitive landscape is therefore moving in two directions at once. On one hand, scale players are working to consolidate access, expand clinician pools, and integrate service lines. On the other, specialized and digitally native providers continue to enter with focused value propositions around convenience, employer coverage, or particular patient populations. The market’s low concentration leaves room for both dynamics, but it also raises the stakes for differentiation. Providers that cannot clearly define their access model, reimbursement strategy, and clinician operating model will likely struggle to convert growth into durable margin.
Business Management Consulting Service Market
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to define the next phase of market development and create distinct commercial opportunities. First, the market will continue its shift toward hybrid care delivery, with in-person and virtual counseling increasingly treated as complementary rather than competing models. Providers that can move patients smoothly across channels, maintain clinical continuity, and align staffing to demand fluctuations will capture more efficient utilization and stronger patient retention. The commercial opportunity lies in designing end-to-end experience models that make access simple, reduce drop-off between intake and first appointment, and support ongoing care without forcing patients into a single modality.
Second, the workforce constraint will remain central, pushing the industry toward new talent models and productivity-focused operating designs. This includes more structured training pathways, apprenticeship and supervised practice programs, and workflow innovations that allow clinicians to focus more on direct care and less on administrative friction. Organizations that invest in clinician retention, well-designed caseloads, and supportive practice infrastructure will have an advantage in both quality and scale. The opportunity here is not simply hiring more clinicians, but building a more durable care workforce and matching supply to demand in a more intelligent way.
Third, reimbursement and access policy will continue to shape where value accrues. Modest payment improvements and legislative efforts to expand eligible provider reimbursement can improve the economics of insured counseling services, while funding volatility in certain community programs may intensify pressure on smaller providers. As a result, companies that can navigate payer diversity, strengthen billing and contracting capabilities, and maintain flexible funding options will be better positioned to stabilize revenue. The risk is that organizations heavily dependent on a narrow set of funding sources face disproportionate disruption if policy or grant priorities shift further.
These trends point to a market in which access, clinical quality, and operational discipline will increasingly determine who thrives. Commercial winners are likely to be those that treat mental health counseling not as a standalone service line but as an integrated part of a broader care and wellness ecosystem, with clear pathways for patient acquisition, continuity, and outcome measurement. At the same time, uncertainty remains around labor availability, reimbursement consistency, and funding levels in public programs. Decision-makers should plan for a market that is expanding, but also one where execution quality and adaptability will separate durable players from short-lived growth stories.
Strategic Recommendations for Decision-Makers
For executives, investors, and procurement leaders, the current market environment calls for clarity of role and discipline in execution. Three strategic priorities are especially relevant.
- For organizations building or scaling counseling services, prioritize hybrid delivery design and clinician operating models before chasing raw demand. Access speed, continuity across channels, and provider productivity will determine whether growth translates into sustainable economics.
- For investors and capital allocators, assess business models against reimbursement exposure, workforce scalability, and retention dynamics. Platforms and provider networks with diversified revenue streams, strong engagement metrics, and defensible operational advantages are better positioned than those dependent on a single channel or funding source.
- For employers, health plans, and institutional buyers, focus on access reliability and care navigation when evaluating mental health benefits and vendor partnerships. The most valuable partnerships are those that reduce friction to care, support a range of clinical needs, and provide visibility into utilization and follow-through rather than offering only broad access claims.
These decisions are best informed by detailed segmentation data, competitive benchmarking, and scenario analysis tailored to specific operating contexts. Broad market direction is only the starting point; the commercially relevant questions lie in segment economics, channel mix, payer dynamics, and the operational levers that determine margin under different demand conditions. Market participants who obtain structured, granular intelligence early can calibrate expansion plans, partnership choices, and service design with more confidence, while those relying on aggregate trends alone risk misjudging where opportunity and exposure are concentrated.
For detailed analysis of this topic, please visit the official page: Mental Health Counseling Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


