



Screening Services Market: Why 8.12% CAGR and $11B Forecast Change Everything

The Worldwide Job Screening Services Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global job screening services market has demonstrated sustained expansion over the past half decade, moving from an estimated $4.45 billion in 2020 to $6.39 billion in 2025. This trajectory reflects a compound annual growth rate of 8.12 percent, with revenue projections scaling toward $11.03 billion by 2032. The growth is not merely a function of headline hiring volumes; it signals a structural recalibration of how organizations approach talent acquisition, risk management, and regulatory compliance. As hiring cycles accelerate and workforce models grow more distributed, screening has shifted from a periodic administrative check to a continuous, data-intensive function embedded in the employee lifecycle.
Beneath the aggregate figures, three interconnected challenges are reshaping how market participants operate and compete. First, regulatory fragmentation continues to complicate compliance at scale. Fair chance and ban-the-box legislation has expanded across additional states and municipalities, requiring employers to postpone criminal history inquiries until after a conditional offer and mandating precise written disclosures for adverse actions. Simultaneously, new state-level provisions, such as the automatic sealing of certain misdemeanors and older convictions, narrow the scope of information available in standard employment background checks. Organizations must now navigate a mosaic of jurisdictional rules while maintaining consistent hiring standards, a balance that strains both internal HR teams and external screening vendors.
Second, cost pressures on verification infrastructure are intensifying. Third-party vendor fees for court records, employment and education verifications, and supplemental services have continued to rise through 2025 and into 2026, elevating operational costs for both screening providers and their clients. These increases are not uniform across data sources or geographies, creating uneven margin dynamics and prompting renegotiation of service-level expectations. Companies that rely on fragmented, manual procurement of verification data are finding it harder to predict total cost of ownership, while providers must decide whether to absorb cost increases, pass them through, or restructure service bundles to preserve value.
Third, the regulatory environment around automated decision-making and data privacy is adding a new layer of scrutiny. California’s CCPA regulations, effective January 1, 2026, require privacy risk assessments for automated decision-making technology used in employment contexts that present significant privacy risks. This development pushes employers and vendors alike to document how algorithms influence candidate outcomes, how data is retained, and how individuals can challenge automated results. The broader implication is clear: screening is no longer evaluated solely on speed and coverage, but also on explainability, consent management, and audit readiness. Organizations that treat these requirements as afterthoughts face mounting exposure, while those that build compliance into their workflows gain a durable advantage in regulated industries and multi-jurisdiction deployments.
Key Drivers Shaping Market Dynamics
Technology innovation is redefining the speed, granularity, and continuity of screening. API-first architectures and automated adjudication have become baseline expectations for high-volume hiring, particularly in sectors where candidate throughput must align with rapid operational scaling. Real-time and continuous monitoring solutions are extending screening beyond the point of hire, enabling organizations to track changes in criminal records, licensure status, and identity signals over time. The acquisition of a provider of AI-driven real-time screening and continuous monitoring by a private equity sponsor highlights how capital is flowing toward platforms that can reduce manual review, improve consistency, and support ongoing risk assessment rather than one-time checks. These capabilities are especially valuable where hiring is distributed across multiple locations or where roles involve recurring access to sensitive systems and data.
Policy and regulatory evolution is simultaneously acting as both a constraint and a catalyst. The CFPB’s interpretive rule clarifying that the FCRA generally preempts conflicting state laws in matters addressed by the statute introduces a degree of federal clarity into a historically fragmented compliance landscape. For employers and vendors, this reduces the risk of contradictory state obligations in areas already governed by the FCRA, though it does not eliminate the need to manage state-specific fair chance requirements, consent processes, and adverse action procedures. Industry guidance published in late 2025 emphasized the importance of revisiting screening policies for 2026, covering ban-the-box expansions, consent requirements, adverse action workflows, and continuous monitoring practices. Compliance is increasingly treated as a design question: systems must capture appropriate authorizations, sequence checks in the correct order, and produce auditable records that withstand regulatory review.
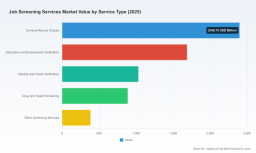
Demand-side behavior is shifting as organizations connect screening more tightly to quality of hire, retention, and enterprise risk. The IT and telecom sector, alongside BFSI and healthcare, continues to represent a substantial share of screening activity, reflecting the sensitivity of roles in these verticals and the pace at which they hire. In technology and gig-economy contexts, volume, speed, and integration with applicant tracking systems are paramount, while in regulated industries, depth of verification and defensible adjudication take precedence. Employers are also increasingly viewing screening as part of a broader trust-and-safety strategy rather than a standalone HR task. This mindset supports demand for bundled services that combine identity verification, criminal checks, education and employment verification, and health or drug screening where relevant, reducing the friction of coordinating multiple vendors and improving the candidate experience through unified workflows.
Cost structure and supply chain dynamics are pushing the market toward integration and automation. As court record and verification fees rise, providers and clients are reassessing how to consolidate touchpoints, reduce manual handoffs, and standardize data ingestion. Unified ordering models that pair background checks with occupational health services, along with deeper ATS integrations and candidate workflow optimizations, are gaining traction because they lower administrative burden and improve completion rates. At the same time, the labor and data economics of verification are prompting a focus on selectivity: not every role requires the same depth of check, and tiered or risk-based approaches can align scope with actual exposure. The practical effect is a market that is moving from uniform, one-size-fits-all packages toward configurable, role-sensitive screening programs that balance coverage, cost, and compliance.
Security Screening Market
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established providers and a dynamic perimeter of technology-forward entrants and specialized firms. Concentration among the largest participants remains meaningful, with the top three holding roughly 41.5 percent and the top five approaching 54.2 percent of market revenue. This structure reflects the advantages of scale in global data access, compliance infrastructure, and enterprise sales, while also leaving room for differentiation through product design, integration depth, and vertical focus. The leading incumbents compete on breadth of coverage, regulatory expertise, and the ability to serve large, multi-national workforces with consistent standards across jurisdictions.
First Advantage and HireRight illustrate two complementary formulations of scale-led strategy. First Advantage emphasizes comprehensive global employment screening across 200-plus countries, combining criminal background checks, identity verification, drug screening, and verifications with advanced risk scoring and compliance tooling for large enterprises. Its recent compliance-focused analysis addressed 2026 FCRA trends, identity fraud mitigation, and CFPB interpretive rules on preemption, signaling a strategy that ties product capability to forward-looking regulatory interpretation. HireRight similarly operates with extensive international coverage and a strong orientation toward regulated industries, offering employment and education verifications alongside compliance solutions for enterprise clients. Its acquisition of ClearChecks expanded its reach to small and medium-sized businesses with technology-based screening services, illustrating a move to capture segments that require lighter-touch, automated offerings while preserving enterprise-grade capabilities for larger accounts.
Worldwide Job Search Recruitment Services Market
The technology-driven segment is shaping competition on speed, integration, and user experience. Checkr has built a reputation around API-first, high-volume screening with automated adjudication and strong alignment to tech, gig-economy, and retail use cases. GoodHire, now part of Checkr, targets small to mid-sized businesses with a user-friendly, FCRA-compliant platform and customizable packages, showing how brand and usability can differentiate even within a consolidated market. Accurate Background combines background screening with drug testing and occupational health services, while expanding international coverage in Asia Pacific and Europe, a reminder that service bundling and geographic extension remain viable ways to create value. Universal Background Screening has reinforced its position through ATS integrations, unified ordering with occupational health, and compliance-focused workflows, reflecting a broader industry push to reduce friction in candidate and HR workflows.
Compliance and governance specialists are carving out a distinct competitive lane. Cisive emphasizes compliance, policy support, social media screening guidelines, and FCRA-aligned processes, and its late-2025 policy guidance on reviewing screening policies for 2026 underscores the importance of proactive governance. Mitratech’s AssureHire platform serves mid-market and enterprise clients with deep compliance, audit trails, and continuous screening capabilities, appealing to organizations that need traceability and ongoing monitoring rather than point-in-time checks. DISA Global Solutions focuses on background screening, drug testing, and compliance services, with explicit attention to AI risks in HR screening, a topic that is gaining prominence as automated tools become more prevalent. Meanwhile, Sterling Check and Cisisive continue to reinforce identity, pre-hire, and post-hire monitoring capabilities within broader service portfolios.
The competitive landscape is evolving along three vectors. Consolidation is accelerating as larger platforms acquire technology and customer bases to broaden segment coverage and strengthen automation capabilities. Differentiation is intensifying around integration quality, regulatory interpretation, and the ability to tailor screening depth to role-specific risk. New entrants and private capital are drawn to continuous monitoring, identity fraud detection, and decision intelligence, areas where software margins and recurring engagement models can complement traditional verification economics. The net result is a market in which scale provides reach and compliance depth, but product design, integration, and governance discipline increasingly determine who wins in specific verticals and customer segments.
PW Consulting
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be defined by the maturation of continuous and risk-based screening. Point-in-time checks will remain essential, but organizations will increasingly pair them with ongoing monitoring for roles that carry elevated access or responsibility. This shift creates commercial opportunities for platforms that can deliver timely alerts, prioritized case management, and clear escalation paths without overwhelming HR and security teams with noise. Providers that can calibrate monitoring frequency and scope to actual risk, while maintaining defensible audit trails, will be well positioned to capture recurring engagement and expand share of wallet within existing accounts.
A second trend is the convergence of compliance, privacy, and decision intelligence. As automated decision-making tools become more embedded in screening workflows, employers and vendors will need to demonstrate how decisions are made, how data is used, and how candidates can contest outcomes. The requirement for privacy risk assessments in employment-related automated decision-making, together with evolving fair chance rules and interpretive guidance on federal preemption, will raise the bar for documentation and process design. Commercially, this favors organizations that invest early in explainable workflows, consent management, and policy engines that can adapt to jurisdictional changes without requiring wholesale rebuilds. It also creates advisory and enablement opportunities for partners that can help clients translate regulatory complexity into operational practice.
A third trend is the continued pressure on verification costs and the corresponding push toward integration and selectivity. Rising third-party fees for court records and verifications will encourage more consolidated procurement, deeper ATS and HRIS integrations, and tiered screening models that align scope with role risk. Bundled offerings that unite background checks with occupational health, identity verification, and drug screening where applicable will likely gain share by reducing vendor fragmentation and improving completion rates. At the same time, uncertainty remains. Regulatory direction can shift at the state and municipal level faster than platform roadmaps, and automated tools introduce new governance and bias considerations that require careful validation. Organizations that treat these uncertainties as design constraints rather than exceptional risks will be better prepared to scale confidently.
Strategic Recommendations for Decision Makers
For enterprise employers and HR leaders, the priority is to move from reactive, one-off screening to a governed, risk-tiered program. This means mapping role types to appropriate screening depth, standardizing consent and adverse action workflows, and embedding continuous monitoring where the risk profile justifies it. Integrating screening with applicant tracking and HR systems reduces administrative drag and improves candidate completion, while documented policy reviews help align practices with evolving fair chance and privacy requirements. Treat compliance and explainability as product features, not add-ons, and ensure that any automated adjudication is auditable and contestable.
For investors and strategic buyers, the most compelling value creation levers are automation, continuous monitoring, and international expansion in high-growth regions. Platforms that can demonstrate measurable reductions in manual review, faster time to decision, and defensible compliance records are better positioned to command premium valuations and cross-sell across segments. Due diligence should focus on data sourcing economics, jurisdictional coverage, integration depth, and the operational maturity of privacy and AI governance, because these factors will increasingly differentiate scalable platforms from point solutions as regulation tightens and cost pressures persist.
For procurement teams and mid-market buyers, the practical goal is to consolidate vendors without sacrificing flexibility or compliance rigor. Seek providers that offer configurable packages, clear audit trails, and integration with existing systems, and evaluate total cost of ownership across verification fees, workflow efficiency, and candidate experience rather than headline price alone. Continuous monitoring and occupational health bundling can be valuable where they fit the use case, but they should be assessed against actual risk exposure and operational capacity.
Given the pace of regulatory change, cost dynamics, and product consolidation, detailed segment-level intelligence is essential for timing decisions and prioritizing investments. More granular data on regional trajectories, service-type demand, vertical adoption patterns, and provider-level positioning can sharpen strategy and reduce execution risk. The complete analysis, including deeper segmentation and customized recommendations, is available in the full PW Consulting report on the Worldwide Job Screening Services Market.
For detailed analysis of this topic, please visit the official page: Worldwide Job Screening Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


