



Worldwide Nail Care Packaging Market Shaped by 5.5% CAGR and Glass Lead

Strategic Trends and Commercial Opportunities in the Worldwide Nail Care Packaging Market
Market Snapshot and Core Challenges
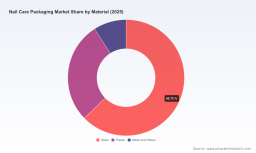
The global nail care packaging market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of $1,532.65 million in 2025. This growth trajectory reflects a compound annual growth rate of 5.48 percent projected through 2032, signaling steady demand despite broader macroeconomic volatility. The sector's foundation rests on a specialized ecosystem where material choices, regional production hubs, and product form factors dictate competitive positioning. Glass continues to dominate material preferences due to its premium aesthetics and barrier properties, while plastic formulations capture significant volume through cost efficiency and design flexibility. Product architecture remains heavily skewed toward bottles, which serve as the primary delivery mechanism, though caps, brushes, tubes, and jars collectively represent a substantial secondary segment that shapes user experience and brand differentiation.
Several structural headwinds are reshaping how manufacturers and brand owners approach capacity planning, material sourcing, and product development. The first challenge stems from escalating raw material volatility, particularly in resin markets where producer price indices have climbed sharply amid energy cost pressures and constrained supply chains. This inflation directly impacts plastic component pricing, forcing converters to navigate margin compression while maintaining competitive retail pricing. The second challenge emerges from an accelerating regulatory environment that demands fundamental redesigns of packaging architectures. Extended producer responsibility frameworks are gaining momentum across multiple jurisdictions, compelling manufacturers to internalize end-of-life management costs and adjust commercial models accordingly. The third challenge lies in balancing sustainability mandates with performance requirements. Nail care products demand precise dispensing mechanisms, chemical compatibility, and tamper evidence, which historically limited material substitution options. Companies now face the complex task of meeting recycled content targets and design-for-recycling criteria without compromising functionality or aesthetic appeal.
These intersecting pressures create a market at an inflection point. Stakeholders must reconcile cost discipline with compliance readiness, while simultaneously responding to evolving consumer expectations around sustainability and premiumization. The companies that successfully navigate this transition will be those that treat regulatory and material shifts not as isolated constraints but as catalysts for structural innovation across their packaging portfolios.
Key Drivers Reshaping the Market
Technological innovation continues to serve as a primary catalyst for market evolution, particularly in the realm of dispensing systems, closure mechanisms, and material engineering. Advanced brush geometries, precision dropper assemblies, and ergonomically optimized caps are redefining application consistency and user satisfaction. Suppliers are increasingly integrating smart manufacturing techniques, including precision molding and automated quality verification, to reduce defect rates and improve batch uniformity. These advancements matter because nail care products rely heavily on tactile and visual cues during application; even minor improvements in flow control or bristle alignment can translate into measurable brand loyalty gains. The trend toward hybrid formulations, including products that blend traditional color delivery with added functional benefits, further reinforces the need for packaging that supports stable ingredient interactions while maintaining clarity and structural integrity.
Policy and regulatory developments are simultaneously restructuring competitive dynamics by imposing new design and compliance obligations. Extended producer responsibility frameworks in several U.S. states are moving from legislative intent to operational requirements, with recycling rate disclosures and fee structures increasingly tied to material choice and packaging complexity. In parallel, the European Union's packaging and packaging waste regulation trajectory is steering manufacturers toward design-for-recycling standards and recycled content thresholds that directly affect cosmetic and nail care containers. These policy shifts are not merely compliance exercises; they influence upstream sourcing strategies, mold investment timelines, and collaboration models between brand owners and packaging suppliers. Companies that anticipate these requirements and build modular design capabilities into their development pipelines are better positioned to avoid retrofitting costs and supply disruptions later in the product lifecycle.
Nail Polish Market
Demand-side behavior is also undergoing a meaningful transformation, driven by a combination of premiumization, sustainability sensibility, and the expansion of professional and at-home nail care usage. Consumers increasingly associate packaging quality with product efficacy and brand credibility, which elevates the strategic importance of bottle clarity, labelability, and closure reliability. At the same time, the rise of hybrid care categories encourages manufacturers to consider packaging that communicates added benefits without complicating the user journey. On the supply chain side, cost structures are being recalibrated by resin price fluctuations, energy inputs, and logistics constraints. These pressures are prompting sourcing diversification, closer coordination between converters and raw material producers, and renewed evaluation of glass-versus-plastic trade-offs based on total cost of ownership rather than unit price alone. Recent trade activity and product introductions illustrate how these forces are converging, with suppliers showcasing material alternatives, refill-compatible configurations, and specialized dispensing components that respond to both performance and regulatory expectations.
Competitive Landscape and Leading Strategies
The market's competitive architecture is characterized by a mix of incumbent packaging specialists, global container manufacturers, and regional suppliers with focused nail care expertise. Concentration levels remain moderate, indicating that no single entity controls the majority of supply and that differentiation is largely achieved through design capability, material specialization, and service integration rather than sheer scale alone. Leading players have positioned themselves along distinct strategic axes, balancing premium aesthetics, sustainability readiness, dispensing innovation, and regional manufacturing proximity. This diversification allows brand owners to select partners based on product positioning, compliance requirements, and speed-to-market considerations.
Worldwide Nail Strips Market
Several companies illustrate the breadth of current strategic approaches. Global cosmetic packaging providers with strong glass and hybrid container capabilities emphasize complete solution offerings, combining bottle design, finish options, and compatibility testing to reduce development friction for nail care brands. European design-driven suppliers focus on customizable, eco-oriented constructions that align with regional regulatory expectations while maintaining premium visual appeal. Specialized glass and plastic container manufacturers prioritize safety, clarity, and aesthetic consistency, appealing to brands where product presentation and chemical stability are paramount. Suppliers centered on dispensing systems, closures, and brushes contribute differentiated value by improving application precision and user experience rather than competing solely on container volume. Meanwhile, manufacturers offering turnkey or private-label capabilities integrate formulation and packaging workflows, creating efficiencies for brands seeking streamlined go-to-market pathways.
The landscape is evolving through a combination of capability consolidation and niche specialization. Larger players are expanding their nail care portfolios through targeted investments in dispensing technology, sustainable material options, and regional production footprints that shorten lead times. At the same time, smaller and mid-sized suppliers are carving out positions by offering highly customizable glass solutions, specialized brush assemblies, or region-specific compliance support. New entrants and adjacent players are also testing the market by leveraging flexible manufacturing and design services to serve emerging brands that prioritize speed, distinctiveness, and sustainability credentials. This dynamic suggests that competition will increasingly hinge on the ability to deliver integrated solutions rather than standalone components, with success measured by how effectively a supplier can align material performance, regulatory readiness, and brand storytelling within a single packaging system.
PW Consulting
Future Outlook and Emerging Opportunities
Over the next three to five years, the market is likely to be shaped by the convergence of regulatory-driven design changes, material innovation, and continued premiumization. One prominent trend will be the broader adoption of recyclable and refill-compatible packaging architectures as extended producer responsibility obligations mature and recycled content expectations become more enforceable. This shift will create opportunities for suppliers that can standardize modular components, simplify material sorting, and demonstrate verifiable end-of-life pathways without sacrificing dispensing accuracy or product protection. Brands that proactively align their packaging roadmaps with these requirements will reduce future reformulation risk and strengthen shelf positioning in markets where sustainability claims are scrutinized.
A second trend will involve the acceleration of functional integration within packaging, including closures and brushes designed to support hybrid product types, precision dosing, and improved application control. As nail care categories expand beyond traditional color cosmetics into care-oriented and hybrid formulations, packaging will need to signal functionality while maintaining the tactile and visual attributes consumers associate with quality. Suppliers that invest in application-specific engineering and user testing will be better equipped to capture premium segments and support brand differentiation. A third trend relates to supply chain reconfiguration, as manufacturers seek to mitigate raw material volatility and compliance complexity through diversified sourcing, regional production, and closer collaboration with converters and resin suppliers. This reconfiguration may favor partners that offer transparency, flexible order structures, and predictable lead times.
These opportunities are not without risk. Material substitution can introduce compatibility challenges, especially when formulations evolve faster than packaging validation cycles. Regulatory timelines may diverge across regions, creating uneven compliance burdens and complicating global product rollouts. Additionally, if resin price pressures persist or recycling infrastructure lags behind policy goals, the economics of sustainable packaging transitions could tighten, rewarding only those players with strong cost control and technical validation capabilities. Strategic foresight will therefore matter as much as execution.
Strategic Implications for Decision-Makers
For packaging manufacturers and converters, the priority is to build modular design capability that can accommodate recycled content, design-for-recycling standards, and changing dispensing requirements without requiring complete toolchain overhauls. Investing in application testing, closure optimization, and glass-plastic integration strategies will help protect margins while meeting evolving brand demands. For investors, the most attractive exposure lies in suppliers that combine regulatory readiness with differentiated dispensing or material solutions, especially those serving premium and hybrid nail care segments where performance and aesthetics command pricing power. For procurement teams and brand owners, the focus should be on supplier partnerships that offer compliance transparency, stable material sourcing, and design flexibility, since these attributes reduce launch risk and support consistent product experience across markets.
Given the pace of regulatory change, material volatility, and product innovation, decision-makers benefit from access to detailed segmentation data, regional compliance mapping, and supplier capability assessments that go beyond high-level market sizing. Deeper Intelligence on volume splits, material transitions, competitive positioning, and scenario-based forecasts can sharpen capacity planning, sourcing decisions, and portfolio prioritization. For organizations seeking a comprehensive view of market structure, company strategies, and forward-looking dynamics, the full PW Consulting research report provides expanded segmentation detail and tailored analysis to support sector-specific planning.
For detailed analysis of this topic, please visit the official page: Worldwide Nail Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


