



Bovine Leather Goods Market: 4.25% CAGR Trajectory and Regional Power Shifts Exposed

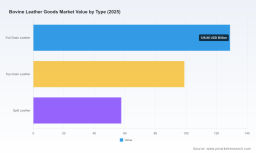
Bovine Leather Goods Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The bovine leather goods market has demonstrated resilient growth over the past half-decade, expanding from approximately $234.66 billion in 2020 to $285.5 billion in 2025. This trajectory reflects a compound annual growth rate of 4.25% through the forecast period extending to 2032, with projected revenues reaching $382.08 billion by the end of the outlook window. The market's expansion is not merely a function of population growth or inflation; it represents a structural shift in how bovine leather is positioned across premium, mid-tier, and specialized industrial applications. However, the growth path is neither linear nor without friction. Industry participants navigating this landscape must contend with a set of interconnected challenges that will define competitive positioning over the next several years.
Leather Market
One of the most pressing inflection points lies in the tension between raw material cost volatility and margin preservation. Hides prices have fluctuated in a narrow but persistent band, hovering around 57 to 59 US cents per pound in early 2026, while wholesale raw hides and skins in the United States have traded within a range of approximately $1.38 to $2.76 per kilogram. These fluctuations, though seemingly modest in percentage terms, compound across complex supply chains where tanning, finishing, and craftsmanship add significant value. Manufacturers operating with thin margins or rigid pricing contracts face residual exposure that can erode profitability even when end-market demand remains robust. The ability to hedge, negotiate long-term supply agreements, or vertically integrate upstream has become a differentiating capability rather than a optional efficiency play.
A second challenge centers on regulatory and sustainability expectations that are reshaping procurement criteria across both consumer and industrial buyer segments. The United States and European Union maintain strict environmental and animal welfare standards for bovine leather production and imports, and compliance is increasingly treated as a baseline requirement rather than a discretionary credential. Tariff structures on imported raw leather materials further complicate cost planning for manufacturers reliant on cross-border sourcing, introducing variability that can disrupt otherwise stable production economics. Companies that treat compliance as a reactive exercise risk facing supply disruptions, reputational friction, or lost contracts with buyers who now embed sustainability and traceability requirements directly into vendor selection frameworks.
A third structural tension involves the market's moderate concentration and the resulting fragmentation of competitive dynamics. With a combined share of roughly 18.5% held by the top three firms and approximately 24.4% by the top five, the industry remains broadly distributed across established luxury houses, specialized tanneries, and regional manufacturers. This dispersion fosters innovation and niche specialization but also means that no single entity exerts decisive pricing or supply control. The result is a market where scale advantages are real but not absolute, and where differentiation through craftsmanship, traceability, or application-specific engineering often matters more than pure volume. For decision-makers, this environment rewards clarity of positioning and penalizes undifferentiated competition.
Key Drivers of Market Change
Several interlocking forces are propelling the bovine leather goods market forward, each reinforcing the others in ways that create both opportunity and strategic urgency. Understanding these drivers is essential for aligning production capacity, sourcing strategy, and product development with where demand and regulatory momentum are actually heading.
Technological Innovation and Processing Breakthroughs
Advancements in tanning chemistry, finishing technologies, and grading consistency are reshaping what bovine leather can deliver across applications. Traditional vegetable and chrome tanning methods continue to anchor premium segments, but newer processes are enabling manufacturers to achieve more uniform surface quality, improved durability, and reduced environmental footprints without sacrificing the tactile and aesthetic qualities that buyers expect. These improvements matter because they expand the usable yield from each hide, lower rejection rates, and allow producers to serve demanding applications such as automotive interiors and high-wear footwear with greater confidence. The practical implication is straightforward: firms that invest in process control and finishing innovation can convert raw material volatility into a more predictable cost-per-output equation, while also meeting stricter performance specifications from commercial buyers.
Policy, Regulation, and Standards Evolution
Regulatory frameworks are not merely constraints; they are increasingly shaping the structure of competition. Environmental and animal welfare standards in major markets create a de facto barrier for producers who lack traceability systems, certified sourcing practices, or documented compliance records. At the same time, industry bodies and exhibition platforms are actively promoting sustainable bovine leather goods, signaling that sustainability is becoming a commercial asset rather than a compliance cost. Participation in major industry gatherings and exhibitions has become a channel for showcasing compliant, traceable, and performance-optimized leather goods to buyers who are actively filtering suppliers through sustainability criteria. For manufacturers and brands, the strategic question is no longer whether to engage with these standards but how to use them as a basis for differentiation in buyer negotiations and market positioning.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are evolving on both the consumer and commercial sides. In consumer markets, there is sustained appreciation for bovine leather goods that combine durability with craftsmanship, particularly in footwear, apparel accessories, and luxury-adjacent categories where material provenance and finish quality influence purchase decisions. In enterprise and industrial applications, buyers are prioritizing consistency, traceability, and lifecycle performance, especially in automotive interiors and furniture upholstery where material specifications are tied to brand promises and warranty exposure. This dual dynamic means that bovine leather is no longer competing solely on tradition or aesthetics; it is increasingly evaluated on measurable performance, supply reliability, and alignment with sustainability expectations. Brands and manufacturers that can articulate these value propositions with evidence are better positioned to defend pricing and secure long-term contracts.
Supply Chain and Cost Structure Dynamics
Supply chain reconfiguration is another significant driver. Tariff impacts on imported raw leather materials have introduced cost variability for manufacturers dependent on cross-border sourcing, prompting some firms to reassess supplier geography, inventory buffers, and contract structures. At the same time, raw material pricing remains sensitive to broader agricultural and livestock market conditions, meaning that even well-structured procurement strategies must accommodate periodic fluctuations. Companies are responding by diversifying supplier bases, strengthening relationships with certified tanneries, and in some cases exploring closer coordination with hide suppliers to improve visibility and reduce lead-time uncertainty. The firms that treat supply chain design as a strategic lever rather than a transactional function are gaining an edge in cost stability and delivery reliability, both of which are increasingly weighted in buyer selection.
Competitive Landscape and Leading Strategies
The competitive environment in the bovine leather goods market is defined by a mix of heritage craftsmanship, brand equity, and specialized manufacturing capability. The presence of large luxury groups alongside focused tanneries and regional manufacturers creates a landscape where multiple pathways to differentiation coexist. Understanding how leading players position themselves reveals where value is being captured and how the market is likely to evolve.
Strategic Positioning Among Leading Players
At the premium end, luxury houses such as Hermès International S.A. and Kering S.A. emphasize full-grain bovine and calf leathers, artisanal craftsmanship, and strong brand heritage. Their strategy centers on maintaining perceived scarcity, controlling the narrative around material quality, and using leather goods as anchor products within broader luxury portfolios. LVMH and Prada similarly leverage bovine leather across handbags, wallets, and travel goods, but with a stronger emphasis on volume coordination across brands and collections. These players benefit from brand-driven pricing power and direct consumer relationships, but they also face ongoing pressure to demonstrate sustainability credentials and supply transparency without diluting the exclusivity that underpins their pricing.
Specialized manufacturers and tanneries occupy a different strategic position. Horween Leather Company, for example, focuses on high-quality vegetable and chrome tanned bovine leathers for footwear, bags, wallets, and belts, relying on traditional methods that appeal to brands and consumers who value pedigree and consistency. Rancourt & Co., The Frye Company, Circa of America, Garrett Leather Corp, and Tanner Goods each serve distinct niches, from footwear and boots to accessories and supply-oriented manufacturing. Their advantages typically lie in application knowledge, production flexibility, and the ability to meet specific performance or aesthetic requirements that broader producers may not prioritize. In a market with moderate concentration, these specialized players can compete effectively by deepening relationships with brand partners and delivering reliable quality rather than competing solely on price.
PW Consulting Health Care Research Center
Market Evolution: Consolidation, Differentiation, and New Entrants
The market's moderate concentration suggests room for both consolidation and continued fragmentation, depending on segment and geography. In premium luxury, brand consolidation and portfolio coordination are likely to persist, as large groups seek to balance exclusivity with scale efficiencies across leather goods categories. In mid-tier and specialized manufacturing, the more probable trajectory is differentiation through capability: firms that can combine consistent quality, traceability, and application-specific engineering will capture preferential access to discerning buyers. New entrants and smaller specialized producers may find opportunity in niches where craftsmanship, limited runs, or sustainability credentials command premiums, though they will need to navigate raw material cost variability and compliance requirements carefully. Overall, the competitive dynamic favors players who can articulate a clear value proposition and execute reliably across sourcing, production, and delivery.
Leather Goods Market
Future Outlook and Emerging Trends
Looking ahead over the next three to five years, several trends are likely to shape how the bovine leather goods market evolves and where commercial opportunities emerge. These trends are not speculative abstractions; they are extensions of current pricing behavior, regulatory direction, and buyer expectations already visible in the market.
One prominent trend is the increasing integration of sustainability and traceability into procurement decisions across both consumer-facing and industrial segments. As environmental and animal welfare standards remain strict in major markets and as industry exhibitions continue to highlight sustainable bovine leather goods, buyers are likely to place greater weight on documented compliance, responsible sourcing, and process transparency. The commercial opportunity lies in building verifiable credentials that can be presented in sales cycles and vendor evaluations, turning sustainability from a cost center into a competitive asset. The associated risk is that firms without credible traceability or compliance infrastructure may find themselves increasingly excluded from preferred supplier lists, particularly in segments where brand reputation and regulatory exposure are high.
A second trend is the ongoing refinement of product performance and finish consistency through processing innovation. As tanning and finishing capabilities improve, bovine leather goods can better meet the demands of automotive interiors, footwear, and upholstery applications where durability, appearance retention, and uniformity are critical. This creates opportunities for manufacturers to expand into higher-specification segments and for brands to market leather goods with clearer performance promises. The risk here is that innovation requires investment and process discipline; companies that delay modernization may face yield inefficiencies and reduced competitiveness against more advanced producers.
A third trend involves continued supply chain recalibration in response to cost variability and trade dynamics. With raw hides prices fluctuating and tariff impacts affecting imported materials, firms are likely to pursue more diversified sourcing, stronger supplier partnerships, and greater inventory or contract flexibility. The opportunity is to reduce exposure to sudden cost shocks and improve delivery reliability, both of which strengthen buyer confidence. The risk is that over-concentration in any single sourcing geography or supplier relationship can leave a company vulnerable if conditions shift, making diversification and contingency planning essential rather than optional.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen process control, traceability, and supplier coordination so that raw material volatility can be managed more predictably. Investing in finishing consistency, grading reliability, and documented compliance will improve both margins and buyer confidence, particularly in segments where performance specifications and sustainability expectations are tightening. Building longer-term supplier relationships and diversifying sourcing where feasible can also reduce exposure to tariff and price fluctuations.
For investors, the most compelling opportunities lie in companies that combine clear differentiation with operational discipline. Luxury and heritage brands with strong demand and pricing power remain attractive, but scrutiny should extend to their sustainability readiness and supply transparency. Specialized manufacturers with application expertise, dependable quality, and flexible production may offer resilient exposure to multiple end-use segments, especially where they serve buyers who value reliability and specification compliance over lowest-cost sourcing.
For procurement and sourcing leaders, the strategic imperative is to evaluate suppliers against a broader set of criteria that includes traceability, consistency, and resilience alongside price. Engaging with suppliers who can demonstrate compliance, stable output, and transparent sourcing practices will reduce downstream risk and support brand-level commitments. Maintaining visibility into raw material pricing trends and regulatory developments will also improve negotiation positioning and inventory planning.
Detailed segmentation data, regional breakdowns, and customized scenario analysis can sharpen these decisions further. For teams that need granular revenue splits, application-specific growth patterns, and company-level benchmarking beyond the overview presented here, the full PW Consulting research report provides the deeper dataset and structured frameworks required to translate these market dynamics into precise action plans.
For detailed analysis of this topic, please visit the official page: Bovine Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


