



How Asia Pacific's 8.2B Lead and 6.15% CAGR Are Redefining the AC Motor Controllers Market

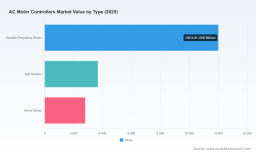
Worldwide AC Motor Controllers Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The global AC motor controllers market has matured into a critical enabler of industrial efficiency and electrification. Between 2020 and 2025, the sector expanded from approximately USD 13.7 billion to USD 18.5 billion, reflecting a compound annual growth rate of 6.15% through 2032, when it is projected to reach USD 28.1 billion. This trajectory is not merely incremental; it signals a structural shift where motor control infrastructure is moving from a maintenance-driven commodity to a strategic asset for energy management, process optimization, and automation.
Despite this robust expansion, the industry faces three interconnected challenges that will define competitive positioning in the coming years. First, supply chain fragmentation and component volatility are testing margin resilience. While wide-bandgap semiconductor pricing has shown periodic relief, other critical inputs such as copper-based PCB materials have experienced sharp cost escalations, forcing manufacturers to balance pricing power against volume commitments. Second, regulatory complexity is accelerating fragmentation across regional compliance frameworks. Safety and efficiency mandates are no longer optional; they dictate design architectures, certification pathways, and time-to-market. Firms that treat compliance as an afterthought face escalating rework costs and delayed commercialization. Third, the integration of advanced control algorithms with legacy infrastructure creates deployment friction. End users increasingly expect plug-and-play interoperability, yet many facilities operate mixed-vendor environments with varying communication protocols and cybersecurity baselines. Bridging this gap requires more than hardware performance; it demands ecosystem-level compatibility and lifecycle support.
These pressures are reshaping how value is captured. Companies that can standardize compliance, stabilize component sourcing, and simplify integration are gaining share, while those relying on fragmented product lines or reactive supply strategies are seeing margin compression. The market is no longer growing uniformly; growth is concentrating around application segments that deliver measurable energy savings, process reliability, and scalability.
Key Drivers Shaping Market Dynamics
Technological Innovation and Control Architecture Evolution
The most visible driver is the maturation of intelligent control architectures that embed optimization directly into drive hardware and firmware. Recent product introductions highlight a shift toward self-tuning parameters, adaptive torque control, and built-in energy management functions that reduce the need for external supervisory systems. At major industry exhibitions, manufacturers have demonstrated drives with integrated optimization features that adjust operating profiles based on load conditions, reducing energy waste without requiring extensive re-engineering of existing lines. This evolution lowers the barrier to adoption for mid-tier industrial users and expands the addressable base beyond high-performance automation.
Cybersecurity and functional safety are now first-class design requirements rather than add-on certifications. Updated drive platforms have begun incorporating hardened communication stacks and secure update pathways, responding to the reality that connected motor control systems are increasingly exposed to operational technology threats. As facilities integrate drives into broader industrial networks, vendors that provide verifiable security baselines and clear lifecycle patching policies are differentiating themselves in procurement evaluations.
Policy and Regulatory Momentum
Regulatory frameworks are acting as a powerful demand catalyst, particularly where energy efficiency mandates directly influence equipment selection. Efficiency standards that require higher performance classes for AC motors above defined power thresholds have accelerated the replacement of fixed-speed setups with variable-speed solutions. In parallel, safety regulations for adjustable speed power drive systems remain mandatory across multiple jurisdictions, shaping both product certification and system integration practices. These requirements are not uniform; they vary by region and application, which creates compliance complexity but also rewards vendors with global certification portfolios and regionalized support capabilities.
The cumulative effect is a regulatory tailwind that favors controllers capable of delivering measurable efficiency gains while meeting stringent safety and interoperability criteria. Procurement teams are increasingly aligning equipment specifications with compliance roadmaps, turning regulation from a constraint into a selection filter that narrows the field to vendors with proven adherence and documentation rigor.
Demand-Side Shifts in Industrial and Commercial End Users
On the demand side, operational resilience and total cost of ownership are driving procurement behavior. Industrial operators are prioritizing motor control solutions that reduce maintenance downtime, improve process consistency, and offer remote diagnostics. HVAC and water management sectors are similarly focused on energy consumption reduction, where variable-speed control delivers fast payback through reduced fan, pump, and compressor loads. Meanwhile, electrification trends in mobility and material handling are expanding the use of precision motor control in applications that require responsive torque and regenerative capabilities.
These demand patterns are shifting the evaluation criteria from unit price to lifecycle value. End users are more willing to invest in controllers that provide clearer visibility into operating conditions, predictive maintenance signals, and integration with existing control ecosystems. The result is a market where software-enabled features, service agreements, and deployment support increasingly influence purchasing decisions alongside hardware specifications.
Supply Chain and Cost Structure Realignment
Cost structures are being reshaped by both component dynamics and trade policy. On the input side, power semiconductor pricing has experienced periodic declines due to expanded production capacity, easing pressure on bill-of-materials costs for certain drive categories. However, this relief is uneven; other materials critical to drive construction have seen price increases tied to mining disruptions and logistics constraints. These fluctuations require proactive sourcing strategies, dual-sourcing arrangements, and design flexibility to substitute components without compromising performance or certification status.
Trade policy adds another layer of complexity. Tariff adjustments on specific import categories have altered regional cost comparisons, prompting manufacturers and distributors to reassess sourcing footprints and regional assembly strategies. Companies that maintain diversified supply chains and clear regional compliance documentation are better positioned to navigate these shifts, while those heavily dependent on single-source imports face greater exposure to cost volatility and lead-time risk.
Competitive Landscape and Leading Strategies
The competitive field is defined by a blend of multinational incumbents with broad automation portfolios and specialized players with deep application expertise. Leading firms are pursuing differentiation through a combination of platform breadth, application-specific tuning, and ecosystem integration. Rather than competing solely on hardware specifications, top vendors are expanding their value proposition to include deployment services, firmware lifecycle management, and interoperability with prevailing control architectures.
Strategic positioning varies by company focus. Large industrials leverage integrated drive-and-control platforms to serve complex automation environments, emphasizing precision, scalability, and engineering support. In contrast, specialists often concentrate on high-volume application segments such as HVAC, pumping, and wastewater, where energy efficiency and ease of commissioning drive adoption. Recent product updates have reinforced these strategies: revised drive lines with enhanced security features, expanded low-voltage options, and catalog updates that broaden compatibility with common industrial use cases. Trade show introductions have also highlighted optimization capabilities and process-industry refinements, signaling a market where performance is increasingly defined by how well a controller fits into a specific operational context.
Distribution and regional reach are becoming equally important. Appointment of new distribution partners in key growth regions reflects a deliberate push to improve local availability, technical support, and faster fulfillment. This is particularly relevant where end users expect shorter lead times and on-the-ground application engineering. As a result, competitive advantage is shifting toward vendors that can combine global product consistency with regional responsiveness.
Market consolidation and specialization are unfolding simultaneously. Larger players are strengthening their positions through portfolio alignment and cross-selling into adjacent automation and energy management offerings. At the same time, niche suppliers continue to gain traction by focusing on specific applications, cost-sensitive segments, or unique integration requirements. New entrants face high barriers in certification, reliability validation, and channel development, but opportunities remain in underserved application pockets and regions where localized support is scarce. The overall trend is toward a layered competitive structure: broad-platform leaders at the top, application-focused specialists in the middle, and regional distributors or system integrators extending reach and tailoring solutions to local requirements.
AC Servo Motor Market
Future Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, three trends are likely to shape commercial opportunity. First, intelligent optimization and edge-level analytics will become standard expectations rather than premium features. Drives that can autonomously adjust operating parameters, flag degradation signatures, and communicate efficiently with supervisory systems will be favored in procurement processes. This creates opportunities for vendors that can package control hardware with actionable diagnostics, simplified configuration tools, and clear data interfaces.
Second, regulation-driven adoption will continue to expand the addressable market, especially where efficiency mandates accelerate retrofit and replacement cycles. Regions with active ecodesign and motor efficiency policies will see sustained demand for variable-speed solutions, while safety and interoperability standards will push system designers toward platforms that simplify compliance documentation and multi-vendor integration. Commercial winners will be those that translate regulatory requirements into turnkey deployment pathways rather than leaving end users to assemble compliance pieces independently.
Third, supply chain and cost dynamics will reward agility. Component price cycles will remain uneven, and trade policy will continue to influence regional cost structures. Firms that invest in design modularity, diversified sourcing, and regional inventory positioning will be better equipped to protect margins and maintain service levels. For buyers, this environment favors suppliers with transparent lead-time communication, flexible configuration options, and clear roadmaps for component lifecycle management.
PW Consulting
Potential risks include the possibility that component cost relief could be temporary, that regulatory divergence could increase certification burden for global players, and that rapid feature expansion could outpace end-user readiness for integration and training. Companies that assume uniform adoption or stable input costs may face margin surprises. Conversely, organizations that prepare for variability and invest in deployment simplicity will be better positioned to convert market growth into sustainable commercial gains.
Strategic Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to align hardware roadmaps with the shifting basis of competition. This means investing in control features that reduce commissioning complexity, strengthening cybersecurity and safety documentation, and building modular designs that can accommodate component substitutions without re-certification delays. Differentiators will increasingly come from how quickly a solution can be deployed, how clearly it communicates operating status, and how well it fits into existing automation ecosystems.
For investors, the market offers opportunities in companies that demonstrate platform cohesion, regional channel strength, and disciplined cost management. Valuation and growth potential will depend less on headline volume and more on the ability to protect margins amid input price fluctuation, expand in regulation-driven segments, and capture share through application-focused solutions. Monitoring product launch cadence, distributor expansion, and compliance readiness provides early signals of competitive momentum.
For procurement and operations leaders, the focus should shift from unit price to total lifecycle value. Evaluation criteria ought to include energy performance under real load profiles, integration effort with current control infrastructure, support availability in the region, and the vendor’s ability to sustain firmware and security updates over the asset life. Supplier diversity and clear service-level expectations can reduce exposure to supply disruptions and configuration delays.
Timely access to detailed segmentation data, regional cost structures, and application-level demand patterns can sharpen these decisions and reduce execution risk. For organizations seeking a deeper view of the market, including component-level cost dynamics, regional policy timelines, and competitive positioning across application segments, a comprehensive market report can provide the granular context needed to align strategy with the next phase of growth.
Electric Vehicle Motor Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide AC Motor Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


