



Micro Excavator Market Set for 5.19% CAGR Growth Through 2032

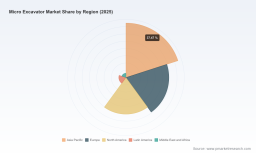
Global Micro Excavator Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global micro excavator market has demonstrated steady expansion over the past five years, evolving from a niche equipment segment into a critical component of urban infrastructure development. Valued at approximately 1,435 million USD in 2025, the market has grown from 1,120 million USD in 2020, reflecting a compound annual growth rate of 5.19 percent projected through 2032. This trajectory indicates a maturation phase where volume growth is increasingly driven by technological differentiation and regulatory compliance rather than purely by population or economic expansion.
Structural shifts within the market reveal diverging growth paths across segments. The zero tail swing category has gained significant ground against traditional tail swing designs, reflecting operator preferences for equipment that maximizes maneuverability in constrained environments. Application-wise, construction and demolition remains the dominant use case, but landscaping and agriculture sectors are exhibiting accelerated adoption rates as property developers and municipal contractors seek compact solutions for precision work. Public utilities represent a stable but slower-growing segment, benefiting from consistent infrastructure maintenance budgets rather than explosive expansion.
Despite positive momentum, the market faces three interconnected challenges that will define competitive battles over the next five years. First, supply chain volatility continues to pressure manufacturing costs. Raw material pricing, particularly for steel components essential to hydraulic systems and chassis construction, has shown variability that complicates long-term pricing strategies. Second, regulatory fragmentation across major markets creates compliance complexity. Emissions standards, safety certifications, and import duties vary significantly between regions, forcing manufacturers to maintain multiple production configurations or absorb compliance costs. Third, labor dynamics are reshaping demand patterns. Persistent skill shortages in construction sectors are accelerating automation requirements, pushing buyers toward equipment with advanced operator aids and telematics capabilities while simultaneously constraining the available workforce to operate even compact machinery.
These challenges do not undermine the market outlook but rather reshape how value is created and captured. Companies that navigate these friction points effectively will secure disproportionate market share, while those relying on legacy product architectures risk margin erosion and customer attrition.
Key Drivers Shaping Market Evolution
Technological Innovation and Equipment Differentiation
Technological advancement stands as the primary catalyst for market growth, transforming micro excavators from simple mechanical tools into connected, precision instruments. Manufacturers are investing heavily in hydraulic system optimization, cab ergonomics, and control interface design. The introduction of joystick controls, improved visibility cabins, and counter-rotation steering mechanisms reflects a broader industry focus on reducing operator fatigue and increasing work efficiency in confined spaces.
Recent product launches illustrate this innovation trajectory. Leading manufacturers have introduced ultra-short tail swing models with enhanced hydraulic responsiveness, enabling tighter turning radii and better access to urban job sites. Updated micro excavator ranges showcased at major industry events have incorporated refined cabin designs that improve operator comfort during extended shifts, directly addressing retention challenges in the construction labor market. New compact excavator models with improved cab comfort have entered the market, targeting contractors who prioritize operator retention alongside equipment performance. Additionally, zero tail swing models compliant with stringent emissions standards have been released, demonstrating how regulatory requirements can coexist with operational efficiency improvements.
Beyond mechanical improvements, digital integration is becoming a competitive differentiator. Telematics platforms that monitor equipment utilization, fuel consumption, and maintenance schedules are increasingly standard features rather than premium add-ons. This connectivity supports fleet management optimization and provides data that contractors use to justify equipment investments through measurable productivity gains.
Policy and Regulatory Environment
Regulatory frameworks are simultaneously constraining and enabling market growth. Emissions standards, particularly in Europe and North America, have compelled manufacturers to redesign engine systems and exhaust treatment components. While compliance adds upfront costs, it also creates barriers to entry that consolidate market positions among established players with sufficient engineering resources and certification infrastructure.
PW Consulting
The European Union Stage V emissions standards, which mandate reduced nitrogen oxide and particulate matter outputs for non-road diesel engines, have been in effect since 2021 and continue to shape product development roadmaps. Manufacturers that achieve compliance efficiently gain access to regulated markets without disruption, while those lagging face shipment delays and potential market exclusion. Similar regulatory pressures exist in other regions through varying mechanisms, creating a complex compliance landscape that rewards manufacturers with global engineering capabilities and diversified production footprints.
Beyond emissions, safety regulations and import policies influence market access. Tariff structures on certain origin countries affect competitive pricing dynamics, with duties on Chinese-origin equipment over specific value thresholds altering the cost advantage that some importers previously enjoyed. These trade policies encourage regional manufacturing investments and supply chain localization strategies among major players seeking to maintain price competitiveness in key markets.
Demand-Side Shifts and Construction Sector Dynamics
Changes in how construction projects are executed and funded are driving sustained equipment demand. Global construction output expanded by 3.5 percent in 2024, supported by infrastructure investments exceeding 10 trillion USD annually. This capital flow into roads, utilities, urban redevelopment, and commercial construction creates consistent demand for compact equipment that can operate in space-constrained environments where larger machinery cannot function effectively.
A critical demand-side dynamic involves labor availability. The construction sector in the United States alone faced a shortage of approximately 500,000 workers in 2024. This labor gap is accelerating demand for compact automation equipment that reduces manual labor requirements and increases individual operator productivity. Contractors are increasingly willing to invest in higher-specification micro excavators with operator aids, improved hydraulics, and telematics because these features help maximize output from smaller crews and reduce reliance on multiple personnel for tasks that compact equipment can handle more efficiently.
Urbanization trends further support demand. As cities expand and existing infrastructure requires renovation, demolition and rebuilding activities increasingly occur in dense neighborhoods where large equipment faces access restrictions, noise limitations, and safety constraints. Micro excavators fit precisely into this operational paradigm, enabling contractors to work in alleys, residential zones, and interior spaces without the logistical burden of larger machines.
Supply Chain and Cost Structure Dynamics
Cost pressures and supply chain stabilization efforts are reshaping manufacturing strategies. Raw material pricing for construction machinery inputs, including hot-rolled steel coils, averaged around 650 USD per metric ton in the fourth quarter of 2024 amid gradual supply chain stabilization. While this represents improvement from earlier volatility, cost management remains a strategic priority as manufacturers balance material expenses with competitive pricing expectations.
Manufacturers are responding through multiple approaches: optimizing component design to reduce material usage, negotiating long-term supplier agreements to lock in pricing, and exploring alternative material specifications where performance requirements allow. Regional production strategies are also gaining traction, with companies establishing or expanding manufacturing footprints closer to end markets to reduce logistics costs, mitigate tariff impacts, and improve supply chain resilience.
The cost structure evolution is not purely defensive. Efficient supply chain management and localized production can become competitive advantages, enabling manufacturers to offer more consistent pricing, faster delivery times, and improved after-sales support. These operational capabilities increasingly factor into procurement decisions alongside equipment specifications.
Competitive Landscape and Leading Strategies
The market features a diverse competitive field spanning established global manufacturers, specialized compact equipment producers, and regional players with strong local presence. Market concentration metrics indicate that the top three companies capture approximately 38.5 percent of revenue, while the top five hold roughly 52.8 percent. This concentration level suggests a moderately consolidated landscape where leading players exert significant influence but substantial share remains available for well-positioned competitors.
Leading manufacturers have adopted distinct strategic positioning approaches. Major equipment companies with broad product portfolios leverage their brand recognition, global service networks, and financial strength to offer micro excavators as part of comprehensive fleet solutions. These players emphasize telematics integration, dealer support infrastructure, and the ability to supply equipment across multiple size classes, appealing to large contractors who value single-source procurement and standardized maintenance processes.
Japanese manufacturers have carved out strong positions through specialization in compact and micro segments. Their product architectures emphasize zero tail swing designs, fuel-efficient engine systems, and refined operator interfaces tailored to precision work. These companies often compete on reliability, maneuverability, and segment-specific engineering rather than broad portfolio breadth. Their focus on micro excavators as a core competency rather than a peripheral offering enables deep optimization of weight, size, and functionality for targeted applications.
European and American players contribute through varied approaches. Some emphasize electrification alongside diesel options, offering zero-emission alternatives for urban environments with noise or air quality restrictions. Others focus on GPS integration and grade control technologies that enhance precision for landscaping and utility work. These technology-forward strategies appeal to contractors operating in regulated urban zones or those seeking to differentiate through higher-precision outputs.
Chinese manufacturers have expanded their presence through competitive pricing and increasingly sophisticated feature sets. Their product ranges target emerging markets and cost-sensitive segments while incorporating intelligent control systems and efficiency improvements that narrow the perceived quality gap with established brands. Trade policy dynamics, including tariff structures on certain origin equipment, influence the competitive balance in specific regions, prompting some Chinese manufacturers to pursue regional assembly strategies or partner with local distributors to navigate trade barriers.
Strategic differentiation is evolving along several dimensions. Electrification represents a growing battleground, with manufacturers offering electric micro excavators under specific weight thresholds for applications where indoor operation, noise sensitivity, or emissions restrictions favor battery-powered alternatives. Telematics and data connectivity are becoming standard expectations rather than differentiators, pushing competition toward deeper integration with contractor fleet management systems and predictive maintenance capabilities.
Excavator Attachments Market
Market evolution trends point toward continued consolidation pressure alongside ongoing fragmentation in niche segments. Larger players may pursue acquisitions to gain specialized technology, regional distribution networks, or product line completeness. At the same time, specialized manufacturers with strong micro excavator expertise can thrive by serving specific applications or geographic markets with focused value propositions. New entrants face high barriers due to engineering complexity, certification requirements, dealer network development costs, and the need to establish reliability reputations, but opportunities exist for companies that bring distinctive technology or serve underserved application niches.
Future Trends and Commercial Implications
Looking toward 2032, several trends will shape market trajectories and create distinct commercial opportunities. The first and most consequential is the acceleration of electrification and alternative powertrain adoption. While diesel micro excavators will remain dominant in the near term, electric models are gaining traction for specific use cases where operational restrictions, urban noise ordinances, or corporate sustainability commitments favor zero-emission equipment. As battery technology improves and charging infrastructure expands, electric micro excavators will capture growing share in landscaping, indoor construction, and municipal applications. Manufacturers that develop robust electric platforms with competitive runtime, fast charging options, and integrated energy management will position themselves advantageously for regulated urban markets and sustainability-focused contractors.
The second trend involves deepening digital integration and data-driven equipment management. Telematics will evolve from basic utilization tracking to predictive maintenance, remote diagnostics, and performance optimization recommendations. Contractors will increasingly expect equipment that integrates seamlessly with their digital workflows, providing data that supports operational decisions, reduces downtime, and improves resource allocation. Companies that offer open data architectures, compatible fleet management software, and responsive remote support will differentiate themselves as the market shifts from evaluating individual machine specifications to assessing total fleet intelligence capabilities.
Excavator Market
The third trend relates to continued urbanization and infrastructure renewal driving sustained demand for compact, maneuverable equipment. As cities densify and renovation activities displace new ground-up construction in many developed markets, the operational niche for micro excavators will expand. Contractors will require equipment that navigates confined spaces, complies with noise and emissions restrictions, and delivers precision work without the logistical complexity of larger machinery. This environment favors manufacturers with strong zero tail swing designs, versatile attachment compatibility, and configurations optimized for urban job site constraints.
These trends carry both opportunities and risks. Electrification promises market expansion but introduces uncertainty around battery costs, charging logistics, and performance parity in demanding applications. Digital integration enhances value but raises expectations for software reliability, cybersecurity, and ongoing technical support that smaller manufacturers may struggle to meet consistently. Urban demand growth is robust but depends on continued infrastructure spending and regulatory environments that sustain construction activity. Economic cycles, interest rate fluctuations, and shifts in government investment priorities could moderate growth rates, particularly in segments dependent on discretionary development rather than essential infrastructure maintenance.
Commercial opportunities will accrue to companies that align product development with these trajectories. Manufacturers can capture growth by expanding electric model ranges, enhancing telematics integration, and optimizing products for urban constraints. Investors can evaluate companies based on their technology roadmaps, regional market access, and ability to navigate regulatory and trade complexity. Procurement professionals can focus on total cost of ownership considerations that include operator efficiency, maintenance predictability, and compliance assurance rather than initial purchase price alone.
Strategic Recommendations for Decision Makers
Manufacturers should prioritize technology roadmaps that balance emissions compliance, electrification capabilities, and digital integration while maintaining cost competitiveness. Investing in zero tail swing architectures, operator comfort improvements, and telematics platforms will address the key purchase drivers identified by contractors. Companies should also evaluate regional production and supply chain strategies to navigate tariff dynamics and raw material cost variability, ensuring that pricing remains attractive while margins are protected through operational efficiency and localized support infrastructure.
Investors evaluating opportunities in this market should focus on companies with clear technological differentiation, strong regional market access, and capabilities to manage regulatory complexity. The moderate market concentration suggests room for growth, but sustained value creation will favor players that can execute on product innovation, service network development, and strategic geographic positioning. Assessing a company's electrification roadmap, data integration maturity, and ability to adapt to trade policy shifts will provide insight into long-term competitive positioning beyond current revenue performance.
Procurement teams and contractors should approach equipment selection with a total cost of ownership mindset that accounts for operator productivity, maintenance predictability, compliance assurance, and fleet integration capabilities. The labor shortage environment makes operator efficiency and retention increasingly valuable, supporting investment in equipment with improved ergonomics, automation aids, and telematics that reduce downtime and simplify fleet management. Evaluating suppliers based on their ability to deliver consistent product availability, responsive service support, and compliance with regional emissions standards will mitigate operational risk and support long-term project execution.
For stakeholders seeking detailed segment-level data, regional analysis, competitive benchmarking, and customized strategic recommendations, comprehensive market research reports provide the depth required for precise planning. Access to granular data across product types, application segments, regional dynamics, and company profiles enables more informed decisions regarding market entry, investment allocation, product development priorities, and procurement strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


