



Cast Aluminum Cookware Market: Why 5.24% CAGR & Asia Pacific Shift Change Everything

Global Cast Aluminum Cookware Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
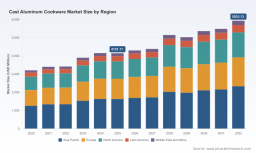
The worldwide cast aluminum cookware market has demonstrated consistent expansion, with revenue reaching approximately 4.15 billion USD in 2025. The sector has navigated a period of steady growth from 2020 through 2025, transitioning into a forecast period that extends to 2032. Projections indicate the market will approach the 6 billion USD threshold by the end of the forecast window, supported by a compound annual growth rate of 5.24 percent. This trajectory reflects a mature yet evolving industry where volume expansion increasingly depends on value differentiation rather than raw capacity additions.
Several structural shifts are reshaping the competitive baseline. First, regulatory pressure around chemical coatings is accelerating formulation changes across the supply chain. Jurisdictions such as California have moved to restrict cookware containing intentionally added PFAS, effective from early 2025. This creates compliance complexity for manufacturers relying on traditional nonstick chemistries and pushes brands toward alternative surface technologies, reformulated coatings, or uncoated hard-anodized variants. Second, input cost volatility remains a persistent pressure point. Primary aluminum transaction prices have experienced notable swings, and dependence on concentrated production hubs exposes downstream cookware makers to supply disruptions and currency effects. These dynamics compress margins for undifferentiated products while rewarding manufacturers that secure stable sourcing arrangements or pass cost efficiency into premium positioning. Third, channel fragmentation is altering how value is captured. Online commerce has grown its share of distribution, but offline retail still commands substantial volume, particularly in mass-market and regional segments. Companies must balance channel economics, inventory risk, and brand visibility without diluting price discipline.
These challenges are not purely headwinds. They function as filters that reward scale, technical competence, and regulatory readiness. Firms that treat compliance, material sourcing, and channel strategy as integrated design choices are better positioned to convert market growth into durable margin expansion.
Key Demand and Supply Drivers
Technology innovation continues to redefine product value. Advances in nonstick coating formulations, induction-compatible base structures, and multilayer casting methods are enabling lighter cookware with improved heat distribution and durability. Pressure-casting techniques and recycled aluminum integration are also gaining traction, allowing producers to reduce weight, improve consistency, and address sustainability expectations without sacrificing performance. These improvements matter because they expand the addressable use cases for cast aluminum beyond traditional cost-sensitive applications and into premium residential and multi-cooktop environments.
Aluminum Casting Market
Policy and regulatory environments are increasingly shaping product roadmaps. Beyond PFAS-related restrictions, trade policy is affecting landed costs and sourcing decisions. Additional duties on certain aluminum products imported from China have added complexity to cost planning for brands that rely on cross-border supply chains. At the same time, stricter environmental expectations are encouraging material traceability, recycled content, and longer product lifecycles. The combined effect is a market where regulatory and trade dynamics are not external noise but core inputs to product design, supplier selection, and pricing architecture.
On the demand side, consumer behavior is tilting toward convenience, health-conscious messaging, and cookware compatibility with modern kitchens. Households are investing in fewer, higher-quality pieces that work across gas, electric, and induction surfaces. In commercial settings, foodservice operators prioritize dent resistance, consistent heating, and low maintenance, especially in high-volume environments where downtime and replacement frequency directly affect cost control. These divergent requirements create distinct value propositions within the same material category, supporting both premium and value-tier segments simultaneously.
Supply chain and cost structure changes reinforce the importance of flexibility. Primary aluminum production remains geographically concentrated, and regional price disparities can create arbitrage opportunities or exposure depending on sourcing strategy. Manufacturers that combine localized finishing or assembly with disciplined raw material procurement are better equipped to manage tariff exposure, lead times, and working capital. Meanwhile, the shift toward e-commerce and direct-to-consumer models is altering inventory positioning and packaging requirements, making agility in demand forecasting and channel mix a competitive advantage.
Stainless Steel Cookware Market
Competitive Landscape and Leading Strategies
The industry is characterized by a mix of established multinational players, specialized premium brands, and high-volume regional producers. Market concentration remains moderate, indicating that share gains are still achievable through differentiation rather than consolidation alone. Companies are competing on multiple fronts at once: coating performance, induction readiness, aesthetic design, durability claims, and channel reach. The result is a landscape where positioning is increasingly specific rather than generic.
Several strategic archetypes are evident. Premium-focused brands emphasize advanced nonstick surfaces, induction compatibility, and high-temperature oven safety, targeting consumers who value performance and design and are willing to pay for durable, multifunctional products. These players often use trade exhibitions and retail partnerships to reinforce credibility and visibility. Value-oriented manufacturers compete on price, practicality, and broad foodservice suitability, offering standard nonstick lines, woks, saute pans, and steam table components that meet commercial durability expectations without premium pricing. In parallel, brands built around consumer franchises or lifestyle identities use set configuration, hard-anodized exteriors, and accessible price points to capture mainstream retail demand.
Commercial specialists remain critical to the overall market. Suppliers serving foodservice prioritize dent-resistant bottoms, consistent heat transfer, and ease of cleaning, recognizing that total cost of ownership matters more than upfront price in professional kitchens. Their product lines are often optimized for repeated use, high-temperature service, and compatibility with common commercial cooktops and ovens. This commercial segment provides a stable demand base that can offset volatility in consumer discretionary spending.
Recent exhibition activity illustrates how companies are using visible market moments to reinforce product direction. In early 2024, multiple manufacturers showcased cast aluminum skillets, griddles, and nonstick collections at major trade events, highlighting pressure-cast construction, induction readiness, and reformulated surface technologies. These presentations are not merely promotional; they signal where brands are placing bets on future demand, particularly around multifunctionality and compliance-friendly materials.
The competitive trend appears to be moving toward segmentation with overlapping competition. Premium and value tiers are both expanding, but they are not converging quickly because the underlying performance and cost requirements differ. New entrants can succeed by targeting underserved application niches, such as specific induction configurations, commercial durability at mid-range pricing, or region-specific retail preferences. Incumbents, meanwhile, are strengthening moats through coating expertise, sourcing reliability, and brand trust. M&A and partnership activity may increase where scale in sourcing or distribution can convert into margin advantage, but differentiation will remain the primary battleground.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, two to three trends are likely to shape opportunity sets. First, compliance-driven coating innovation will become a standard product requirement rather than a niche advantage. As restrictions on certain chemical additives broaden and consumer sensitivity increases, brands that can deliver durable nonstick performance without relying on restricted chemistries will command stronger shelf positioning and lower regulatory risk. This creates openings for coating specialists, material scientists, and manufacturers that can validate performance claims with consistent test data and transparent sourcing narratives.
PW Consulting
Second, induction compatibility and multifunctionality will increasingly serve as baseline expectations, especially in regions where appliance mix is shifting. Cookware that works reliably across cooktop types and can transition from stovetop to oven expands consumer utility and reduces replacement cycles. The commercial implication is clear: product lines should be designed for interoperability, not just for a single cooking environment. This is especially relevant where kitchen upgrades are accompanied by appliance changes, since cookware compatibility often becomes a purchase criterion at the point of replacement.
Third, supply chain regionalization and cost management will matter more as trade policy and input prices continue to fluctuate. Companies that diversify sourcing, secure longer-term aluminum supply agreements, or adapt product geometry to optimize material use can protect margins more effectively than those dependent on single-channel procurement. There is also opportunity in recycled content and lighter-gauge engineering where performance allows, both to manage cost and to align with sustainability expectations.
These trends carry uncertainty. Regulatory timelines can shift, enforcement intensity may vary by region, and raw material prices can change quickly enough to disrupt planning horizons. Brands that treat these variables as dynamic inputs rather than fixed assumptions will be better prepared to adjust product mixes, pricing, and sourcing without losing market momentum.
Actionable Recommendations for Decision-Makers
Manufacturers should prioritize integrated product design that combines compliance-ready coatings, induction compatibility, and durable base construction. Where possible, investment in coating validation, material traceability, and channel-specific packaging can protect differentiation and reduce exposure to regulatory or trade disruptions. Aligning product roadmaps with both residential convenience and commercial durability requirements can broaden addressable demand without fragmenting brand identity.
Investors should assess exposure to regulatory transitions, input cost sensitivity, and channel mix when evaluating opportunities. Businesses with stable sourcing, clear compliance positioning, and resilient commercial demand tend to offer more predictable operating profiles than those dependent on single-material sourcing or price-led competition. Commercial foodservice-oriented suppliers and brands with strong multifunction performance can provide defensibility even when discretionary consumer spending softens.
Procurement and retail buyers should weigh total cost of ownership, compatibility with existing cooktops, and compliance documentation alongside upfront price. Diversifying across coating technologies and supplier geographies can reduce risk while maintaining product quality. In commercial procurement, prioritizing dent resistance, ease of cleaning, and consistent heating can lower replacement frequency and service interruptions over time.
For organizations seeking a deeper view of segment sizing, regional dynamics, pricing patterns, and competitive benchmarks, the full PW Consulting market study provides detailed segmentation data and tailored scenario analysis to support planning across product, channel, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Aluminum Cookware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


