



Otolaryngology Endoscopy Market: Why 6.52% CAGR and Shifting Dynamics Redefine Growth

Navigating the Global Otolaryngology Endoscopy Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
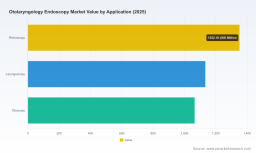
The global otolaryngology endoscopy market has demonstrated consistent expansion, reaching an estimated valuation in 2025 before progressing toward a projected valuation by 2032. This trajectory reflects a compound annual growth rate of approximately 6.52 percent across the forecast horizon. Such growth underscores the procedure's central role in modern ear, nose, and throat care, driven by procedural volume increases and procedural complexity. The market structure reveals notable concentration, with the top three players commanding nearly half of total revenue and the top five entities controlling over sixty percent. This consolidated landscape suggests established incumbents hold significant sway over pricing, distribution channels, and technological standards, while smaller specialized firms navigate limited whitespace without strategic partnerships or niche differentiation.
Several structural headwinds currently shape market dynamics. First, supply chain fragility continues to pressure manufacturers, particularly for precision optics, specialized sensors, and medical-grade polymers. Component shortages and logistics disruptions have historically extended lead times and inflated production costs, forcing companies to reassess inventory strategies and supplier diversification. Second, reimbursement environments remain uneven across regions and procedure codes. While certain automated delivery systems and advanced visualization techniques have secured favorable payment classifications, many health systems face budget constraints that delay capital equipment upgrades. This reimbursement uncertainty directly influences procurement cycles and limits the speed at which newer technologies diffuse into clinical practice. Third, the sector faces a talent and training bottleneck. Advanced endoscopic procedures demand specialized clinical proficiency, yet training infrastructure often lags behind equipment availability. Hospitals and ambulatory surgery centers must invest in simulation programs, credentialing pathways, and continuous education to realize the full value of modern endoscopic platforms, creating an adoption friction point that manufacturers and service providers must address holistically.
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Technological innovation remains the most visible accelerator of market evolution. Visualization quality has improved markedly through enhanced depth-of-field optics, higher-resolution video processors, and integrated imaging workflows. Recent regulatory clearances for systems featuring extended depth of field capabilities and towerless hybrid architectures illustrate how engineering advances translate into procedural efficiency. These platforms reduce setup complexity, improve surgeon ergonomics, and support faster turnover between cases, which matters greatly in high-volume ENT practices. At the same time, single-use flexible endoscopy has matured from a niche concept into a credible alternative for diagnostic procedures. Single-use devices lower cross-contamination risk, streamline reprocessing workflows, and reduce downstream costs associated with sterilization and instrument maintenance. This shift aligns with institutional priorities around infection control and operational simplification, particularly in outpatient settings where throughput and patient turnover are critical metrics.
Regulatory and reimbursement developments are reshaping commercial pathways. Recent clearance activity has expanded the procedural envelope for both diagnostic and therapeutic endoscopy, including indications that support transoral approaches for select oropharyngeal conditions and novel navigation systems designed for cranial and sinus applications. Clearer procedural indications reduce commercial uncertainty and encourage earlier adoption by demonstrating acceptable safety and performance profiles. On the payment side, the assignment of national payment rates to specific procedural codes for automated tube delivery and localized anesthesia techniques signals a broader willingness to recognize technology-enabled efficiency. When reimbursement frameworks explicitly value automation and precision delivery, hospitals gain fiscal justification to invest in compatible capital equipment, creating a virtuous cycle of device uptake and procedural standardization.
Demand-side behavior is shifting as care delivery models evolve. Patients and providers alike increasingly favor minimally invasive diagnostics that can be performed in office-based settings rather than operating rooms. Office-based endoscopy reduces facility fees, shortens wait times, and supports same-day decision-making, making it attractive for both health systems and payers. This preference accelerates demand for portable, high-quality visualization tools and single-use scopes suited to ambulatory workflows. Simultaneously, hospital operators continue to allocate substantial capital toward infrastructure modernization. Large health networks have outlined multi-year capital expenditure programs that explicitly include imaging and endoscopy system upgrades, reflecting a strategic intent to standardize platforms, improve surgical precision, and support expanded service lines. When capital budgets align with clinical priorities, procurement cycles accelerate and multi-year platform agreements become more common.
Laryngoscope Market
Supply chain and cost structures are undergoing parallel transformation. Manufacturers are rebalancing toward regional sourcing, dual-supplier strategies, and modular component designs that allow faster production adjustments when demand shifts. These approaches help mitigate volatility in optical elements, display components, and disposable materials. At the same time, the cost equation for end-users is changing. While advanced visualization platforms require meaningful upfront investment, total cost of ownership arguments increasingly account for reduced reprocessing labor, fewer repair events, and improved case throughput. Buyers are therefore evaluating purchases not solely on sticker price but on workflow integration, service availability, and clinical outcomes. This more sophisticated evaluation framework rewards vendors that can demonstrate measurable operational benefits rather than device features in isolation.
Competitive Landscape and Strategic Positioning
The market is defined by a mix of large diversified conglomerates, focused endoscopy specialists, and emerging innovators targeting specific procedural niches. Established players have built strong positions through broad product portfolios, global distribution networks, and long-standing relationships with surgical teams. Their advantage lies in the ability to offer integrated solutions spanning rigid and flexible scopes, video processors, navigation platforms, and related instruments. This comprehensiveness simplifies purchasing for health systems that prefer fewer vendor interfaces and standardized service contracts. Differentiation among incumbents increasingly depends on workflow integration, image quality, and the degree to which platforms connect with navigation or robotics ecosystems. Companies that can unify planning, visualization, and instrument control within a coherent clinical workflow create meaningful switching costs and support recurring revenue through servicing and consumables.
Several strategic themes distinguish the competitive field. First, single-use and hybrid device strategies are expanding. Some manufacturers have introduced disposable flexible video rhinolaryngoscopes tailored for diagnostic and therapeutic use, while others have brought forward hybrid systems that combine rigid and flexible capabilities within a single platform. These moves address two distinct demands: infection control and reprocessing simplification on one hand, and procedural versatility on the other. Second, navigation and robotics integration is becoming a competitive battleground. Advanced navigation platforms designed for sinus and skull base procedures, along with systems that unify planning and instrument guidance, are gaining regulatory clearances and clinical visibility. These technologies appeal to centers treating complex pathologies where precision and anatomical orientation directly influence outcomes. Third, smaller innovators are carving opportunities through specialized navigation features, steerable flexible platforms for nasal and upper airway applications, and streamlined towerless designs that reduce footprint in crowded procedure rooms. Such entrants often compete on agility, focused clinical claims, and faster iteration cycles.
Market structure appears to be moving along two parallel tracks. Consolidation remains likely as larger organizations seek to expand procedural coverage, geographic reach, and consumables attach rates through acquisitions or partnership arrangements. At the same time, segmentation is intensifying. Different care settings—large academic hospitals, community surgical centers, and office-based practices—have distinct requirements for portability, reprocessing capacity, and capital tolerance. This divergence encourages vendors to develop tiered offerings, where high-end integrated systems serve complex surgical environments while streamlined portable units and single-use options address outpatient and ambulatory demand. New entrants that can demonstrate clear clinical utility, regulatory compliance, and a credible reimbursement pathway stand a realistic chance of gaining footholds, even in a concentrated market, provided they solve a specific workflow pain point rather than competing broadly on general specifications.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
One defining trend is the continued blurring of diagnostic and therapeutic endoscopy. As imaging clarity improves and instrument channels become more capable, clinicians increasingly move from visualization to intervention within the same procedural session. This evolution favors platforms that support smooth transitions from diagnosis to treatment, including compatible instruments, reliable suction and irrigation, and integrated navigation where anatomical complexity warrants it. Companies that design for this continuum—rather than treating diagnosis and therapy as separate product lines—will be better positioned to capture recurring procedural volume and consumables demand.
A second trend is the institutionalization of single-use endoscopy for selected indications. As clinical evidence matures and cost models are refined, single-use flexible scopes are likely to claim a growing share of diagnostic examinations, particularly where turnaround time, sterility assurance, and space constraints matter. The commercial implication is a shift in revenue mix: lower per-unit pricing for disposable devices must be offset by higher volumes, streamlined supply agreements, and reliable distribution. Manufacturers that can standardize specifications, ensure consistent quality, and align with facility procurement cycles will benefit most. At the same time, hybrid strategies that pair durable capital systems with consumable accessories and selected disposables may become the dominant economic model for many providers.
A third trend involves deeper integration of navigation, planning tools, and data-enabled workflow support. Rather than viewing endoscopy as an isolated visualization task, leading centers increasingly treat it as part of a broader procedural ecosystem that includes pre-operative planning, intra-procedural guidance, and post-procedural documentation. This trajectory opens opportunities for software-driven differentiation, interoperable device ecosystems, and analytics that help hospitals benchmark throughput, complication rates, and instrument utilization. The associated risk is that integration requirements raise the barrier to entry and increase dependency on a small number of platform providers. Buyers may consequently demand greater interoperability, transparent data ownership provisions, and flexible service terms to avoid lock-in while still capturing clinical benefits.
Worldwide Respiratory Endoscope Market
Actionable Implications for Decision-Makers
For manufacturers and technology developers, the priority is to build modular yet integrated solutions that serve multiple care settings without sacrificing clinical performance. Portfolio strategy should balance advanced visualization and navigation for complex surgical environments with portable, low-footprint, and single-use options for office-based and ambulatory use. Equally important is aligning product roadmaps with reimbursement realities: devices that help standardize procedures, reduce reprocessing burden, or enable office-based care will find stronger adoption pathways when paired with clear payment logic and clinical evidence. Companies should also invest in training and service ecosystems, since adoption friction often hinges on clinician confidence and operational readiness rather than hardware specifications alone.
For investors, the most promising signals sit at the intersection of workflow simplification and procedural expansion. Capital allocation should favor platforms that demonstrate genuine integration benefits, recurring consumables potential, and credible clearances for expanded indications. It is also prudent to monitor suppliers and sub-systems where supply chain resilience is improving, as component reliability increasingly determines which vendors can scale consistently. Careful attention to reimbursement developments and hospital capital expenditure guidance can provide early indicators of procurement momentum, especially in markets where payment classification changes have recently improved the economics of technology-enabled procedures.
For procurement leaders and health system executives, the strategic question is less about buying a scope than about selecting a platform that fits long-term service lines and operational goals. Evaluations should weigh image quality and instrument compatibility alongside reprocessing demands, training requirements, service coverage, and interoperability with existing navigation or imaging infrastructure. Where possible, pilot programs and structured clinical assessments can reduce uncertainty before multi-year commitments. As the market continues to evolve, organizations that secure detailed, up-to-date intelligence on segment dynamics, pricing structures, and regulatory trajectories will be better equipped to time investments, negotiate terms, and build procurement strategies aligned with both clinical needs and fiscal constraints.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Otolaryngology Endoscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


