



Worldwide Wireless Communication Systems: The Forces Behind 12.48% CAGR Growth

Worldwide Wireless Communication Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
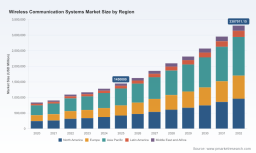
The worldwide wireless communication systems market has evolved from a connectivity utility into a strategic infrastructure layer that underpins digital transformation across industries. Valued at approximately 1.45 billion USD in 2025, the market has demonstrated consistent expansion over the past five years and is projected to accelerate through the 2032 horizon. The compound annual growth rate of 12.48 percent reflects a structural shift rather than a cyclical upturn, driven by the maturation of fifth-generation networks, the gradual retirement of legacy fourth-generation deployments, and the increasing integration of satellite and short-range wireless architectures into unified communication ecosystems.
Despite this robust trajectory, the sector is navigating a set of interconnected challenges that will shape competitive positioning and capital allocation decisions in the near term. The first challenge lies in the physical and economic density of next-generation infrastructure. Deploying advanced radio access networks and backhaul systems requires substantial upfront investment, and operators are under continuous pressure to justify site-level economics while expanding coverage and capacity. This tension is particularly pronounced in regions where population density, terrain complexity, and regulatory approval timelines intersect, forcing vendors and service providers to rethink deployment models and cost-sharing frameworks.
The second challenge centers on fragmentation in standards, interoperability, and vendor ecosystems. The industry is moving toward disaggregated architectures and open interface frameworks, which promise greater flexibility and lower switching costs. At the same time, this transition introduces integration complexity, testing overhead, and the need for new operational competencies. Organizations that cannot manage multi-vendor interoperability or align their hardware and software roadmaps with evolving interface specifications risk higher total cost of ownership and slower time-to-market for new services.
A third challenge is the shifting regulatory and geopolitical landscape. Spectrum allocation decisions, export controls on advanced semiconductors, and platform interoperability mandates are increasingly influencing where and how wireless systems can be designed, manufactured, and deployed. These dynamics are not uniform across regions, which means global players must operate with greater architectural flexibility and regional adaptation. The market's overall concentration, with the top three participants holding roughly 38.45 percent and the top five holding about 52.12 percent, indicates that scale, portfolio breadth, and ecosystem relationships remain decisive, but it also leaves room for specialized players that can deliver differentiated technology or cost advantages in targeted segments.
PW Consulting
Key Drivers Shaping Market Dynamics
Technology Innovation and Architectural Shift
The transition from fourth-generation systems to fifth-generation and emerging fifth-generation advanced capabilities is the most visible driver of market expansion. This is not simply a matter of faster peak speeds; it is an architectural shift that enables network slicing, lower latency, and more granular service differentiation. Recent commercial activity illustrates how quickly these capabilities are being operationalized. In early 2025, Ericsson was selected by Deutsche Telekom to upgrade the 5G standalone core across Germany, signaling a move toward fully independent core architectures that can support diverse enterprise and consumer workloads. Around the same period, Nokia deployed 5G advanced equipment for China Mobile across multiple provinces, reinforcing the industry's push toward higher-throughput radio systems and more efficient resource utilization.
At the device and component level, the innovation curve is extending beyond traditional smartphones and base stations. Qualcomm's introduction of a new 5G modem-RF platform designed to support reduced-capability devices and lightweight wireless standards points to a broader vision in which lower-power, cost-sensitive endpoints can participate in advanced wireless networks. This expands the addressable base beyond high-end mobile devices and creates new pathways for industrial sensors, wearables, and specialized telemetry equipment. Huawei's launch of a 5.5G solution with 10Gbps peak speeds for commercial trials in Asia further underscores the industry's focus on pushing throughput boundaries while preparing networks for denser traffic patterns and more demanding applications.
Policy, Spectrum, and Regulatory Environment
Policy decisions continue to shape both the pace and geography of wireless investment. Spectrum availability remains a foundational enabler, and recent auction activity demonstrates how aggressively operators are securing mid-band and other valuable frequencies. In one notable allocation, the FCC awarded 102 licenses in the 3.45-3.55 GHz band, raising 1.82 billion USD and highlighting the strategic value of mid-band spectrum for balancing coverage and capacity. At the same time, regulatory frameworks are increasingly addressing the broader digital ecosystem rather than wireless infrastructure in isolation. The restoration of net neutrality rules under Title II classification in the United States and the enforcement of interoperability requirements for gatekeeper platforms in the European Union both signal a more interventionist stance on how networks and platforms interact.
These regulatory moves matter because they influence service design, traffic management, and the commercial models that operators and enterprises can build on top of wireless systems. For vendors, regulatory certainty can reduce planning risk, while sudden policy shifts can alter demand forecasts and regional prioritization. For enterprises, clearer rules around interoperability and traffic treatment can lower integration risk and make wireless-dependent solutions more predictable from a compliance standpoint.
Demand-Side Transformation Across Sectors
Demand is no longer concentrated solely in traditional telecommunications services. Industrial operations, consumer devices, and mobility applications are all generating new requirements for reliable, scalable, and often low-latency wireless connectivity. Industrial environments are increasingly adopting private and hybrid network models to support automation, asset tracking, and real-time control, which places a premium on predictable performance and integration with operational technology. Consumer electronics continue to expand the base of connected endpoints, but the more strategically important shift is the growing expectation that devices and services should work seamlessly across cellular, Wi-Fi, and short-range networks depending on context and cost.
In transport and automotive applications, wireless systems are enabling vehicle-to-infrastructure communication, fleet telemetry, and in-cabin connectivity, all of which depend on a combination of coverage, resilience, and spatial reuse. This diversification of end users means that wireless communication systems are becoming multi-purpose platforms rather than single-use networks. The strategic implication is that suppliers must design for flexibility: the same infrastructure should be able to serve mobile operators, enterprises, and vertical industries with different service levels and operational constraints.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by both infrastructure economics and component-level constraints. The average cost of deploying a 5G base station, typically ranging from 100,000 to 300,000 USD per site, remains a meaningful barrier to rapid dense deployment, especially when operators are balancing capital expenditure against uncertain revenue uplift in certain areas. This cost pressure is encouraging experimentation with virtualized radio architectures, centralized processing, and more efficient site designs that can reduce per-location expenditures or improve utilization.
Worldwide Underwater Communication System Market
At the same time, export controls on advanced semiconductors have introduced new uncertainty into the supply of high-performance chips used in both network equipment and end-user devices. Restrictions imposed on semiconductor exports to Huawei in late 2023, for example, illustrate how geopolitical considerations can affect product roadmaps, regional availability, and competitive dynamics. These supply-side factors are pushing companies to diversify sourcing, design for component flexibility, and in some cases re-evaluate where critical manufacturing and integration activities are located.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established infrastructure incumbents, semiconductor and platform specialists, and regional players with strong execution capabilities in specific markets. Ericsson and Nokia remain central to the carrier-grade infrastructure conversation, with portfolios that span radio access, core networks, and cloud-aligned platforms. Ericsson's recent core upgrade work with Deutsche Telekom emphasizes end-to-end control of the standalone architecture, which can be a differentiator for operators seeking to standardize on a single vendor's ecosystem for manageability and service orchestration. Nokia's deployment of 5G advanced equipment for China Mobile highlights a strategy centered on scaling proven radio and baseband technologies across large operator networks while supporting next-generation features such as massive MIMO and advanced antenna systems.
Samsung and Qualcomm illustrate a different but complementary axis of competition. Samsung's expanded Open RAN 5G network work with Verizon in the US Midwest reflects a push toward virtualized and open-interface infrastructure that can reduce dependence on single-vendor stacks and broaden integration options for operators. Qualcomm's modem-RF platforms anchor much of the device-side ecosystem, and its continued investment in reduced-capability and lightweight wireless standards shows a strategy aimed at broadening the range of connectable devices and use cases beyond premium smartphones. This device-to-network alignment is increasingly important because wireless system value is shaped not only by infrastructure performance but also by the diversity and capability of endpoints.
Huawei, ZTE, NEC, Fujitsu, Cisco, and CommScope each occupy distinct strategic positions. Huawei's full-stack 5G approach and emphasis on AI-driven optimization and high-capacity base stations position it as an integrated solution provider, even as export controls and regional restrictions shape where and how its offerings can be deployed. ZTE's focus on macro and small-cell radio systems with carrier aggregation supports operators seeking capacity gains through dense site architectures. NEC's microwave and radio systems serve backhaul and fronthaul needs, which remain critical as traffic grows and fiber availability varies by region. Fujitsu's RIC and O-RAN compliant base stations align with the broader move toward programmable, disaggregated networks. Cisco continues to strengthen its role in enterprise wireless LAN environments by integrating Wi-Fi 6 and 6E access points with SD-WAN and broader networking fabrics, while CommScope provides radio and antenna solutions for small cells and macro sites, addressing the physical-layer realities of densification.
Wireless Communication Intelligent Module Market
What ties these strategies together is a gradual re-balancing between integration and openness. Leading players are investing in platforms that can operate across proprietary and open interfaces, and they are positioning themselves as enablers of hybrid architectures rather than as single-stack vendors. Market concentration remains significant, but the landscape is also becoming more modular, which creates opportunities for specialized suppliers in radios, antennas, control software, device platforms, and integration services. The companies most likely to sustain advantage are those that can combine technical performance with deployment efficiency, multi-vendor compatibility, and the ability to tailor solutions to regional spectrum, cost, and regulatory conditions.
Future Trends and Strategic Implications
Over the next three to five years, one clear trend is the continued convergence of cellular, short-range, and satellite wireless capabilities into more unified service experiences. Networks will increasingly be evaluated not only on peak throughput but on how effectively they can hand off traffic, prioritize critical sessions, and support varied device classes without fragmenting the user or enterprise experience. This creates opportunities for providers that can offer orchestration layers, cross-domain management, and service assurance across heterogeneous environments.
A second trend is the acceleration of virtualized and software-defined radios and cores, which will make networks more adaptable but also increase the importance of integration, automation, and security. As functions become more software-centric, the competitive edge will shift toward operational efficiency, lifecycle management, and the ability to introduce new capabilities without costly hardware replacement cycles. Vendors and operators that invest early in automation, telemetry, and standardized interfaces are likely to gain an advantage in total cost of ownership and service velocity.
A third trend is the widening of use-case diversity across industrial, automotive, and consumer segments, which will increase demand for tailored connectivity profiles rather than one-size-fits-all network designs. This opens commercial opportunities for private network solutions, vertical-specific service bundles, and endpoint platforms optimized for power, cost, and specialized performance. The main uncertainty lies in how quickly standards, spectrum, and regulatory frameworks will align to support these differentiated offerings at scale. Geopolitical constraints, spectrum affordability, and deployment economics could slow adoption in some regions, while more favorable conditions may enable faster commercialization elsewhere. Companies that can model these variables and adapt their architectures accordingly will be better positioned to capture value as the market matures.
Actionable Guidance for Decision Makers
For infrastructure manufacturers and technology suppliers, the priority is to design for flexibility without sacrificing performance. This means investing in architectures that can support both integrated and open interfaces, building portfolios that address a broad range of device classes and deployment scenarios, and reducing the integration cost of multi-vendor environments. Suppliers that can demonstrate lower site-level deployment complexity, efficient spectrum use, and credible interoperability will be better placed to compete in a market where cost pressures and regulatory diversity are both rising.
For investors, the most valuable signal is where capital is flowing across the stack. Interest is likely to remain strong in core modernization, virtualized and open-interface infrastructure, device platforms that expand the addressable endpoint base, and enabling technologies for backhaul, small cells, and enterprise wireless environments. Portfolio decisions should account for regional exposure, since spectrum policy, export controls, and interoperability mandates are creating uneven competitive conditions across geographies. Diversification into integration, orchestration, and specialized vertical solutions may offer more durable returns than betting solely on generic hardware cycles.
For procurement leaders and enterprise adopters, the focus should be on total lifecycle economics and service assurance rather than on headline specifications alone. Selecting wireless systems that can integrate with existing IT and operational technology environments, support evolving interface standards, and provide predictable performance across cellular, Wi-Fi, and short-range networks will reduce risk as use cases expand. Building internal capability for network management, security, and vendor coordination is increasingly as important as the equipment selection itself.
Given the speed at which spectrum decisions, deployment economics, and regulatory frameworks are evolving, decision makers benefit from maintaining a continuous view of segment-level demand, regional policy shifts, and vendor roadmaps. Detailed segmentation data, region-specific deployment economics, and company-level strategic assessments can sharpen capital allocation, product planning, and sourcing decisions in a market that is expanding rapidly but becoming more complex to navigate.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Communication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


