



Railway Expansion Joints Market: Why 5.14% CAGR and Asia Pacific Lead Reshape Strategy

Strategic Trends and Commercial Opportunities in the Global Railway Expansion Joints Market
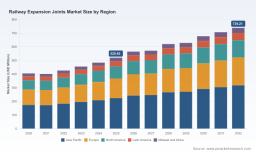
The global railway expansion joints market has transitioned from a steady demand-driven sector to a strategically dynamic space shaped by infrastructure modernization, technical specialization, and supply chain volatility. In 2025, the market crossed the 520 million USD threshold, extending a five-year trajectory that has consistently moved upward despite cyclical pressures in raw materials and project pipelines. Projections point to a compound annual growth rate of approximately 5.14 percent through 2032, a pace that signals durable expansion rather than short-term recovery. This trajectory is not uniform across geographies or applications. Instead, value creation is concentrating in segments where movement capacity, ballast retention, and certification requirements push buyers toward differentiated engineering rather than commodity procurement. Market concentration data underscores this shift: the top three and top five players together account for a meaningful share of revenue, reflecting buyer preference for suppliers with proven qualification records and global installation experience.
Pipe Joints Market
The current environment is defined by several interdependent challenges. First, raw material cost volatility continues to pressure margins, particularly for steel-intensive expansion joints exposed to fluctuating rebar and alloy benchmarks. Second, procurement cycles are lengthening in publicly funded railway programs, where certification, qualification testing, and compliance documentation can delay project timelines and compress installation windows. Third, the divergence between maintenance-driven replacement demand and new-build expansion projects is creating uneven revenue patterns across segments. Buyers are increasingly asking for components that can handle higher movement ranges, minimize ballast seepage, and maintain performance under variable weather and load conditions. These requirements are reshaping supplier selection criteria, elevating technical documentation and regional approval records to core decision factors.
For executives and investors, the implication is clear. The market is no longer a simple volume play. Growth is increasingly tied to engineering credibility, qualification breadth, and the ability to offer solutions that align with specific bridge, track, and high-speed rail requirements. Companies that rely on standardized offerings without documented performance in relevant operating conditions face mounting pressure to justify pricing and installation value. Conversely, suppliers with localized approval records, modular variants, and proven movement capacities are capturing a larger share of complex orders. The next phase of market development will be decided by how effectively participants convert technical differentiation into repeatable project wins and stable order books.
Key Drivers Shaping Market Dynamics
The expansion of railway infrastructure investment is the most visible driver in this market. Public and private operators are committing capital to track surfacing, undercutting, viaduct reinforcement, and capacity expansion, all of which increase demand for reliable expansion joints. Recent corporate capital plans illustrate this pattern, with multiple operators budgeting billions for infrastructure renewal and capacity-building projects. These investments are not cosmetic. They reflect the need to maintain network availability, reduce maintenance interruptions, and prepare corridors for higher traffic density or heavier axle loads. In practical terms, this means expansion joints are being specified not only for new alignments but increasingly for refurbishment programs where existing joints must be replaced with components that match modern movement requirements and long-term reliability expectations.
Regulatory and qualification frameworks are equally important. Approval pathways have become a competitive differentiator. Where operators require manufacturer-related product qualification or alignment with national railway specifications, suppliers with documented approvals gain a distinct advantage in sourcing decisions. This is especially true in markets where ballast bed load transfer, compliance with recognized design rules, and performance under weather and repeated load cycles are scrutinized during procurement. The effect is twofold. First, qualification becomes a barrier to entry that favors experienced players and disciplined engineering teams. Second, it raises the value of technical documentation, testing evidence, and field performance records. Suppliers that can provide clear, repeatable qualification information reduce procurement risk for operators and shorten evaluation cycles, which translates into faster conversion of project pipelines into awarded contracts.
Technological differentiation is reshaping product value. Expansion joints are moving beyond basic gap accommodation toward engineered systems that manage ballast retention, corrosion resistance, movement range, and load distribution. Certain suppliers emphasize stainless steel construction to improve durability in aggressive environments, while others focus on modular or mat-style designs that simplify installation and align with specific bridge geometries. Movable switch configurations and extended movement capacities are becoming more relevant where heavy-duty transport and variable thermal cycles create higher expansion demands. At the same time, manufacturers are increasingly tailoring product families to short-to-medium extensions versus high-range applications, allowing buyers to match joint specifications more precisely to project conditions. This specialization reduces over-engineering in simpler installations and improves fit-for-purpose selection in complex bridge and viaduct work.
PW Consulting
Supply chain and cost structure shifts are an additional pressure point. Steel and alloy prices have exhibited mixed, range-bound behavior in recent quarters, driven by raw material costs, construction demand recovery, and inventory adjustments. Rebar benchmarks have remained elevated in some regions, creating periodic margin stress for steel-intensive products. These fluctuations matter because they affect both pricing strategies and lead-time planning. Suppliers that manage material procurement more proactively, balance product mix toward higher-value engineered systems, and maintain transparent documentation on cost drivers are better positioned to preserve profitability without sacrificing competitiveness. For buyers, this environment increases the importance of total-cost evaluation, including installation complexity, maintenance expectations, and lifecycle performance rather than unit price alone.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established engineering and infrastructure suppliers, with strong representation from European manufacturers and meaningful participation from North American and Asian players. Freyssinet has built a reputation around railway expansion joints designed to prevent ballast seepage into joint gaps on bridge decks, with solutions covering movement ranges up to 900 mm and extensive global installation experience on railway structures. This positioning reflects a strategic emphasis on high-movement applications and long-term field credibility. Voestalpine Railway Systems offers rail expansion joints with movable switch rails for short to medium extensions, and a heavier-duty model engineered for transport applications with axle loads up to 30 t and extension capacity up to ±600 mm. This dual approach allows the company to address both standard trackwork and more demanding heavy-duty use cases.
In the bridge segment, MAURER provides mat expansion joints with movement capacities up to ±130 mm and load transfer via ballast bed, supported by manufacturer-related product qualification for German Federal Railways. The company's recent technical documentation update reinforces performance claims under weather and load conditions, an example of how qualification clarity and documentation discipline can strengthen a supplier's competitive position. Mageba contributes ballast-retaining railway expansion joints made of stainless steel, with models designed for railway bridges and installed by major rail operators. D.S. Brown Company brings over 50 years of experience in engineered steel and rubber products for transportation infrastructure, offering bridge expansion joint systems adaptable to railway applications. Vossloh provides bridge joints and expansion rail joints in multiple configurations, including manganese and all-rail designs, while L.B. Foster supports rail infrastructure solutions with insulated rail joints and related trackwork components. CMI Promex rounds out the field with rail expansion joints for standard and embedded track, designed for measured expansion ranges suitable to specific installation contexts.
Across this group, the clearest pattern is strategic differentiation through fit-for-purpose engineering rather than broad price competition. Leaders position around movement capacity, ballast retention, certification records, and installation experience. Some concentrate on bridge-specific requirements with documented load transfer behavior. Others emphasize heavy-duty axle loads, short-to-medium extension ranges, or material durability in corrosive environments. The result is a market where value is captured by suppliers who can demonstrate that their offerings match the operational and regulatory conditions of the target segment. This is also where buyer risk is reduced, because qualification evidence and product-specific installation guidance make evaluation more straightforward and reduce ambiguity during project planning.
Looking ahead, the market structure is likely to evolve through selective consolidation, deepening specialization, and cautious new entry. Established players with global installation footprints and approval records are well placed to absorb complex demand and expand into adjacent corridor projects. Smaller or regional suppliers may compete by targeting niche movement requirements, specific track configurations, or cost-sensitive replacement programs, but they will need credible qualification or field performance to win larger contracts. New entrants face a meaningful barrier in certification and installation track record, which favors incremental expansion over disruptive displacement. At the same time, procurement teams are becoming more deliberate, weighing total installed value, maintenance exposure, and documentation quality. This environment rewards suppliers that combine engineering clarity with reliable execution, and it pressures those that compete primarily on price without a differentiated technical story.
Forward-Looking Trends and Commercial Opportunities
One clear trend for the next three to five years is the continued shift toward application-specific expansion joints rather than generic replacements. As more rail corridors undergo modernization and operators seek to reduce maintenance interruptions, projects will increasingly call for joints with documented movement capacity, ballast retention behavior, and approval alignment with local railway requirements. This trend creates commercial opportunity for suppliers that can present clearly segmented product families and provide transparent installation and qualification guidance. The practical upside is stronger conversion rates on technically complex bids and reduced reliance on commodity price competition.
Concrete Expansion Joint Market
A second trend is the growing importance of lifecycle value in procurement decisions. Unit pricing will remain relevant, but it will be weighed against installation complexity, expected service life, corrosion and wear performance, and total maintenance burden. Stainless steel options, modular designs, and mat-style systems that simplify load transfer are likely to gain attention where operators want to limit long-term intervention. For suppliers, this means communicating performance evidence in ways that procurement teams can compare across alternatives. For investors, it suggests that margin resilience will favor companies with engineered, higher-value product mixes rather than undifferentiated volume lines.
A third trend is the continued impact of material cost volatility on pricing and project economics. Steel and alloy benchmarks may remain range-bound with periodic spikes, and procurement teams will increasingly manage this risk through earlier specification, flexible sourcing, and lifecycle cost assessments. Suppliers with disciplined material planning and transparent cost communication will have an advantage in maintaining stable pricing relationships. At the same time, operators may accelerate replacement programs when maintenance disruptions or reliability concerns become more costly than the capital investment, creating episodic demand surges tied to operational pressure rather than pure expansion.
These trends carry inherent uncertainty. Certification requirements may evolve, project pipelines can shift with budget cycles, and raw material volatility can compress margins if not managed proactively. Still, the direction of travel remains favorable for suppliers who can convert technical credibility into repeatable project wins. The commercial opportunity lies in aligning product strategy with qualification evidence, installation practicality, and lifecycle value communication, so that expansion joints are evaluated as engineered solutions rather than interchangeable components.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen product segmentation around movement capacity, ballast retention, and certification relevance. Rather than competing broadly, focus technical messaging on the applications where documented performance and approval records reduce buyer risk. Invest in clear technical documentation, installation guidance, and qualification evidence that procurement teams can use directly during evaluation. Where material costs are volatile, strengthen procurement planning and communicate cost drivers transparently to protect pricing relationships without eroding competitiveness.
For investors, the key question is whether a supplier's portfolio is aligned with higher-value, application-specific demand or dependent on commodity replacement cycles. Favor companies with diversified product families across bridge, standard track, and heavy-duty use cases, and with credible qualification or installation records that support margin resilience. Monitor how effectively management converts engineering differentiation into repeat project wins, because that is a stronger indicator of durable growth than headline order announcements.
For procurement and project leaders, the practical move is to evaluate expansion joints on total installed value and documented performance rather than unit cost alone. Specify movement requirements, load transfer expectations, and approval criteria early, and request evidence that matches the intended operating conditions. This approach shortens evaluation cycles and reduces risk in complex bridge and trackwork projects. Detailed segmentation data, regional demand patterns, and supplier-by-supplier qualification breadth can further sharpen sourcing decisions, and a comprehensive market report can help internal teams benchmark alternatives before commitments are made.
For detailed analysis of this topic, please visit the official page: Worldwide Railway Expansion Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


