



Graphene Aerogel Market 2026: Decoding the 16.52% CAGR and 637 Million USD Growth Path

Navigating the Global Graphene Aerogel Market: Strategic Trends and Commercial Opportunities
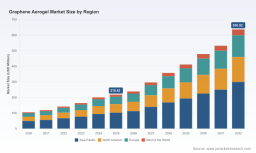
The worldwide graphene aerogel market has entered a period of accelerated expansion, transitioning from laboratory curiosity to a commercially viable material class with cross-industry applications. Valued at approximately $105.34 million in 2020, the market reached $218.42 million by 2025, reflecting a compound annual growth rate of 16.52% through 2032. By the end of the forecast period, annualized revenue is projected to approach $636.92 million. This trajectory is not merely a function of incremental demand growth; it signals a structural shift in how advanced porous materials are integrated into energy, electronics, and environmental systems.
Despite the compelling growth narrative, producers and buyers alike face persistent headwinds. First, scaling laboratory-grade synthesis to industrial volumes remains a bottleneck. Traditional supercritical drying and freeze-drying methods are energy-intensive and difficult to standardize across batches, creating quality variance that delays qualification in precision applications. Second, the supply chain for high-purity graphite precursors is tightening. As downstream demand rises, upstream concentration in specific geographic regions exposes manufacturers to pricing volatility and logistics friction. Third, end-users in regulated sectors require extensive validation before adoption. Thermal durability, long-term mechanical stability, and compatibility with existing manufacturing lines often become gatekeeping requirements that slow commercial rollout. These challenges do not negate the market's momentum; rather, they define the competitive terrain where execution discipline will determine winners.
A third inflection point lies in the evolving regulatory and trade environment. Shifts in tariff structures, export licensing requirements, and chemical classification frameworks are reshaping how raw materials and finished aerogel products move across borders. Companies that previously operated with a single-region supply model are now re-evaluating sourcing portfolios, while buyers are building redundancy into their procurement strategies. The net effect is a market that rewards flexibility, transparent compliance practices, and diversified production footprints. The question for decision-makers is no longer whether graphene aerogel will scale, but which players can navigate the intersection of technical complexity, supply chain constraints, and regulatory change most effectively.
Strategic Implications for Market Participants
Growth at this pace rarely translates into uniform opportunity. Margins, qualification timelines, and customer acquisition costs vary significantly by application and region. Producers that treat aerogel as a general-purpose material often struggle against competitors who align product specifications, processing routes, and certification support with the exact requirements of target end markets. For buyers, the key is distinguishing between early-stage promise and repeatable, supply-stable performance. The next phase of market development will separate companies that build defensible positions from those that simply ride the volume wave.
Key Drivers Shaping Market Trajectory
Several interdependent forces are accelerating adoption and reshaping competitive dynamics. Understanding these drivers is essential for evaluating where value will concentrate over the next five to seven years.
Technical Innovation and Process Maturation
The most consequential driver is the steady improvement in manufacturing scalability and property control. Researchers and commercial producers have progressively reduced the cost and complexity of creating low-density, high-surface-area structures while preserving mechanical integrity. Advances in ambient-pressure drying, template-assisted synthesis, and composite integration are narrowing the gap between bench-scale performance and factory-floor reproducibility. Equally important is the ability to tune pore structure, conductivity, and compressibility for specific applications. When aerogel can be engineered to meet thermal, electrical, or adsorption requirements without excessive over-engineering, total system cost declines and adoption becomes more practical.
This technical maturation is particularly visible in energy storage and thermal management. In battery and supercapacitor architectures, aerogel-based electrodes and intercalation layers can support faster charge transport and improved structural resilience. In thermal management, the material's low conductivity and flexibility enable insulation solutions that are difficult to achieve with conventional foams or mineral fibers. The strategic takeaway is that innovation is no longer limited to discovering new properties; it increasingly centers on making those properties accessible at scale and in forms that downstream manufacturers can integrate without major retooling.
Policy, Regulation, and Trade Environment
Regulatory clarity and trade policy are becoming decisive variables in global sourcing and investment. In Europe, the European Chemicals Agency concluded that graphene, graphene flakes, and few-layer graphene do not warrant harmonized classification for specific target organ toxicity or germ cell mutagenicity. This determination reduces a layer of uncertainty for downstream users developing formulations and components in regulated industries. It does not eliminate the need for responsible handling and product stewardship, but it does simplify the compliance narrative for many commercial applications.
At the same time, trade policy is reshaping cost structures and supply routes. The United States has moved to increase Section 301 tariffs on imports of natural graphite and synthetic graphite from China to 25%, effective January 1, 2026. Alongside this, China requires export licenses for graphite and related products with purity above 99.95% carbon and specifications for battery use, effective December 1, 2023. These measures create a more guarded environment for high-purity precursor flows, particularly for battery-related supply chains. For aerogel producers, the implication is twofold: sourcing strategies must account for tariff exposure and licensing friction, and qualification programs may need to incorporate alternative precursor routes or regional production options to maintain continuity.
Demand-Side Shifts in Energy, Electronics, and Environmental Applications
Demand is being pulled by structural needs rather than cyclical promotions. In energy storage, the push for higher power density, longer cycle life, and improved thermal safety is encouraging exploration of advanced porous materials that can supplement or replace conventional electrode architectures. In electronics and electromagnetic interference shielding, miniaturization and higher performance thresholds are driving interest in lightweight materials that combine conductivity control with mechanical flexibility. Environmental remediation represents another expanding demand channel, where high surface area and adsorption characteristics support water treatment, contaminant capture, and separation processes.
What ties these demand segments together is a common requirement: performance must be delivered within cost and integration constraints. End-users are increasingly unwilling to accept material superiority if it comes with unpredictable supply, difficult processing, or unclear total-cost economics. As a result, adoption is accelerating in channels where suppliers can provide not only the material itself, but also application-specific guidance, sample availability, and compatibility data. This shifts the competitive emphasis from product features alone to solution readiness.
Supply Chain and Cost Structure Evolution
Cost dynamics remain a central driver of market behavior. Graphite feedstock pricing has moved in response to demand expansion and regional supply concentration. For example, prices for Chinese fine-flake graphite with 95% carbon content and 300-mesh specification averaged around $1,200 per metric ton in December 2023 amid rising demand. While this figure reflects a specific grade and window, it illustrates the sensitivity of precursor economics to demand cycles and regional availability. Aerogel manufacturers that depend heavily on a narrow set of feedstock specifications can experience margin pressure when input costs shift or when preferred grades become less accessible due to export or licensing constraints.
In response, the supply chain is gradually diversifying. Producers are evaluating alternative precursor grades, blended formulations, and regional sourcing partnerships to reduce single-point exposure. At the same time, downstream buyers are increasingly factoring resilience into procurement decisions, sometimes accepting modest cost premiums in exchange for predictable availability and reduced compliance risk. This recalibration is changing how value is negotiated across the chain and encouraging longer-term supply relationships rather than purely transactional purchasing.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of specialized producers, application-focused suppliers, and regional material companies pursuing different routes to value. Rather than competing on a single dimension, leading players are building positions around product format, application alignment, and supply reliability.
Differentiated Positioning Among Established Players
The Sixth Element (Changzhou) Materials Technology Co., Ltd. operates from Changzhou, Jiangsu, China, and has developed a profile centered on graphene aerogel composite insulation materials, including blankets and felts for high-temperature thermal insulation and aerospace applications. This positioning reflects a clear strategic choice: target demanding thermal and specialty environments where performance and reliability justify premium positioning. By focusing on composite formats rather than powder alone, the company aligns more directly with end-use integration requirements in sectors where processing compatibility and thermal endurance are decisive.
ACS Material LLC, based in Alhambra, California, USA, supplies graphene aerogel powder with densities ranging from 2 to 10 mg/cm³ for research, energy storage, and thermal management applications. This format-oriented approach serves a market segment that values specification transparency, density tunability, and accessibility for development work. The strategy is well suited to customers who need material flexibility for prototyping and early-stage product design, particularly in energy storage and thermal management. It also positions the company as a provider of enabling inputs rather than finished assemblies, allowing it to serve a broader set of downstream developers.
Cheap Tubes Inc., located in Braselton, Georgia, USA, provides graphene aerogel products optimized for supercapacitors, insulation, and adsorption applications. By explicitly connecting product offerings to application categories, the company emphasizes use-case relevance over generic material supply. This is an effective way to shorten evaluation cycles for buyers who want to understand suitability before committing to larger-scale testing. In practice, application-oriented messaging can reduce the friction between material acquisition and engineering validation, especially in fast-moving development environments.
Structural Evolution in the Market
The broader market structure appears to be moving along multiple paths simultaneously. One path is consolidation around players who can combine consistent quality, application support, and supply continuity. In high-stakes sectors such as aerospace, energy storage, and regulated electronics, customers often prefer fewer, more reliable suppliers over a long list of low-cost options. This creates an incentive for producers to invest in process control, certification readiness, and customer-facing technical support.
A second path is fragmentation in research-grade and early-commercial segments, where a wider range of suppliers compete on density options, packaging, lead time, and application notes. This level of the market is important as an input channel for innovation, but it also tends to reward producers who can maintain reproducible specifications while keeping access convenient for development teams. The presence of multiple US-based and China-based suppliers illustrates how regional specialization and format differentiation can coexist within the same overall market.
A third dynamic is the potential for new entrants to emerge at the intersection of precursor supply, processing technology, and application integration. Companies that can bridge the gap between raw material economics and finished-product performance may find opportunities in niche segments where incumbents are too general in their offerings or too slow to adapt to changing compliance and trade conditions. At the same time, new entrants face real barriers in scale-up, qualification, and customer trust, meaning that success will depend on targeted positioning rather than broad market coverage.
What Differentiates Executing Players
Across these competitive patterns, several capability themes recur. Producers that can deliver repeatable density and pore characteristics, offer formats aligned with downstream processing, and navigate trade and compliance complexity are better positioned to convert demand into durable revenue. Equally important is the ability to support customer evaluation with clear technical documentation and application-relevant sample programs. In a market where performance claims are easy to make and harder to validate, evidence and consistency become competitive assets. For buyers, the operational lesson is to evaluate suppliers not only on unit price, but on the total cost of integration, qualification, and supply continuity.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 window, a few trends are likely to shape where growth concentrates and where risk accumulates.
Worldwide Organic Aerogel Market
- Application-led scaling will outpace generic volume growth. The strongest commercial momentum is expected in energy storage, electronics and shielding, and environmental remediation, where the material's properties map directly onto system-level needs. Producers that align capacity expansion with specific application requirements are more likely to capture higher-value demand than those pursuing undifferentiated volume.
- Supply chain reconfiguration will become a strategic necessity. With tariff escalation, export licensing, and regional precursor concentration all influencing cost and availability, companies will increasingly design sourcing structures around resilience. This may mean multi-region procurement, alternative precursor pathways, or closer integration with downstream customers to reduce cycle time and uncertainty.
- Regulatory clarity will lower friction in some regions while trade policy raises it in others. The absence of harmonized toxicity classification for certain graphene forms in Europe is favorable for commercial development in that jurisdiction. Meanwhile, evolving US-China trade measures and licensing requirements will continue to affect cross-border material flows. The net outlook is one of uneven terrain: opportunity is expanding, but it is not identically distributed across regions and supply routes.
These trends create actionable commercial opportunities. Manufacturers can gain advantage by doubling down on application-specific formats, investing in process consistency, and building compliance-aware sourcing strategies. Investors can focus on companies with credible scale-up roadmaps, defensible customer relationships, and exposure to demand segments where performance justifies premium economics. Procurement teams can use the current environment to negotiate more resilient supply arrangements, qualify alternative sources, and reduce dependence on single-region feedstock pathways. At the same time, risk remains. Scale-up shortfalls, quality variability, and sudden policy shifts can disrupt timelines and compress margins, especially for players with narrow supply exposure or underdeveloped customer validation capabilities.
Aerogel Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to link product development to real integration requirements. That means defining target applications early, engineering formats that fit downstream processing, and investing in the documentation and sample support that shorten customer qualification cycles. It also means building sourcing flexibility before disruptions force reactive changes.
For investors, due diligence should go beyond headline growth rates and examine the operating mechanics behind them: repeatability of production, readiness for regulated end markets, exposure to tariff and export constraints, and the depth of customer relationships beyond pilot-scale trials. Companies that can demonstrate a credible path from lab performance to reliable commercial supply are better positioned to capture long-term value.
For procurement and engineering leaders, the practical move is to treat graphene aerogel as a strategic input rather than a spot purchase. Qualify multiple sources, map tariff and licensing exposure across regions, and evaluate total cost against performance, lead time, and supply continuity. Building optionality now reduces vulnerability later, particularly in applications where qualification lead times are long and substitution is difficult.
PW Consulting
Market intelligence that combines segment-level demand trends, competitor positioning, regulatory updates, and supply chain cost dynamics can materially improve planning quality. For organizations seeking deeper segmentation detail, regional breakdowns, application-specific sizing, and tailored scenario analysis, the full PW Consulting market study provides a more granular basis for investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Aerogel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


