



Worldwide Water Soluble Pastes Market: Asia Pacific’s 6% CAGR Trajectory Explained

Global Water Soluble Pastes Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The water soluble pastes market, particularly within the electronics assembly sector, is navigating a period of structured expansion underpinned by steady revenue growth. Measured in USD millions, the market has demonstrated consistent upward momentum over the historical period from 2020 through 2025, with cumulative revenue climbing from approximately 385 million to over 512 million. The forward trajectory through the 2026 to 2032 forecast window projects continued scale, with annual revenue expected to surpass 770 million by the end of the period. This progression translates to a compound annual growth rate hovering around 6 percent, signaling a mature yet resilient demand environment rather than a speculative surge.
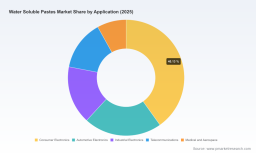
Beneath the headline figures lies a market shaped by clear structural preferences. Lead-free water soluble formulations now dominate total revenue, reflecting entrenched regulatory and manufacturing realities that have made traditional leaded variants a minority share. Application demand is heavily anchored in consumer electronics and automotive electronics, which together account for the largest revenue concentration, while industrial electronics, telecommunications, and medical or aerospace applications form substantial secondary pillars. Geographically, the Asia Pacific region commands the largest revenue contribution, followed by North America and Europe, with Latin America and the Middle East and Africa representing smaller but steadily participating slices of global demand.
Despite this orderly growth path, the industry faces several inflection points that decision makers cannot overlook. First, formulation performance is being tested by increasingly dense and miniaturized assembly requirements. As component pitch shrinks and mixed-technology boards become standard, water soluble pastes must balance high activity and reliable wetting with cleanability and residue control. Second, environmental and process compliance continues to tighten across multiple manufacturing jurisdictions. Halogen-free and low-residue expectations are no longer niche preferences; they are becoming baseline requirements that influence material selection, validation cycles, and qualification costs. Third, the supply chain for specialty chemistries and high-purity alloy materials remains sensitive to price volatility and regional capacity shifts, creating margin pressure for manufacturers that rely on single-source inputs or inflexible procurement models.
These challenges are not solely constraints; they are also markers of where innovation and commercial positioning will be rewarded. Companies that can deliver repeatable fine-pitch printability, stable performance in lead-free processes, and straightforward cleaning with deionized water are better placed to capture demand from advanced assembly environments. At the same time, the market's moderate concentration, with the top three players holding a meaningful share and the top five approaching just over half of total revenue, suggests that scale advantages exist but are not insurmountable. That leaves room for differentiated performers to gain ground through formulation specificity, application engineering support, and regional service depth.
For executives and investors, the immediate implication is that growth in this space will be earned through reliability, compliance readiness, and process compatibility rather than through broad commodity positioning. The next phase of expansion will likely favor participants who can align product portfolios with the technical demands of lead-free, increasingly miniaturized electronics manufacturing while managing input-cost exposure.
Key Demand and Supply Drivers
Several interlocking drivers are shaping the pace and direction of the water soluble pastes market. The most visible is the ongoing transition to lead-free electronics assembly. Global restrictions on lead-containing materials have made lead-free formulations the default choice across mainstream board-level and semiconductor packaging applications. This shift is not simply a compliance exercise; it has reshaped formulation chemistry, process windows, and qualification expectations. Manufacturers designing for lead-free processes need pastes that maintain strong wetting, resist graping, and produce residues that can be removed cleanly without compromising adjacent components or underfill interfaces. As a result, advanced water soluble systems have become integral to meeting both performance and regulatory expectations in modern assembly lines.
Water Soluble Fertilizers Market
Closely linked to this transition is the growing adoption of halogen-free and low-residue formulations. Environmental regulations across multiple countries are pushing electronics manufacturers toward materials that reduce hazardous substance exposure while maintaining process robustness. Halogen-free water soluble pastes are increasingly selected for applications where long-term reliability, humidity resistance, and worker safety considerations intersect. This trend is particularly relevant for high-volume consumer electronics and automotive electronics, where qualification cycles are rigorous and material consistency directly affects yield. The momentum behind halogen-free options signals a broader industry preference for materials that simplify downstream compliance and reduce the risk of failed audits or customer-specific requirements.
A second major driver is the technical demand created by finer-pitch assembly and advanced packaging formats. Surface mount technology continues to handle smaller geometries, and system-in-package designs, flip-chip interconnections, and microdispensing applications are becoming more common in high-performance devices. These applications place stringent requirements on paste printability, slump control, voiding behavior, and residue profile. Water soluble pastes engineered for ultrafine-pitch printing and controlled deposition are therefore gaining relevance not only in traditional PCB assembly but also in semiconductor packaging processes that require precise material placement and reliable joint formation. In this environment, formulations that combine high activity with manageable residue characteristics provide a practical advantage because they reduce cleaning complexity while supporting tighter process controls.
The third driver lies in end-market demand patterns and manufacturing economics. Consumer electronics continues to be a large revenue contributor because of its scale and cadence of product refreshes, which sustain steady material consumption. Automotive electronics is another pivotal demand source, driven by increasing electronic content in vehicles and the need for dependable interconnections under demanding operating conditions. Industrial electronics, telecommunications infrastructure, and medical or aerospace applications add further layers of demand, each with distinct tolerance for cost, qualification depth, and performance margins. What unites these segments is a growing preference for materials that can support high-throughput manufacturing without introducing cleaning bottlenecks or reliability risks. Water soluble systems that can be removed efficiently with deionized water, even after extended processing intervals, address a practical production concern that influences line efficiency and total cost of ownership.
On the supply side, cost structures and material availability remain important variables. Specialty fluxes, alloy powders, and purity-controlled inputs can be exposed to pricing fluctuations and regional supply constraints. At the same time, manufacturers are under pressure to maintain competitive pricing while funding formulation improvements and application support. This creates a strategic tension: participants must invest in performance-enhancing chemistry and technical service, yet they must also manage input costs and avoid sacrificing consistency. Companies that develop robust supplier relationships, diversified sourcing strategies, and formulation platforms capable of serving multiple assembly needs are better positioned to absorb these pressures.
Recent product activity reflects these dynamics. Updates to solder paste catalogs have reinforced the availability of water soluble types for lead-free, RoHS-compliant circuit board assembly, indicating that suppliers continue to align portfolios with mainstream regulatory and performance expectations. Such moves are less about dramatic market disruption and more about sustaining relevance in a market where compliance, cleaning efficiency, and print reliability are baseline expectations. In practice, the companies that stand out are those that connect product updates to specific assembly challenges, whether that means lower voiding in lead-free processes, improved print definition, or residues that remain easy to remove after storage or extended handle time.
Competitive Landscape and Leading Strategies
The competitive field in water soluble pastes is populated by a mix of established materials suppliers and specialized formulation providers, each pursuing distinct routes to differentiation. Indium Corporation offers a broad range of water-soluble solder pastes, including versatile PCB assembly formulations and ultrafine-pitch printing options for SiP designs, alongside water-wash formulations used in semiconductor packaging and microdispensing applications. Its positioning suggests a strategy centered on breadth of application coverage and performance balance, particularly where low voiding, good wetting, and controlled printing are equally important.
Electrode Paste Market
MacDermid Alpha, encompassing ALPHA and Kester brands, contributes water-soluble solder pastes aimed at semiconductor and board-level assembly. Its focus on fine-pitch printing, low voiding, and easy cleaning in lead-free processes aligns with the core requirements of high-volume electronics manufacturing. By maintaining multiple brand touchpoints and application-specific options, the company can address both mainstream assembly and more demanding packaging environments. AIM Solder pursues a similar practical orientation, offering water-soluble pastes that emphasize strong wetting, low slumping, and residues that remain cleanable with deionized water even after extended time. That kind of cleaning resilience is especially valuable for operations where boards may not be immediately processed after printing.
In the semiconductor-oriented segment, Senju Metal Industry manufactures water-soluble fluxes and pastes for wafer bumping, ball attach, and PCB reflow applications. Its presence underscores the importance of materials that can support both board-level and component-level interconnection processes. Heraeus Electronics adds a European perspective with water-soluble pastes designed for halogen-free, fine-pitch printing in SiP, flip-chip, and ultrafine applications, where low voiding and good cleanability are central value propositions. Henkel, through its Loctite brand, provides water-washable and soluble pastes with halogen-free, temperature-stable formulations that support humidity resistance and high-activity performance. This breadth allows the company to serve customers who need materials that perform consistently across varied environmental and process conditions.
Smaller or more specialized players also play meaningful roles. Inventec Performance Chemicals delivers water-soluble solder pastes that emphasize exceptional wetting, reliable joints, and easy deionized water cleaning for lead-free SMT printing and soldering. FCT Solder focuses on water-soluble lead-free options with strong printability, wetting, and low graping characteristics, alongside warm-water clean residues that simplify process handling. Qualitek International offers Delta series water-soluble pastes for both Sn/Pb and lead-free SMT assemblies, with formulations oriented toward print definition, high tack, and easy cleaning. SHENMAO Technology rounds out the field with a full line of water-soluble solders and fluxes for SMT and IC packaging applications, reinforcing the importance of regional manufacturing depth and broad product availability.
What separates leading players is not merely product presence but the ability to translate formulation capabilities into application-specific advantages. The most effective strategies tend to combine several elements: formulation stability for lead-free and halogen-free requirements, print performance suited to fine-pitch and mixed-technology boards, residue behavior that simplifies cleaning, and technical support that helps customers qualify materials faster. Suppliers that can demonstrate consistent results across these dimensions often gain preference in environments where downtime, rework, and validation delays carry significant cost.
The market structure suggests continued differentiation rather than uniform consolidation. While the leading group holds a meaningful share, the field remains wide enough for specialized entrants and regional players to compete on performance, service, or price. Over time, the likely evolution will be a layered landscape: large multi-brand suppliers will continue to cover broad application portfolios, while focused providers may gain traction in niche areas such as ultrafine-pitch printing, semiconductor packaging, or regional lead-free compliance needs. New entrants will need to bring something concrete to the table, whether that is a formulation advantage, a cleaner process profile, or a stronger application engineering capability. Price competition will persist, but the more durable competitive advantage will come from reducing total process friction, not simply lowering unit cost.
Future Trends and Commercial Implications
Over the next three to five years, the water soluble pastes market is likely to be shaped by three reinforcing trends. The first is deeper entrenchment of lead-free and halogen-free formulations as default materials rather than special cases. As qualification standards mature and customer expectations stabilize around environmentally compliant materials, the competitive edge will shift from proving compliance to demonstrating process reliability within compliant formulations. Suppliers that can provide repeatable performance across lead-free chemistries, with predictable wetting and cleanability, will be better positioned to secure long-term supply agreements in high-volume segments.
The second trend is the expanding relevance of advanced packaging and fine-pitch assembly requirements. As devices become more integrated and board real estate more constrained, material behavior at small geometries will matter more than ever. Water soluble pastes that support ultrafine-pitch printing, controlled deposition, and low voiding will see continued demand from both PCB assembly and semiconductor packaging applications. This trend also creates an opportunity for suppliers to bundle material offerings with process guidance, printing recommendations, and cleaning protocols, turning product sales into broader process support engagements.
PW Consulting
The third trend is the growing emphasis on total cost of ownership rather than sticker price alone. Manufacturers are increasingly attentive to cleaning time, residue-related reliability risk, storage stability, and rework exposure. Water soluble systems that can be removed efficiently with deionized water, even after delays, and that maintain consistent performance through typical production intervals will be favored in cost-sensitive but quality-driven environments. This creates commercial opportunity for suppliers that can quantify process benefits in operational terms, such as reduced cleaning burden, fewer defect-driven interruptions, or smoother qualification cycles.
At the same time, uncertainty remains. Regulatory expectations can continue to tighten, and regional differences in material acceptance may complicate global product strategies. Input-cost volatility and supply continuity for specialty materials could pressure margins, especially for participants with limited sourcing flexibility. In addition, demand growth will not be uniform across applications or regions, meaning that portfolio alignment and regional execution will matter as much as overall market expansion. Companies that treat these uncertainties as planning variables, rather than external noise, will be better prepared to adjust formulations, service models, and commercial terms as conditions evolve.
Strategic Guidance for Decision Makers
For manufacturers, the priority is to align material selection with the practical demands of lead-free, increasingly miniaturized assembly. That means evaluating water soluble pastes not only on baseline performance but also on print definition, voiding behavior, residue cleanability, and stability over typical storage and handling intervals. Building qualification pipelines around formulations that support fine-pitch printing and straightforward deionized water cleaning can reduce process friction and shorten the path to reliable volume production. Supplier partnerships should be judged on application support and consistency as much as on unit pricing.
For investors, the most compelling exposure lies in participants that combine compliance-ready chemistry with differentiated performance in high-growth applications such as consumer electronics, automotive electronics, and advanced packaging. Business models that rely on broad commodity positioning without clear technical differentiation face greater risk in a market where cleaning efficiency, reliability, and regulatory alignment increasingly determine purchasing decisions. Monitoring portfolio updates, formulation focus, and application-specific claims can provide early signals about which players are likely to defend or expand their positions.
For procurement and supply chain leaders, the strategic task is to balance cost control with resilience. Diversifying approved materials where possible, securing visibility into lead-free and halogen-free compliance status, and evaluating total process cost rather than paste price alone can improve operational stability. Where feasible, favor suppliers that can demonstrate consistent cleaning performance and provide documentation or technical support that simplifies downstream validation. In a market where the top five players account for just over half of revenue, there is room to structure sourcing strategies that preserve optionality while maintaining performance standards.
Detailed regional splits, application-level revenue breakdowns, and company-specific positioning data can sharpen these decisions further. The broader market signals are clear, but the most useful next step is to connect them to the specific product categories, end-use segments, and regional conditions that shape individual procurement and investment choices.
For detailed analysis of this topic, please visit the official page: Worldwide Water Soluble Pastes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


