



Why Corporate LMS Adoption Is Leaving Legacy Systems Behind Through Cloud, SMEs and APAC Expansion in a $44.9B Market

The Worldwide Corporate LMS Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global corporate learning management system (LMS) market has transitioned from a mature support function into a strategic imperative for enterprise talent development. Valued at approximately $9.5 billion in 2020, the market expanded steadily through the mid-2020s, crossing the $16.7 billion threshold by 2024 and reaching an estimated $18.5 billion in 2025. Growth is projected to accelerate through the end of the decade, with the market expected to surpass $20.4 billion in 2026 and continue scaling toward $24.6 billion by 2027, $25.6 billion by 2028, $30.6 billion by 2029, $36.6 billion by 2030, $40.9 billion by 2031, and ultimately approaching $44.9 billion in 2032. This trajectory reflects a compound annual growth rate of roughly 13.51 percent across the 2026 to 2032 forecast horizon. The expansion signals a structural shift: learning platforms are no longer treated as administrative cost centers but as integral components of workforce transformation, compliance management, and competitive differentiation.
Despite the favorable growth trajectory, several structural challenges are reshaping vendor strategies and buyer expectations. First, data governance and privacy compliance have become non-negotiable constraints. Corporate LMS platforms must navigate complex regulatory environments, including GDPR Article 32 requirements for pseudonymization and encryption when processing employee training data, as well as CCPA mandates that grant California residents opt-out rights for personal data collected through LMS analytics. These obligations force vendors to embed privacy-by-design architectures and transparent data handling protocols, which elevate development costs and slow feature deployment cycles. Second, the cost structure surrounding cloud hosting and specialized labor is tightening margins for mid-tier providers. AWS EC2 pricing for LMS hosting typically ranges between $0.10 and $0.25 per hour for m5.large instances used in scalable deployments, while the average annual salary for LMS administrators in the United States hovers around $85,000. Together, these inputs pressure vendors to optimize infrastructure utilization and streamline platform administration without sacrificing user experience. Third, the market is experiencing a concentration of influence among a handful of scaled players, yet fragmentation remains across niche capabilities such as collaborative content creation, partner enablement, and industry-specific compliance workflows. This duality creates both a standardization pull and a customization demand, leaving enterprises to weigh integration simplicity against functional depth.
The current inflection point is defined by expectations for intelligent personalization, seamless HR ecosystem integration, and measurable skill outcomes rather than mere course completion. Vendors that treat the LMS as a static repository will struggle to retain enterprise buyers, while those that align learning delivery with real-time workforce analytics and regulatory readiness will capture disproportionate share.
PW Consulting
Key Growth Drivers
Technological Innovation and AI-Enabled Learning Experiences
Artificial intelligence has moved from experimental add-on to core architecture in modern corporate LMS platforms. Generative AI capabilities now power adaptive learning paths, content synthesis, and competency-based recommendations that adjust dynamically based on role, performance signals, and skill gaps. Vendors are embedding these capabilities directly into learning workflows rather than offering them as peripheral tools. For example, the introduction of generative AI features for personalized learning paths within enterprise learning suites has reduced manual curriculum design effort and accelerated time-to-competency for large workforces. In parallel, AI-assisted content creation tools have begun to compress course development cycles, enabling organizations to scale training production without linearly expanding L&D headcount. The strategic implication is clear: platforms that can convert raw learning signals into actionable development plans will command premium positioning, while generic content aggregators will face margin compression.
Policy and Regulatory Pressure as a Demand Catalyst
Regulatory compliance continues to be a durable demand driver, particularly in sectors with stringent training mandates and cross-border workforce operations. Privacy frameworks such as GDPR Article 32 and CCPA shape how LMS data is stored, processed, and shared, compelling vendors to invest in encryption, pseudonymization, and auditable access controls. Beyond privacy, the adoption of privacy information management standards like ISO/IEC 27701 provides a structured approach to handling employee learning data responsibly, which has become a differentiator in procurement evaluations. In practice, compliance is no longer a checkbox; it is a design requirement that influences platform architecture, deployment models, and customer trust. Enterprises operating across multiple jurisdictions increasingly favor LMS solutions that can centralize governance while supporting regional data handling rules, creating opportunities for vendors that can demonstrate both technical rigor and operational transparency.
Customer Support Training Software Market
Demand-Side Shifts in Corporate Learning Behavior
Enterprise learning behavior has fundamentally changed. Organizations are moving away from one-size-fits-all training catalogs toward skills-based development models that align learning with workforce planning, internal mobility, and performance outcomes. Collaborative learning models are gaining traction as companies recognize that employee-generated content and peer-led upskilling can scale faster than top-down course development. Adoption of collaborative LMS environments that enable employee-generated content and connect with collaboration tools has been evident in recent client engagements, including global upskilling programs for large consumer brands. Mobile-first design, gamification, and microlearning formats are also reshaping engagement patterns, especially for field teams and deskless workers who require on-demand access to training outside traditional classroom settings. These behavioral shifts reward platforms that prioritize usability, social interactivity, and just-in-time learning delivery over bulky administrative interfaces.
Cost Structure and Deployment Economics
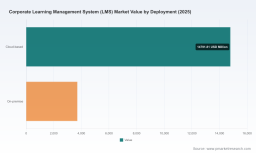
The economics of LMS deployment are evolving as cloud maturity lowers entry barriers while specialized operational costs remain elevated. Cloud-based deployments have become the dominant preference for scalability and reduced infrastructure overhead, yet hosting costs and administrative labor still influence total cost of ownership. Scalable cloud hosting for LMS workloads, such as AWS EC2 m5.large instances, typically ranges from $0.10 to $0.25 per hour, and enterprise deployments must account for load balancing, storage growth, and integration maintenance. On the personnel side, specialized LMS administration roles carry meaningful salary expectations, with U.S. administrators averaging around $85,000 annually. The resulting pressure is pushing vendors to deliver stronger automation, simplified reporting, and embedded analytics that reduce manual oversight. Buyers, meanwhile, are weighing the trade-off between fully managed cloud environments and controlled on-premise deployments where data residency and customization requirements dominate. This economic reality is accelerating demand for platforms that combine elastic cloud scalability with operational efficiency features, including automated provisioning, self-service configuration, and intuitive admin dashboards.
Competitive Landscape and Leading Strategies
The corporate LMS market is shaped by a mix of established HCM suites, specialized learning platforms, and AI-focused entrants, each pursuing distinct strategic positions. Cornerstone OnDemand offers a comprehensive LMS built around AI-driven content recommendations, compliance tracking, and HR system integration, reinforcing its positioning as an end-to-end talent development platform. SAP provides enterprise-grade learning through its SuccessFactors ecosystem, emphasizing employee development, skills management, and virtual classroom capabilities, while also extending its footprint through acquired assets such as an LMS offering with pre-built course libraries, compliance training, and analytics tailored for sales and customer service teams. Workday integrates learning directly into its HCM suite, focusing on skills-based learning paths and personalized employee development, which aligns tightly with organizations seeking unified workforce data. Oracle delivers adaptive learning, content curation, and HCM Cloud integration through its learning cloud offering, appealing to enterprises that prioritize scale and ecosystem cohesion.
Beyond the suite players, specialized vendors are carving out differentiation through AI-native experiences, collaboration models, and targeted use cases. Docebo positions itself around AI-powered learning experiences, social learning features, and multi-tenant architecture designed for large corporations, and it has continued to expand its creative tooling by launching an AI content creation capability integrated into its LMS platform. TalentLMS emphasizes cloud-based corporate training with gamification, course e-commerce, and mobile-first design, and it has reinforced enterprise trust through security certifications such as SOC 2 Type II compliance. LearnUpon focuses on compliance, partner training, and sales enablement with multi-portal capabilities, while Absorb LMS targets enterprise training management through automation, e-commerce, and reporting features. 360Learning differentiates through collaborative learning that supports employee-generated content and integrations such as Microsoft Teams, and it has translated that positioning into enterprise wins for global upskilling initiatives. Together, these players illustrate a market where value is increasingly defined by how effectively a platform connects learning, work context, and measurable skill outcomes.
Strategic positioning is also being reshaped by partnerships and ecosystem integration. Integrations that connect learning platforms with collaboration and productivity tools, such as the partnership between Cornerstone OnDemand and Microsoft Viva Learning, highlight how LMS vendors are embedding learning into daily workflows rather than isolating it in a separate portal. This convergence suggests a market trend toward workflow-anchored learning, where platforms compete on seamless experience and context-aware content delivery more than on catalog size alone. At the same time, consolidation pressure remains: large suites continue to absorb niche capabilities, while independent vendors defend differentiation through speed, UX, and vertical specialization. New entrants are likely to challenge incumbents in AI-assisted content production, skills inference, and compliance automation, but scaling trust and enterprise integration depth will remain demanding barriers.
E-learning Corporate Compliance Training Market
Future Trends and Commercial Opportunities
Over the next three to five years, the corporate LMS market is likely to be defined by three interrelated trends. First, AI will become the primary mechanism for learning personalization and content operations. Expect broader adoption of adaptive learning paths, automated content generation, and skills inference that maps learning activities to workforce planning data. The commercial opportunity lies in platforms that can demonstrate measurable productivity gains from reduced course development time and improved skill alignment, especially for enterprises managing large, distributed workforces. Second, learning platforms will increasingly function as workflow-integrated skill orchestration layers rather than standalone training portals. As organizations consolidate HR, performance, and learning data, LMS solutions that integrate directly with collaboration tools and HCM ecosystems will gain preference, creating opportunities for vendors that can deliver context-aware learning within everyday work environments. Third, compliance and privacy governance will become deeper differentiators. Enterprises operating under multi-jurisdiction data rules will favor platforms that can prove strong encryption, pseudonymization, and auditable data handling practices, while also supporting privacy management standards relevant to learning data.
These trends create clear commercial openings for vendors and buyers alike, but uncertainty remains. Rapid AI adoption may outpace internal governance capabilities, leading to content quality concerns and skill measurement challenges if models are not carefully supervised. Cost volatility in cloud infrastructure and specialized talent can strain deployment economics, particularly for organizations pursuing ambitious scale without proportional operational maturity. Finally, as suites consolidate capabilities, independent vendors will need to defend defensible niches or deliver materially superior user outcomes to maintain pricing power.
Strategic Recommendations for Decision-Makers
For enterprise buyers evaluating LMS investments, prioritize platforms that connect learning delivery to skills data, workflow integration, and compliance readiness rather than catalog breadth alone. Assess how well a solution integrates with existing HCM and collaboration tools, how transparently it handles employee data under applicable privacy obligations, and whether its administration model reduces ongoing operational burden. For investors and strategic partners, focus on vendors with credible AI-enabled content and personalization capabilities, strong ecosystem integration roadmaps, and demonstrable traction in enterprise-scale deployments. Vertical specialization, security certifications, and measurable customer outcomes will be key indicators of durable differentiation. For platform vendors and service providers, the opportunity lies in reducing friction across content creation, deployment, and measurement while strengthening governance features that satisfy cross-border privacy demands. Aligning product roadmaps with workflow-anchored learning and cost-efficient cloud operations will be essential to competing as the market scales. For decision-makers seeking a deeper view of segmentation dynamics, regional deployment patterns, and customized scenario planning, the full research report provides extended data and tailored recommendations to support precise commercial strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Corporate Learning Management System (LMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


