



Wireless Communication Intelligent Module Market: Why 13.5% CAGR Reshapes Strategy

The Wireless Communication Intelligent Module Market: Navigating the Next Wave of Connectivity Growth
1. Market Landscape and Core Challenges
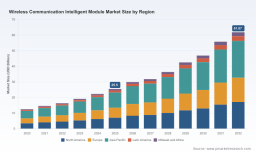
The wireless communication intelligent module market has entered a phase of sustained, high-velocity expansion. From 2020 through 2025, the sector compounded at a steady pace, crossing the twenty-five billion dollar threshold in the base year before accelerating into the forecast window. The growth trajectory points toward a double-digit compound annual growth rate through 2032, with revenue projections approaching sixty-two billion dollars by the end of the decade. This expansion reflects a structural shift rather than a cyclical upturn: intelligent modules are transitioning from peripheral connectivity components to core architectural elements in connected products across multiple verticals.
Geographic distribution of revenue reveals a market that is simultaneously mature in developed economies and rapidly scaling in emerging regions. Asia Pacific continues to generate the largest share of global revenue, driven by manufacturing density, consumer electronics demand, and accelerated industrial automation. North America and Europe maintain substantial, stable contributions, supported by automotive adoption, enterprise IoT deployments, and regulated connectivity standards. Latin America and the Middle East and Africa, while smaller in absolute terms, are expanding as infrastructure investment and digital transformation initiatives create new monetization pathways for wireless intelligent modules.
Technology segmentation further illustrates where value is concentrating. Cellular IoT dominates the technology mix, reflecting the broad applicability of licensed-band connectivity for mission-critical, mobility-heavy, and long-range deployments. Wi-Fi and Bluetooth remain essential for short-range, high-throughput, and cost-sensitive applications, particularly in consumer and enterprise environments. Low-power wide-area networks and satellite or ultra-wideband technologies occupy smaller but strategically important positions, enabling niche use cases in remote monitoring, asset tracking, and specialized positioning scenarios. On the application side, automotive and transportation represent the largest demand pool, followed by industrial IoT and consumer electronics. Smart city and utilities, along with healthcare, contribute meaningful but comparatively narrower revenue streams, each with distinct regulatory, reliability, and integration requirements.
Several structural challenges are shaping the market's inflection points. First, the competitive landscape is moderately concentrated, with a small group of established players accounting for the majority of global revenue. This concentration creates both pricing discipline and barriers for newcomers, while also intensifying pressure on incumbents to differentiate through performance, certification breadth, and application-specific optimization. Second, the industry is navigating a transition from volume-driven growth to value-driven design. Customers increasingly demand modules that integrate processing capability, edge intelligence, security features, and multi-standard interoperability rather than standalone connectivity silicon. This shift requires deeper engineering collaboration, longer qualification cycles, and more sophisticated lifecycle management. Third, supply chain and infrastructure dynamics are introducing new cost and timing variables. Rising material and deployment costs in adjacent infrastructure segments, including fiber and broadband construction, indirectly influence the economics of network-dependent modules by shaping rollout timelines and total cost of ownership for end customers.
These pressures do not diminish the market's growth potential; rather, they redefine where competitive advantage will be earned. Companies that align product roadmaps with regulatory momentum, application-specific reliability needs, and cost-aware design will be better positioned to capture share as the market matures. Understanding these inflection points is essential for any organization evaluating product strategy, procurement planning, or investment allocation in the wireless intelligent module space.
2. Key Drivers Shaping Market Trajectory
The market's expansion is not being pulled by a single force. Instead, several interlocking drivers are reinforcing each other, creating a compounding effect on demand, product evolution, and competitive behavior.
PW Consulting Information & Electronics Research Center
Technical innovation remains the most visible driver. Intelligent modules are increasingly defined by their ability to combine connectivity with on-device processing, improved power efficiency, and multi-protocol support. The emergence of reduced-capability cellular variants, such as RedCap, illustrates how the industry is expanding the addressable design space between full-featured 5G modules and low-bandwidth alternatives. These intermediate solutions enable manufacturers to deploy richer sensing, telemetry, and edge-computing functions without the cost and power profiles of flagship cellular platforms. Similarly, the integration of positioning, short-range radios, and cellular capabilities into unified intelligent module architectures is reducing integration complexity for OEMs and system integrators. The practical effect is faster time to market for connected products and a broader set of applications that can justify wireless connectivity in previously cost-sensitive or power-constrained contexts.
Regulatory and spectrum policy dynamics are another powerful catalyst. Authorities in key markets are altering the operating environment in ways that directly affect module demand and design choices. Recent rule changes aimed at easing technology transitions from legacy networks to IP-based infrastructure are reducing friction for operators and enterprises preparing for next-generation connectivity. Parallel efforts to expand the commercial spectrum pipeline create longer-term optimism around capacity, coverage, and new service models that can rely on wireless intelligent modules as enabling hardware. In specific regions, certification pathways and regulatory approvals are also becoming more structured, which helps module suppliers plan product lifecycles and gives end customers greater confidence in long-term support. At the same time, ongoing work to modernize spectrum sharing and allocate mid-band spectrum for advanced wireless services is shaping which standards and frequency bands module developers prioritize in their roadmaps.
Demand-side behavior is evolving as enterprises and consumers reassess what connected products must deliver. Purchasing decisions are increasingly influenced by total cost of ownership, reliability under real operating conditions, and the ability to support future feature upgrades without hardware replacement. In automotive and transportation, connectivity is no longer limited to infotainment or basic telemetry; it is becoming integral to fleet optimization, safety-related communications, and infrastructure interaction. In industrial IoT, the emphasis is shifting toward modules that can withstand harsh environments, maintain secure and deterministic communication, and support integration with analytics and automation workflows. Consumer electronics demand continues to reward compact, energy-efficient, and multi-standard solutions that can serve diverse usage scenarios without fragmenting bill-of-materials complexity. These preferences are pushing module suppliers to offer more application-tailored configurations, reference designs, and certification packages rather than generic connectivity components.
Supply chain and cost structure changes are adding both friction and opportunity. On one hand, input cost volatility and infrastructure deployment pressures in adjacent segments can complicate planning for network-dependent products. Rising material and labor costs in broadband and fiber deployment, for example, can influence rollout pace and indirectly affect the timing of demand for certain connectivity modules. On the other hand, these pressures are encouraging more disciplined design practices, including greater use of standardized form factors, platform-based development, and supplier partnerships that can share qualification risk. Companies that can stabilize lead times, manage component sourcing across regions, and provide clear migration paths between technology generations are gaining trust in segments where downtime or redesign cost is unacceptable.
Taken together, these drivers point to a market in which product excellence, regulatory awareness, and application-specific value creation matter as much as raw connectivity performance. Players that treat intelligent modules as part of a broader system solution, rather than as commoditized radio components, are likely to capture disproportionate value as demand broadens and matures.
3. Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of global specialists, region-rooted scale players, and operator-affiliated or diversified technology firms. The leading companies share a common strategic imperative: build credible application coverage while differentiating on reliability, certification depth, platform integration, and lifecycle support.
Worldwide Wireless Communication Systems Market
Several established players have anchored their positions through broad cellular IoT portfolios and extensive certification footprints. These companies typically compete on the strength of their product breadth across 5G, LTE, low-power wide-area, and positioning technologies, as well as their ability to support automotive, industrial, and enterprise use cases with pre-validated designs. Their advantage often lies in offering customers a predictable migration path across generations, reducing qualification risk, and maintaining long-term availability for deployed systems. In practice, this means leading module suppliers are investing not only in silicon selection but also in firmware support, security frameworks, and regional compliance packages that make it easier for OEMs to scale across markets.
Other strong competitors have built differentiation through specialization. Some focus on high-reliability and security-oriented modules for industries where failure is not an option, emphasizing robust architectures, traceability, and certification for demanding environments. Others concentrate on cost-effective cellular and wireless solutions that address price-sensitive IoT, machine-to-machine, and smart applications, using lean product structures and efficient manufacturing to compete on value. A further group emphasizes embedded wireless modules for consumer electronics, industrial equipment, and automotive applications, leveraging integration expertise and compact form factors to serve design-constrained products. Operator-affiliated providers add yet another angle, drawing on network relationships and shipment scale in cellular IoT to support integrated connectivity solutions.
Recent product and market activity underscores how competition is evolving from catalog expansion to targeted, application-driven launches. In early 2026, multiple companies introduced or expanded 5G-capable modules and platform integrations designed for specific deployment contexts. New 5G NR sub-6 module series with platform-based architectures and railway-ready variants signaled growing attention to mobility, public-transport, and specialized communication standards. Parallel expansions in reduced-capability 5G portfolios reflected efforts to capture mid-tier use cases that need more capability than legacy low-power options but do not require full flagship performance. At the same time, flagship fixed-wireless and CPE-oriented solutions combining advanced 5G modules with high-performance processor platforms showed how module suppliers are increasingly positioning themselves within broader system-level solutions rather than selling connectivity in isolation.
Certification and market-access moves are equally important. Securing regional approvals for LTE Cat 1 bis and similar efficiency-focused modules illustrates how suppliers are building out addressable markets in geographies where cost, power, and coverage trade-offs favor leaner cellular options. Trade show showcases featuring next-generation IoT modules, AI-oriented platforms, and advanced 5G connectivity further highlight the industry's emphasis on embedding intelligence and future-proofing designs for evolving workloads. Collectively, these developments suggest a market where competitive advantage is being earned through a combination of technical readiness, regional compliance, and the ability to align module capabilities with application roadmaps.
Looking at the broader structure, the market appears to be moving toward selective consolidation in certain segments and continued fragmentation in others. In high-volume, standardized segments, scale, cost efficiency, and certification breadth will reward larger, well-resourced players. In specialized or vertically demanding applications, differentiation through reliability, integration, and domain expertise can sustain smaller or more focused competitors. New entrants face a real barrier in certification lead times, supply chain credibility, and the need to demonstrate long-term support, but targeted opportunities remain in emerging applications, region-specific requirements, and architectures that combine connectivity with edge intelligence in novel ways. The most resilient strategies are likely those that balance scale with specialization, allowing companies to serve broad demand while retaining the flexibility to win in higher-value niches.
4. Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market will likely be shaped by three interlocking trends. First, intelligent modules will increasingly be evaluated as integrated system enablers rather than radio components. Buyers will expect stronger combinations of connectivity, processing efficiency, security, and application-specific certification in a single design path. This trend favors suppliers that can offer cohesive platforms and reference architectures, and it raises the importance of firmware, lifecycle management, and migration planning.
Second, the spectrum and regulatory environment will continue to influence product priorities. Policy moves that ease network modernization and expand commercial spectrum access should support long-term demand for advanced wireless modules, while regional certification and sharing rules will keep shaping which standards and bands receive the most engineering focus. Companies that monitor regulatory timelines and align product roadmaps accordingly will be better positioned to capture emerging opportunities without costly redesigns.
Third, application demand will keep diversifying in ways that reward tailored solutions. Automotive and transportation, industrial IoT, and consumer electronics will remain core growth engines, but the most interesting margin opportunities may come from specialized deployments where reliability, power constraints, or integration complexity create room for higher-value module designs. Smart city, utilities, and healthcare will contribute incremental but strategically meaningful demand, especially where secure, dependable connectivity is non-negotiable.
These trends carry both opportunity and risk. On the opportunity side, broader intelligent module adoption opens the door to platform-based revenue models, longer customer relationships, and cross-selling into security, positioning, and edge-processing add-ons. On the risk side, input cost volatility, infrastructure deployment delays, certification bottlenecks, and the ongoing concentration of share among leading players can compress margins and raise entry barriers. Organizations that plan for these dynamics by diversifying supply, prioritizing application-relevant differentiation, and investing in regulatory readiness will be better prepared to convert market growth into durable commercial advantage.
5. Strategic Implications for Decision-Makers
For manufacturers and product leaders, the near-term priority is to align module selection with application realities rather than treating connectivity as a commodity input. The most effective strategies typically combine platform-based development, proactive certification planning, and clear migration paths across technology generations. Where possible, companies should evaluate suppliers not only on unit cost but also on qualification support, regional compliance coverage, power-performance balance, and the ability to support future feature upgrades without full hardware redesign.
For investors, the market offers a nuanced picture. Growth is robust, but value creation is increasingly concentrated in players that can combine scale with application-specific differentiation and disciplined lifecycle management. Due diligence should focus on product roadmaps, certification momentum, supply chain resilience, and exposure to both high-volume standards and specialized high-reliability segments. Companies that can demonstrate repeatable wins in demanding applications while maintaining cost competitiveness are likely to command more durable positioning than those competing primarily on price in commoditizing segments.
WiFi Modules Market
For procurement and procurement-led organizations, the strategic task is to balance cost, availability, and long-term support risk. Multi-source strategies, clear technical requirements for security and reliability, and early engagement with suppliers on regional certifications can reduce exposure to lead-time shocks and redesign costs. Establishing performance and compliance criteria before specification freezes helps ensure that module choices support both immediate deployment goals and future scalability.
Given the pace of product launches, regulatory activity, and application expansion, staying current with detailed segment data, competitive moves, and region-specific requirements is increasingly important. Deeper analysis of subsegments, technology transitions, and supplier-by-supplier positioning can help decision-makers refine product roadmaps, investment theses, and sourcing strategies with greater precision. For those seeking a fuller picture of market sizing by segment, competitive dynamics, and scenario-based guidance, the complete PW Consulting report provides the structured detail needed to support more granular planning decisions.
For detailed analysis of this topic, please visit the official page: Wireless Communication Intelligent Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


