



Worldwide Dryer Refurbishment Repair Service Market: Why 4.6% CAGR Redefines Value

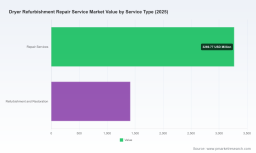
Worldwide Dryer Refurbishment & Repair Service Market: Strategic Shifts and Commercial Opportunities (2026–2032)
The dryer refurbishment and repair service market has matured into a resilient, operationally critical segment of the broader industrial and commercial equipment lifecycle ecosystem. Valued at 4.68 billion USD in 2025, the market has expanded from 3.75 billion in 2020, reflecting a compound annual growth rate of 4.6 percent through the 2026–2032 forecast horizon. This trajectory underscores a structural shift: organizations are increasingly optimizing existing assets rather than pursuing full capital replacement. The market is projected to approach 6.41 billion by 2032, driven by aging equipment fleets, supply chain recalibrations, and a growing preference for service-led value retention. Yet this expansion is neither automatic nor uniform. The sector stands at an inflection point where operational efficiency, regulatory compliance, and service model innovation will determine which players capture margin and scale.
Three structural challenges are reshaping competitive dynamics. First, the talent constraint in specialized field service has intensified cost pressures and limited deployment flexibility, particularly for complex rotary and industrial dryer systems requiring certified technicians. Second, fragmented service standards and varying regional compliance requirements create operational friction, especially for multinational operators seeking consistent quality across jurisdictions. Third, the procurement mindset is shifting from reactive breakdown maintenance to predictive, outcome-based service contracts, forcing traditional repair providers to rethink pricing, capability deployment, and customer engagement. These pressures are not merely operational; they are redefining value capture across the service chain.
For decision-makers, the implication is clear. The refurbishment and repair space is no longer a peripheral support function but a strategic lever for total cost of ownership optimization, uptime assurance, and sustainability alignment. Organizations that recognize this transition and align their service strategies accordingly will be better positioned to navigate the next five years of market evolution.
Market Drivers: Technology, Regulation, Demand, and Cost Architecture
Technology Innovation and Predictive Service Integration
Digital diagnostics, remote monitoring, and modular repair frameworks are redefining what refurbishment and repair can deliver. Advanced sensor integration and condition-based monitoring allow service teams to identify wear patterns, thermal inefficiencies, and mechanical degradation before failure occurs. This shift is particularly evident in rotary dryer applications, where alignment, seal integrity, trunnion wear, and drum shell deformation directly influence throughput and energy consumption. Providers that combine field diagnostics with engineering-grade retrofits are converting episodic repairs into lifecycle optimization engagements. The result is a more predictable service cadence, reduced unplanned downtime, and a stronger value proposition for operators managing high-utilization assets.
Technology also enables more precise parts matching and refurbishment sequencing. Reconditioned components, when validated through standardized testing and quality protocols, can extend asset life without compromising performance. This capability matters as original equipment availability becomes less predictable in certain categories, and as operators seek to balance lead-time risk against capital expenditure. Service providers that invest in machining, shell repair, and precision realignment capabilities are increasingly positioned as de facto lifecycle partners rather than break-fix vendors.
Policy and Regulatory Pressure as a Service Catalyst
Regulatory expectations around safety, emissions, and operational compliance are accelerating demand for certified refurbishment and repair practices. Industrial environments, in particular, require field teams to operate under stringent safety frameworks and documented procedures. Certified alignment, seal replacement, gear and trunnion work, and drum shell repairs are no longer optional best practices; they are increasingly tied to operational licensure, insurance expectations, and corporate risk management. In parallel, the broader push toward resource efficiency and asset circularity is reinforcing the economic case for refurbishment over replacement, especially when refurbished units carry warranty coverage that mitigates performance risk.
Compliance-oriented service models also create differentiation. Providers that maintain documented repair procedures, standardized quality checks, and certified field teams can serve regulated sectors more effectively and command premium positioning. As safety and quality expectations rise across industrial and commercial applications, procedural rigor becomes a competitive moat.
Demand-Side Behavior: From Ownership to Outcome
Customer behavior is moving toward service models that prioritize uptime, predictability, and cost control over isolated repair transactions. In commercial laundry and institutional settings, operators are managing high-cycle equipment where malfunction directly affects throughput, customer experience, and revenue continuity. This reality is driving demand for preventive maintenance, rapid response networks, and genuine parts supply chains that reduce variability in repair outcomes. Brand-agnostic service coverage is gaining relevance because many facilities operate mixed equipment fleets and value single-point accountability over manufacturer-restricted service paths.
Residential and light commercial segments exhibit a similar pattern, albeit at a different scale and complexity. Consumers and property operators increasingly expect reliable, transparent service with clear parts replacement protocols and consistent quality. The emphasis is shifting from lowest initial cost to long-term dependability, particularly in multi-unit residential, hospitality, and laundromat environments where repeat failures carry high operational and reputational costs.
Supply Chain and Cost Structure Realignment
Labor intensity remains a defining feature of the dryer repair and refurbishment sector. On-site diagnostics, machining, component reconditioning, and field installation rely heavily on skilled human execution, which keeps labor economics at the center of margin structure. At the same time, material availability, reconditioning throughput, and logistics for specialized parts influence service response times and cost consistency. Providers are responding by standardizing procedures, expanding localized service presence, and investing in training pipelines that reduce dependency on scarce specialized talent.
Cost architecture is also being reshaped by warranty-backed refurbishment and reconditioning models. When an upgraded or restored unit is delivered with a new-machine warranty, the service transaction shifts from uncertainty to risk-managed performance. This structure supports higher customer confidence and can justify more comprehensive service bundles, but it also requires disciplined quality control and parts traceability. Organizations that can align labor efficiency, component quality, and warranty assurance will capture stronger retention and more stable revenue streams.
PW Consulting
Competitive Landscape and Leading Strategies
The market remains relatively fragmented at the top, with a limited concentration of share among leading providers. This fragmentation reflects the diversity of dryer types, application contexts, and regional service requirements. Yet the leaders share a common strategic thread: they extend beyond transactional repair into capability-rich service ecosystems that combine field execution, parts availability, technical training, and standardized quality administration.
FEECO International exemplifies a capability-focused positioning centered on rotary dryer support across multiple industries. Its service scope spans preventive maintenance, repair, rebuilds, retrofits, and replacement parts, with specialized field work such as alignment, seal replacement, gear and trunnion service, and drum shell repairs. The emphasis on certified field teams and cross-industry applicability signals a strategy built on technical breadth and regulatory-aware execution. In practical terms, this approach allows the provider to serve operations where dryer performance directly affects processing continuity and safety compliance.
Industrial Kiln & Dryer Group has cultivated a leadership position by combining field service with engineering support and training. Its offering includes installation, alignment, emergency and planned repair, maintenance, and new or reconditioned parts for rotary dryers and kilns, with support for all OEM brands. The integration of 3D modeling, specialized tooling, and structured training programs suggests a differentiation strategy rooted in precision, repeatability, and capability transfer. By investing in know-how dissemination, the organization builds long-term customer reliance rather than one-off service events.
Prime Field Service Corp has pursued a globally deployable model with localized execution. Its service portfolio covers repair, rebuild, installation, retrofitting, and maintenance for rotary kilns and dryers, supported by machining capabilities and ISO-qualified procedures. The combination of global reach, machining depth, and standardized process control is strategically important for multinational operators that need consistent service quality across sites. This model aligns well with customers seeking scalable support without sacrificing procedural rigor.
Semiconductor Part Refurbishment Repairs Market
In the commercial laundry space, Consolidated Laundry Machinery and Alliance Laundry Systems illustrate divergent but complementary pathways. CLM focuses on industrial tumbler dryers with on-site and in-plant upgrading and refurbishing services, emphasizing downtime reduction and warranty-backed completion. This positions the company as an asset-upgrade partner where customers value performance restoration and risk mitigation in a single engagement. Alliance Laundry Systems, through its distribution network, emphasizes brand-agnostic repair, installation, preventive maintenance, and genuine parts supported by a sizable technician network and worldwide distributors. Its recent service network update reinforced the importance of factory-trained support and rapid parts-backed response. Both models highlight a shared reality: service credibility increasingly depends on trained personnel, parts authenticity, and consistent field execution.
Residential and multi-site commercial players such as Mr. Appliance and Whirlpool Corporation’s authorized service network demonstrate the importance of scale, brand alignment, and parts supply reliability. Their service models center on replacing critical components such as thermostats, belts, and coils, with broad coverage across electric and gas dryer types. For laundromats, hotels, and residential operators, the value proposition rests on dependable response, recognizable service standards, and streamlined parts replacement. These players benefit from established franchise or authorized provider structures that support geographic coverage and customer trust.
Taken together, the competitive landscape is evolving along three axes. One is integration, as providers combine repair, refurbishment, training, and digital or engineering support to deepen customer relationships. A second is specialization, where companies build advantage around certified safety practices, machining capability, or application-specific expertise. A third is network expansion, with service organizations extending local presence and technician capacity to reduce response times and improve coverage reliability. New entrants face meaningful barriers in specialized field service, particularly where certification, parts access, and technical reputation are prerequisites for trust. At the same time, consolidation remains plausible in regions where fragmented providers can be combined into broader coverage platforms with stronger logistics and training backbones.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the continued migration from reactive repair to predictive and preventive service architectures. As condition monitoring becomes more accessible and service teams accumulate diagnostic data, providers will be able to anticipate failure modes earlier and structure maintenance around usage patterns rather than breakdowns. This creates opportunities for subscription-style service contracts, tiered coverage, and performance-linked pricing, especially in commercial and industrial settings where uptime is directly tied to revenue.
The second trend is the growing importance of warranty-backed refurbishment as a commercial differentiator. Customers are increasingly willing to commit to upgraded or reconditioned equipment when the service provider assumes performance risk through a new-machine-style warranty. This model encourages deeper refurbishment engagements and can support premium pricing, but it also demands disciplined quality assurance, traceable parts sourcing, and consistent field execution. Providers that can operationalize this risk transfer will stand out in a market where trust and reliability are central purchase criteria.
The third trend is geographic and capability rebalancing. As organizations seek faster response and more predictable service costs, local or regional service presence will become more valuable, particularly where specialized labor and parts logistics have historically constrained performance. This may encourage network expansion by established providers and selective partnerships by manufacturers seeking broader coverage. At the same time, labor availability and certification requirements will remain a binding constraint, making training pipelines and workforce development strategically important rather than merely operational concerns.
Worldwide Electrical Transformer Repair Market
Potential risks should not be underestimated. Cost volatility in skilled labor, uneven regulatory expectations across regions, and variability in parts quality can erode margin and service consistency. Macroeconomic pressure may also shift procurement toward the lowest short-term cost, delaying investment in preventive or warranty-backed service models. Providers and buyers alike will need to manage these uncertainties through standardized procedures, clear service-level definitions, and disciplined capacity planning.
Actionable Recommendations for Decision-Makers
For Manufacturers and Equipment Owners
Treat dryer service strategy as a lifecycle decision rather than a maintenance afterthought. Prioritize providers that combine certified field expertise, standardized repair procedures, and clear warranty or performance assurance for refurbishment work. Where equipment fleets are mixed, evaluate brand-agnostic service coverage and rapid-response capabilities to reduce downtime risk across asset types.
For Investors and Strategic Buyers
Focus on service organizations with defensible capabilities: certified technical teams, machining and reconditioning depth, training infrastructure, and documented quality processes. Business models that can convert episodic repairs into recurring service relationships, or that can support warranty-backed refurbishment with disciplined quality control, are better positioned for durable margin expansion. Geographic coverage, technician scalability, and parts supply reliability should be assessed as core value drivers.
For Procurement and Operations Leaders
Shift evaluation criteria from unit cost to total cost of ownership, response reliability, and performance assurance. Ask for documented repair procedures, parts traceability, and clear warranties on refurbished or upgraded units. Where possible, consolidate service relationships to improve accountability, reduce coordination overhead, and strengthen negotiating leverage around response times and preventive maintenance scheduling.
The market’s trajectory will reward organizations that act on these structural shifts early. For those seeking deeper segmentation data, regional dynamics, and customized strategic pathways, the full PW Consulting report provides a more granular view of the commercial landscape and the service models likely to outperform over the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Dryer Refurbishment Repair Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


