



Mountain Protection Net Market: Why 6.4% CAGR Through 2032 Signals Strategic Shifts in Global Safety Infrastructure

Navigating the Worldwide Mountain Protection Net Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide mountain protection net market has established itself as a critical infrastructure component, reflecting the growing intersection of safety, engineering, and environmental resilience. From 2020 to 2025, the market expanded from 480.15 million USD to 652.48 million USD, demonstrating sustained growth even amid broader economic uncertainties. This trajectory underscores a fundamental shift: mountain protection systems are no longer peripheral safety add-ons but integral elements of infrastructure planning across transportation, mining, and energy sectors. The forward-looking period from 2026 to 2032 projects continued expansion, with revenues anticipated to reach 1008.64 million USD by 2032. This corresponds to a compound annual growth rate of 6.42 percent, signaling steady, compounding demand rather than speculative growth.
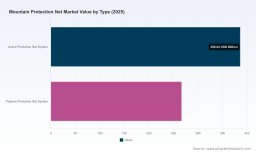
Several structural forces define this market. Demand is distributed across transportation infrastructure, mining operations, hydropower and utilities, and residential and urban development, each with distinct risk profiles and procurement cycles. Regionally, activity spans Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, reflecting both developed-market infrastructure maintenance and emerging-market construction surges. The active protection net segment commands the larger share of revenue, while passive systems maintain significant relevance for long-term slope stabilization and lower-energy hazard zones. Market concentration remains moderate, with the top three companies accounting for 38.45 percent of revenue and the top five reaching 52.12 percent, indicating room for both established leaders and specialized challengers.
Camouflage Netting Market
Despite this growth trajectory, the industry faces three defining challenges. First, raw material volatility has introduced significant cost uncertainty. High-tensile steel wire, the core component of mountain protection nets, represents 60 to 70 percent of final product costs. During recent supply chain disruptions, steel wire prices experienced increases of 25 to 30 percent, compressing margins and forcing manufacturers and buyers to reconsider pricing models, inventory strategies, and contract structures. Second, the regulatory and certification environment continues to tighten. European guidelines such as ETAG 027, now transitioning to EAD 340059-00-0106, require rigorous full-scale testing protocols, including MEL and SEL impact tests on deformable barriers. Compliance is not optional; it is a market access requirement, and the cost of testing, certification, and documentation creates barriers for smaller players while reinforcing the position of firms with dedicated testing infrastructure. Third, the market is experiencing a geographic and application-level divergence. Infrastructure development in mountainous regions is accelerating, but so are requirements for highways, railways, and mining safety. This divergence means that standardized, off-the-shelf solutions are increasingly insufficient; buyers expect systems calibrated to site-specific geology, energy thresholds, and failure modes.
Key Drivers Shaping Market Dynamics
The market's direction is being shaped by four interconnected drivers: technological evolution, regulatory momentum, demand-side transformation, and supply chain restructuring. Each driver carries distinct implications for manufacturers, investors, and procurement teams.
Technological innovation remains the most visible catalyst. The frontier has moved beyond basic rockfall netting toward engineered, dynamically tested systems capable of absorbing extreme impact energies. Recent testing milestones illustrate this shift. In June 2025, a rockfall barrier achieved a world record by absorbing more than 12,500 kJ from a 25-ton block impacting at 115 km/h, validating the potential of flexible steel systems to handle high-energy events previously addressed only by rigid structures. Equally significant is the push toward multi-impact validation. By October 2025, multiple-impact testing on flexible rockfall protection barriers advanced, including simultaneous impacts on the ROCCO system. This matters because real-world hazard scenarios rarely involve single, isolated events; repeated impacts, progressive deformation, and cumulative fatigue increasingly define the performance expectations of engineers and insurers. In February 2026, a Ringnet-type rockfall protection barrier successfully stopped a boulder on the Basque coast, protecting traffic and demonstrating how laboratory-validated systems translate into operational resilience in live environments. These developments are not isolated technical achievements; they are reshaping procurement criteria. Buyers now ask for documented energy absorption capacity, multi-impact behavior, and field-proven reliability, which elevates the importance of testing infrastructure and certification portfolios.
Regulatory and standardization trends reinforce the technology trajectory. The continued application of ETAG 027, transitioning to EAD 340059-00-0106, anchors the European market in full-scale testing and certification expectations. The guideline requires deformable barriers to undergo MEL and SEL impact tests, creating a common benchmark for performance comparison. This standardization has two effects. First, it reduces ambiguity for cross-border procurement, enabling specifiers to compare systems against shared criteria rather than proprietary claims. Second, it raises the compliance burden, favoring companies that can invest in 1:1 scale testing facilities and maintain ongoing certification documentation. Manufacturers routinely conduct testing at sites such as the Styrian Erzberg in Austria to validate systems against rockfall energies at and beyond 12,500 kJ. This is not merely a technical exercise; it is a strategic asset that supports sales cycles, insurance negotiations, and public-sector tenders where demonstrated compliance is a prerequisite.
Demand-side behavior is evolving as infrastructure expansion intersects with risk awareness. Increasing development in mountainous regions, combined with stricter safety regulations for highways, railways, and mining, is driving demand for certified high-tensile steel mountain protection nets. This is visible in the breadth of applications: transportation corridors require systems that can protect traffic and maintain operational continuity; mining operations need mitigation for slope instability and debris movement; hydropower and utilities seek protection for assets that are both expensive and difficult to replace; and residential and urban development in hazard-prone zones increasingly demands visible, certified mitigation measures. Importantly, demand is not purely regulatory. Insurers, operators, and public agencies are increasingly treating protection systems as risk-management investments with measurable ROI in avoided downtime, reduced liability, and extended asset life. This reframing shifts the conversation from cost minimization to performance assurance, which benefits suppliers that can articulate reliability, testing evidence, and lifecycle value.
Supply chain and cost structure changes add another layer of strategic complexity. High-tensile steel wire price volatility, with increases of 25 to 30 percent during recent disruptions, has forced a re-examination of procurement timing, inventory buffers, and supplier diversification. Because steel wire constitutes 60 to 70 percent of final product costs, even modest price swings can materially affect project economics. In response, some manufacturers are adjusting contract terms, exploring forward sourcing, and emphasizing design efficiencies that reduce material intensity without compromising performance. For buyers, this environment rewards early engagement, transparent cost breakdowns, and partnerships with suppliers that can demonstrate supply continuity and stable quality. The supply chain dynamic also favors manufacturers with integrated capabilities, from wire processing to mesh fabrication to system installation support, because integration can reduce exposure to intermediate market fluctuations and improve overall lead-time predictability.
Competitive Landscape and Leading Strategies
The competitive field combines long-established European specialists with growing manufacturing capacity in Asia, creating a landscape defined by performance credibility, geographic reach, and cost positioning. The market's moderate concentration, with the top three players at 38.45 percent and the top five at 52.12 percent, suggests that leadership is earned through differentiated capabilities rather than pure scale.
PW Consulting
Several companies illustrate distinct strategic positions. Geobrugg AG, based in Romanshorn, Switzerland, has built a reputation around high-tensile steel wire mesh systems and rockfall protection nets and barriers for slope stabilization and mountain hazard mitigation. Its recent activity signals a deliberate strategy centered on testing leadership, field validation, and knowledge dissemination. The company's world record absorption of over 12,500 kJ from a 25-ton block at 115 km/h, combined with multiple-impact testing on the ROCCO system, positions it around performance documentation. Field deployment on the Basque coast and participation in GEO-Summit 2025 under the theme "From Risk to Resilience" reinforce a narrative of engineering credibility and operational resilience. The Technical Conference 2025 in Guatemala, drawing 63 engineers from multiple Latin American countries, also reflects a push into regional knowledge building and relationship development, particularly relevant where infrastructure growth and hazard exposure are both rising.
Maccaferri S.p.A., headquartered in Bologna, Italy, offers a broader system portfolio that spans rockfall protection nets, dynamic barriers, drapery systems, and Mac.RO™ solutions for active and passive mountain protection. Its strategic emphasis appears to be comprehensive application coverage and integrated slope management, appealing to specifiers who want a single supplier capable of addressing multiple hazard types and deployment configurations. Trumer Schutzbauten GmbH, based in Oberndorf, Austria, manufactures flexible rockfall protection nets, Omega-Net systems, high-tensile slope meshes, and barriers certified to ETAG 027/EAD standards. Its positioning rests on certification alignment and flexible system options, which matters in European and export markets where compliance documentation is a gating factor. Tensar International, with global operations from Atlanta, Georgia, USA, provides geosynthetic rockfall netting and slope protection systems integrated with stabilization solutions, emphasizing the combination of netting and broader slope engineering for highway and mountain applications.
On the supply and cost side, manufacturers from China are expanding their role. Hebei Xinjuyuan Protective Net Engineering Co., Ltd. and Wanzhi Steel, both based in Hebei, China, produce rockfall netting, high-tensile steel meshes, slope protection nets, galvanized and stainless steel options, and wire rope nets, with monthly output supporting global exports. Hesly Group / HeslyFence similarly produces high-tensile steel wire mesh and rockfall protection nets for slope and mountain applications. These players contribute scale, cost flexibility, and export capacity, which can be attractive for large-volume projects and price-sensitive markets. At the same time, their competitive challenge lies in matching the testing documentation, certification alignment, and field-validation narratives that increasingly guide specification in regulated markets. Other notable participants, including RUD Ketten Rieger & Dietz GmbH u. Co. KG in Germany, Pfeifer Isofer AG in Switzerland, Maeda Kosen Co., Ltd. in Japan, and Geoquest, part of the Reinforced Earth Group with a global footprint from France, add further specialization. RUD focuses on components and systems for heavy-duty mountain applications; Pfeifer Isofer supplies rockfall protection netting and related steel wire systems; Maeda Kosen manufactures high-tensile rockfall protection nets and geosynthetic solutions for natural hazard mitigation; and Geoquest engineers rockfall protection nets, drapery systems, and combined soil nailing solutions for mountain slope stabilization. This breadth indicates a market where differentiation can come from components, integrated systems, geosynthetic combinations, or regional service networks.
The competitive evolution points toward both consolidation and segmentation. Consolidation is plausible among players seeking to combine testing infrastructure, geographic sales coverage, and installation capability into more complete value propositions. Segmentation is equally likely, as different applications and regions prioritize different attributes: some buyers emphasize certified energy absorption and multi-impact performance; others prioritize cost, lead time, or local support. New entrants are most likely to succeed by targeting a specific niche—such as a particular energy class, a regional compliance framework, or an integrated geosynthetic-plus-netting solution—rather than competing broadly on price alone. For decision-makers, the practical implication is that supplier selection should align with project risk profile, certification requirements, and total lifecycle cost rather than headline unit price.
Future Trends and Strategic Implications
Looking ahead three to five years, three trends appear especially consequential. The first is the normalization of extreme-energy, multi-impact validation as a procurement baseline. The June 2025 record absorption of over 12,500 kJ and the October 2025 multiple-impact testing milestone are early indicators of a broader shift. As more systems are tested and documented against these more demanding scenarios, specification language will increasingly reference energy classes, deformation behavior, and cumulative impact performance. Commercial opportunity lies with suppliers that can provide transparent, comparable evidence across these dimensions, and with buyers who use such evidence to right-size solutions rather than over-specify or under-protect.
The second trend is geographic demand migration combined with regional compliance differentiation. Infrastructure development in mountainous regions is expanding, and stricter safety regulations for highways, railways, and mining are amplifying demand for certified high-tensile steel mountain protection nets. Yet compliance expectations differ by market. European projects will continue to be shaped by EAD-aligned testing and certification; other regions may adopt their own acceptance criteria or rely on international benchmarks. The practical outcome is a market where global manufacturers must manage a portfolio of region-specific documentation, testing arrangements, and support capabilities, while buyers benefit from clearer comparative frameworks when they exist.
The third trend is cost and supply chain recalibration. With high-tensile steel wire representing 60 to 70 percent of final product costs and having experienced price increases of 25 to 30 percent during recent disruptions, both suppliers and buyers will increasingly value predictability. This may drive more forward sourcing, longer-term agreements, design optimization to reduce material intensity, and greater interest in suppliers with integrated manufacturing and inventory management. A related risk is that sustained input-cost pressure could push some smaller or less-integrated players out of certain segments, subtly reshaping competition over time.
Worldwide Rockfall Barrier Market
These trends carry risk as well. If steel price volatility persists, project economics and margin structures will remain unstable. If testing and certification requirements continue to expand, time-to-market and compliance costs may rise, potentially slowing entry for newer players. And if demand growth is uneven across regions and applications, companies with broad but shallow portfolios may struggle compared with those that can concentrate on high-growth, high-certification segments. The opportunity for resilient strategies lies in treating performance evidence, compliance readiness, and supply continuity as core commercial assets rather than operational details.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to convert testing and certification capability into a distinct market position. Documented energy absorption, multi-impact results, and field deployments should be organized into clear, comparable narratives that help specifiers evaluate options quickly. Where cost pressure is high, design efficiency and integrated manufacturing can protect margins without sacrificing performance. For investors, the market's 6.42 percent CAGR through 2032 suggests durable growth, but value creation will likely concentrate among companies with credible performance documentation, regional compliance readiness, and the ability to manage steel-cost volatility. Due diligence should therefore weigh testing infrastructure, certification status, and supply chain resilience alongside revenue trends. For procurement teams and project owners, the most effective approach is to define acceptance criteria early, request comparable evidence across energy classes and impact scenarios, and evaluate total lifecycle value rather than initial price alone. Early engagement with suppliers that can demonstrate both compliance and supply continuity can reduce project risk in a market where raw material volatility and certification requirements are both persistent factors.
Detailed segmentation data, company-level comparisons, and customized scenario analysis can sharpen these decisions further. For those evaluating market entry, capacity expansion, or major procurement programs, the full research report provides deeper breakdowns and tailored guidance to support more precise planning.
For detailed analysis of this topic, please visit the official page: Worldwide Mountain Protection Net Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


