



Vanadium Pentoxide Market: How 21.45% CAGR Reshapes Electrolyte Supply

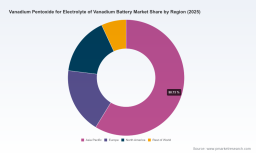
Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market: Strategic Trends and Commercial Opportunities
Market Landscape and Critical Challenges
The global market for vanadium pentoxide (V2O5) serving electrolyte applications in vanadium redox flow batteries (VRFBs) has transitioned from a niche materials segment to a structurally significant pillar of grid-scale energy storage. Valuation data from 2020 through 2025 shows a compounding growth trajectory that moved from approximately $345 million in 2020 to roughly $893 million in 2025. The forward path extends through 2032, with market size projected to reach nearly $3.5 billion by the end of the forecast period. This expansion reflects a compound annual growth rate of 21.45%, positioning the sector among the faster-scaling chemical supply chains tied to clean energy infrastructure.
Such velocity is not merely a function of incremental demand; it signals a structural realignment in how long-duration storage is sourced, financed, and deployed. Yet the same forces that accelerate revenue creation also introduce friction. The market currently navigates three interconnected challenges that will define competitive outcomes over the next several years.
First, purity standardization remains fragmented across procurement channels. While certain grades of vanadium pentoxide meet commercial specifications for electrolyte synthesis, the absence of universally harmonized quality benchmarks creates variability in downstream performance, testing costs, and supplier qualification cycles. Buyers often face trade-offs between cost efficiency and electrochemical consistency, particularly when integrating electrolyte into larger battery systems that require multi-year operational guarantees.
Second, pricing volatility in the upstream feedstock cycle interferes with capacity planning and margin stability. Input costs for vanadium pentoxide are influenced by ore processing economics, by-product recovery from steel and refinery streams, and shifting trade dynamics. When feedstock prices compress, producers may delay capital deployment or scale utilization unevenly. Conversely, when pricing rebounds, customers weigh inventory strategies against long-term offtake commitments, squeezing the predictability that large storage developers require for project financing.
Third, the relationship between raw material supply and specialized electrolyte manufacturing is tightening, but not uniformly. Capacity expansions in electrolyte synthesis are outpacing in some regions while lagging in others, depending on permitting timelines, access to high-purity intermediates, and available offtake structures. This unevenness can create bottlenecks for project developers who must synchronize battery equipment delivery, electrolyte supply, and commissioning schedules.
Key Drivers of Market Momentum
The decisive forces shaping this market operate across technology, policy, demand behavior, and supply chain architecture. Their convergence explains why the segment is expanding at a pace that traditional chemical markets rarely achieve.
Technical Pathways in Purity, Electrolyte Architecture, and Recycling
The industry is moving beyond treating vanadium pentoxide as a commodity input and toward engineering it as a performance-critical component of the electrolyte system. High-purity grades are gaining preference in applications where cycle life, ion stability, and contamination control directly influence total cost of ownership. At the same time, technological efforts are broadening the range of acceptable feedstocks by improving purification processes. This matters because it creates a route to lower-cost inputs without sacrificing electrolyte quality, providing flexibility in a market where upstream availability can vary by region and trade condition.
A parallel trend is the growing emphasis on electrolyte recycling and closed-loop stewardship. As deployed VRFB systems age, reclaiming vanadium from used electrolytes offers a supplementary supply channel and supports long-term sustainability narratives. The commercial relevance lies in reducing dependency on virgin material cycles and improving project economics for operators who plan for multi-decade asset life.
Policy, Incentives, and Standards Development
Electrolyte demand is heavily conditioned by how storage is treated within energy policy and procurement frameworks. In multiple jurisdictions, long-duration storage is increasingly viewed as a complement to intermittent renewable generation, prompting incentive structures, capacity mechanisms, and procurement rules that favor technologies capable of extended discharge and repeated cycling. Vanadium-based storage fits that profile, and policy architecture that rewards duration, reliability, and domestic manufacturing can disproportionately benefit electrolyte supply chains.
At the same time, standards activity is intensifying. Ongoing work under international standardization bodies to align quality control requirements for VRFB electrolyte is significant because consistent specifications lower transaction risk, simplify supplier qualification, and enable larger-scale procurement. Where standards remain uneven, project developers may encounter additional testing, acceptance criteria, and documentation burdens that slow deployment. Harmonization would not only reduce friction; it would also raise the addressable market for suppliers capable of demonstrating repeatable purity and process control.
Demand-Side Shift Toward Utility-Scale and Long-Duration Storage
The demand narrative has shifted from experimental pilots to bankable utility programs and commercial-industrial deployments. Large storage projects are driven by grid stability requirements, renewable integration targets, and the economic need to shift or firm generation over longer durations. These applications create a procurement profile that values predictable performance and long service life more than short-term price minimization. That inclination favors electrolyte suppliers that can provide traceability, consistent specifications, and contractual structures aligned with project finance timelines.
Commercial and industrial storage adds another layer of demand diversity. Facilities seeking resilience, tariff optimization, and sustainability goals are evaluating storage options that can operate with minimal degradation over many cycles. This expands the addressable base beyond purely utility-driven procurement and encourages a broader ecosystem of equipment integrators, developers, and end users to engage with vanadium electrolyte supply.
Supply Chain Reconfiguration and Cost Dynamics
Supply chain strategy is becoming as important as raw material pricing. The upstream picture is shaped by primary mining outputs, by-product recovery from oil refining residues and spent catalysts, and titanomagnetite processing routes. When utilization rates are depressed, pricing may soften, but such periods can also set the stage for later tightening as demand absorption increases. Producers and electrolyte manufacturers are responding by aligning capacity investments with secured offtake, regionalizing supply where policy incentives support domestic production, and building processing flexibility that can accommodate feedstock variability.
Cost structures are also influenced by tariff and trade conditions. Import duties and temporary tariff adjustments can alter sourcing decisions, especially for specialized high-purity material. In markets where trade policy changes quickly, buyers and suppliers must consider not only baseline pricing but also the durability of sourcing arrangements under shifting customs frameworks. This adds a strategic layer to procurement: cost optimization must be weighed against supply continuity and regulatory predictability.
Competition Dynamics and Leading Strategies
The competitive field combines established vanadium producers, dedicated electrolyte manufacturers, and vertically integrated players that operate across the value chain. Differentiation increasingly depends on purity control, processing flexibility, regional supply strategy, and the ability to offer commercial models that align with customer risk preferences.
U.S. Vanadium LLC has positioned itself around high-purity vanadium pentoxide and ultra-high-purity electrolyte production, with capacity scale that supports large-volume electrolyte output. Its recent expansion into high-purity flake production highlights a strategy of broadening specialty vanadium chemical offerings while reinforcing the base needed for battery-grade materials. Support from defense-related logistics funding suggests an additional avenue of institutional alignment that can strengthen manufacturing resilience and supply assurance.
PW Consulting
Storion Energy operates with a distinct lens on domestic electrolyte production and feedstock adaptability. By converting mined and recycled vanadium oxides into high-quality electrolyte and partnering with Largo for supply, it illustrates how purification technology can unlock lower-purity feedstocks without compromising output quality. This approach is commercially relevant because it creates optionality in a supply-constrained environment and can improve margin resilience when primary material economics fluctuate.
Largo Inc. represents the upstream-to-downstream integration model. Through primary vanadium production and its joint venture activities in electrolyte supply, it connects mine output with downstream electrolyte delivery and leasing-oriented commercial structures. The relevance of this model lies in the way it links raw material availability with customer-facing supply arrangements, which can reduce uncertainty for buyers who want more structured access to electrolyte over time.
In China, multiple producers are expanding capacity and linking high-purity V2O5 output with electrolyte operations. LB Group’s commissioning of a large-scale electrolyte facility integrated with high-purity vanadium pentoxide output reflects the continuing scale-up of regional supply aligned with energy storage demand. Other Chinese manufacturers focused on high-purity vanadium pentoxide are strengthening the breadth of available supply for electrolyte applications, reinforcing the region’s role as a significant production center.
European and other international participants are building targeted electrolyte capacity and pursuing integrated or specialized production routes. Companies with operations aimed at European energy storage demand, as well as developers advancing vanadium resource and processing strategies, are contributing to regional diversification. This matters because geographic diversification can reduce concentration risk and offer customers more options for local supply, testing, and logistics.
Vanadium Redox Battery (VRB) Market
Several strategic patterns are becoming visible. One is the move toward vertical coordination, where producers seek to secure or control access to high-purity intermediates and electrolyte conversion capacity. Another is product differentiation through purity grades and processing sophistication rather than price alone, especially as utility-scale buyers place greater weight on reliability and documentation. A third is commercial model innovation, including leasing and structured supply arrangements that can make electrolyte access more predictable for storage developers.
The market is also likely to see a blend of consolidation and fragmentation. Larger integrated players may pursue partnerships, offtake alignment, or selective acquisitions to strengthen supply continuity. Simultaneously, smaller or specialized producers can compete by serving niche purity requirements, regional demand pockets, or flexible feedstock strategies. New entrants will need to demonstrate more than capacity; they will need to prove quality consistency, qualification speed, and commercial terms that fit long-duration storage project economics.
Outlook for the Next Three to Five Years
Three trends are likely to shape the market trajectory through the end of the decade. The first is a continued shift in buyer preference toward high-purity, specification-controlled electrolyte supply. As more large storage projects move from planning to commissioning, qualification cycles will increasingly reward suppliers that can demonstrate process stability, traceability, and repeatable purity levels. This should reinforce the premium associated with grades that can meet stringent application requirements and broaden the opportunity for producers that invest in quality assurance as a competitive asset.
The second trend is capacity expansion becoming more targeted and regionally differentiated. Rather than uniform global scale-up, capacity growth will likely concentrate where demand visibility, policy support, and feedstock access converge. That concentration can create pockets of strong supply availability alongside areas where buyers face longer lead times or higher logistics complexity. For companies planning participation, the strategic task is to match supply expansion with credible offtake or contractual structures that reduce exposure to demand timing risk.
The third trend is price and supply cycle recalibration. After periods of depressed utilization and softer pricing, market conditions are projected to tighten as electrolyte demand accelerates and supply remains constrained in certain channels. If this unfolds, producers with secured intermediate supply, flexible processing, and strong customer relationships will be better positioned to capture value. Buyers, meanwhile, may need to balance spot purchasing with longer-term arrangements to protect project schedules and cost predictability.
Opportunities will be strongest for participants who can connect material quality with commercial reliability. That includes electrolyte manufacturers able to integrate multiple feedstock routes, producers with clear paths to high-purity output, and suppliers offering structured supply or leasing models that reduce upfront uncertainty for storage developers. The main uncertainty lies in the pace and uniformity of standards adoption, the durability of trade and tariff conditions, and the timing of demand absorption relative to new capacity coming online. A market can expand rapidly and still experience local imbalances if procurement, permitting, and production do not stay synchronized.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to convert capacity expansion into competitive advantage through purity control, feedstock flexibility, and qualification readiness. Expanding volume alone is unlikely to secure durable positioning if customers cannot easily validate quality or rely on supply consistency. Investments in process robustness, documentation, and downstream compatibility testing can shorten deployment timelines and improve long-term contract attractiveness.
For investors, the most relevant question is whether a company’s strategy is aligned with the demands of long-duration storage procurement. That means evaluating not only production scale but also offtake visibility, integration depth, regional exposure, and the ability to navigate trade or feedstock volatility. Business models that tie electrolyte supply to structured commercial terms may offer more predictable revenue characteristics than volume-only plays in a market still defining its demand rhythm.
For procurement and project developers, the practical focus should be on minimizing qualification uncertainty while protecting supply continuity. Diversifying supplier options, setting clear purity and testing expectations early, and considering longer-duration supply arrangements can reduce the risk of delays or cost surprises during project execution. In a market where demand is scaling quickly, early alignment with credible suppliers can matter as much as price negotiation.
Detailed segmentation data, company-level assessments, purity-grade dynamics, regional supply patterns, and commercial-model comparisons can help decision-makers narrow options and prioritize engagement. Access to granular research supports faster qualification decisions, sharper supply strategy design, and more informed capital allocation in a market where timing and specification alignment increasingly determine outcomes. Readers seeking a fuller breakdown of sub-segments, competitive positioning, and forward scenarios can explore the complete PW Consulting report for deeper data and tailored guidance.
Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


