



Microbolometer IR Detector Market: Why 8.5% CAGR and Asia Pacific's Rise Redefine Growth

Unlocking Strategic Value in the Global Microbolometer Infrared Detector Market
Market Overview and Core Challenges
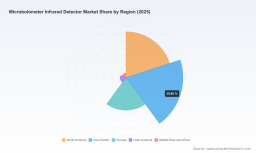
The worldwide market for microbolometer infrared detectors has entered a phase of robust expansion, driven by the growing integration of thermal imaging capabilities across diverse industrial and consumer sectors. Valued at approximately 815.2 million USD in the base year of 2025, the market has demonstrated consistent growth from its 2020 baseline of 542.15 million USD. Projections indicate a steady compound annual growth rate of 8.51 percent through the forecast period extending to 2032, signaling a market trajectory that favors sustained investment and technological maturation. This growth is not merely linear but reflects a deepening adoption curve where thermal sensing is transitioning from specialized defense and industrial applications toward broader commercial and consumer integrations.
Despite the positive revenue momentum, the industry faces significant structural headwinds that require strategic navigation. One primary challenge involves the regulatory environment surrounding technology transfer and export controls. Restrictions on high-performance detector modules, particularly those exceeding specific resolution or sensitivity thresholds, create complexity for global supply chains and limit market access for certain regions. Companies must balance compliance with the need to serve international customers, often requiring sophisticated legal and operational frameworks to manage technology flow without stifling growth.
PW Consulting
Supply chain vulnerability represents another critical pivot point. The production of Vanadium Oxide thin films, a dominant material type in detector manufacturing, relies on refining capacity that is geographically concentrated. This concentration introduces risk regarding raw material availability and pricing stability, potentially impacting production schedules and cost structures for downstream manufacturers. Diversification of material sourcing or investment in alternative material technologies becomes a strategic imperative to mitigate these exposure risks.
Furthermore, the market exhibits a moderate level of concentration, with a significant portion of revenue controlled by a limited number of key players. This landscape suggests that while entry barriers exist due to technology expertise and certification requirements, there is room for disruption through cost innovation or niche specialization. New entrants focusing on specific application verticals or cost-reduced architectures may find opportunities to capture share from established incumbents, particularly in price-sensitive segments where performance requirements are evolving rapidly.
Key Drivers of Market Growth
Technological innovation remains the most potent catalyst for market expansion within the microbolometer sector. Advances in pixel pitch reduction and noise-equivalent temperature difference (NETD) improvements are enabling detectors to become smaller, lighter, and more sensitive. For instance, recent developments have showcased modules with 12µm pixel pitches, allowing for higher resolution imaging in compact form factors suitable for next-generation security cameras and handheld devices. Simultaneously, improvements in thermal sensitivity, such as achieving NETD values below 40mK, enhance the reliability of detection in challenging environmental conditions. These technical breakthroughs expand the viable use cases, making thermal imaging viable for applications where size, weight, and power (SWaP) constraints were previously prohibitive.
Worldwide Infrared Focal Plane Detector Market
Policy and regulatory frameworks are also shaping demand dynamics, albeit in a dualistic manner. While export controls impose restrictions on high-end components, government initiatives aimed at bolstering domestic manufacturing and supply chain resilience are stimulating local production capabilities. Investments in semiconductor fabrication infrastructure, supported by legislative acts in major economies, encourage the development of domestic sensor production. This shift aims to reduce reliance on imported components for critical security and defense systems, driving demand for locally sourced microbolometer arrays and fostering a competitive environment among regional manufacturers seeking to qualify for government contracts.
On the demand side, there is a marked shift in consumer and enterprise behavior toward integrated sensing solutions. In the security and surveillance sector, the integration of thermal sensors into standard video surveillance systems is becoming more common to enhance threat detection capabilities regardless of lighting conditions. Similarly, the automotive industry is increasingly exploring thermal imaging as a complement to existing autonomous driving sensors. The ability of infrared detectors to identify pedestrians, animals, and obstacles in low-visibility scenarios offers a unique value proposition that addresses safety gaps in current Advanced Driver Assistance Systems (ADAS). This functional differentiation drives OEMs to evaluate thermal modules as a necessary addition to vehicle sensor suites.
Cost structure changes are further accelerating adoption. As manufacturing scales up, particularly in Asian production hubs, the average price of standard resolution detector cores has seen downward pressure. Reductions in unit costs make thermal technology accessible to a broader range of applications, including consumer electronics and cost-sensitive industrial monitoring. This democratization of technology allows smaller enterprises and new market segments to incorporate thermal sensing into their products, expanding the total addressable market beyond traditional high-budget sectors. However, manufacturers must balance cost reduction with performance consistency to maintain trust in critical applications where detection reliability is paramount.
Competitive Landscape and Leading Strategies
The competitive environment for microbolometer infrared detectors is characterized by a mix of established defense contractors, specialized sensor manufacturers, and integrators leveraging in-house capabilities. Companies such as Teledyne FLIR and Raytheon Technologies hold significant positions due to their deep expertise in uncooled infrared technology and strong relationships with government and industrial clients. Teledyne FLIR, for example, has focused on expanding its portfolio of small thermal cores for IoT and commercial sensing, exemplified by recent releases of modules with enhanced radiometry features. This strategy targets the growing need for distributed sensing in smart infrastructure and remote monitoring applications.
Defense-oriented firms like Lockheed Martin and BAE Systems continue to prioritize high-performance focal plane arrays for aerospace and night vision systems. Their strategic advantage lies in the ability to meet rigorous military specifications and integrate detectors into complex platforms. These players often benefit from long-term procurement contracts and the ability to customize solutions for specific mission requirements. Conversely, companies like ULIS (Lynred) have carved out a strong niche in high-volume production of Vanadium Oxide and amorphous silicon arrays, serving OEM customers who require cost-effective thermal cores for integration into their own product lines. Recent launches of detectors with improved sensitivity for low-SWaP applications highlight their focus on enabling compact commercial solutions.
In the commercial and security segment, players such as Guide Sensmart and Hikvision are driving adoption through aggressive product integration and cost competitiveness. Guide Sensmart has demonstrated next-generation pixel architectures at major industry exhibitions, signaling a focus on miniaturization for security cameras. Hikvision integrates proprietary sensors into thermal security and fire detection products, leveraging its massive distribution network to deploy thermal solutions in civilian safety applications. This approach contrasts with the component-focused strategy of pure-play detector manufacturers, as these integrators control both the sensor and the end-user system, allowing for optimized performance tuning and faster time-to-market.
The market landscape is evolving through both consolidation and fragmentation. On one hand, larger entities may seek to acquire specialized technology firms to broaden their IP portfolios or gain access to specific material technologies. On the other hand, the influx of new entrants offering differentiated features, such as ultra-low pixel pitches or specialized packaging, creates a fragmented environment in niche segments. Distributors like Boston Electronics play a crucial role in this ecosystem by providing access to a variety of global manufacturers, enabling research institutions and industrial users to source detectors without committing to large-scale production contracts. Excelitas Technologies further supports this by providing modular solutions for medical and industrial OEM integration, emphasizing flexibility and customization. The interplay between these strategies suggests a market where partnerships and supply chain agility will be as critical as raw technological performance in determining market share.
Future Trends and Commercial Opportunities
Looking ahead, the convergence of thermal imaging with artificial intelligence and edge computing emerges as a defining trend for the next three to five years. Detectors will increasingly be paired with onboard processing capabilities to analyze thermal signatures in real-time, reducing the need for constant data transmission to central servers. This shift enables smarter security systems that can distinguish between false alarms and genuine threats autonomously, as well as industrial inspection tools that can detect anomalies immediately. The commercial opportunity lies in developing software-enabled hardware solutions that offer value-added services, moving beyond selling raw sensor components to providing integrated detection platforms.
Another significant trend is the expansion of thermal sensing into consumer health and wellness applications. As the technology becomes more affordable and compact, opportunities arise for non-contact temperature screening and remote health monitoring devices. The pandemic accelerated interest in such tools, and sustained demand for home health monitoring could drive a new wave of consumer electronics incorporating microbolometer arrays. Manufacturers who can optimize sensors for low-power consumption and ease of integration into wearable or handheld consumer devices may capture emerging revenue streams. However, this expansion requires navigating varying regulatory standards for medical devices across different regions, which could slow adoption in certain markets.
Despite the positive outlook, uncertainty remains regarding material supply chains and geopolitical trade dynamics. The reliance on specific raw materials like vanadium, with refining capacity concentrated in limited regions, poses a risk of supply disruption or cost volatility. Additionally, ongoing export controls and trade restrictions could fragment the global market, forcing companies to maintain separate product lines or manufacturing sites to comply with regional regulations. Firms that proactively diversify their material sourcing or invest in alternative detector materials will be better positioned to manage these risks. Similarly, companies with a flexible manufacturing footprint that can adapt to shifting trade policies will likely maintain a competitive edge over those heavily reliant on single-region production for global distribution.
Strategic Recommendations for Decision Makers
For manufacturers operating in this space, prioritizing supply chain resilience is essential. Diversifying raw material sources or investing in recycling and recovery processes for critical elements can mitigate the risk of geopolitical or logistical disruptions. Additionally, focusing on value-added features, such as integrated processing or modular designs, can help differentiate products in a market where commoditization pressures are increasing. Collaborating with system integrators to co-develop solutions tailored to specific verticals may also unlock higher margins compared to selling standalone components.
Infrared Detector Market
Investors should look closely at companies demonstrating capabilities in scaling production while maintaining performance standards. The downward trend in component pricing suggests that volume growth will be a key driver of revenue, favoring players with efficient manufacturing processes and strong demand partnerships. Monitoring developments in material science, particularly alternatives to Vanadium Oxide, could also reveal long-term investment opportunities in firms that secure intellectual property around next-generation detector technologies. Assessing a company's compliance infrastructure regarding export controls is equally important, as regulatory missteps could severely impact international revenue streams.
Procurement teams and system integrators must balance cost considerations with performance requirements carefully. As detector prices decline, there is temptation to opt for lower-cost options, but ensuring reliability in critical applications remains paramount. Evaluating suppliers based on their ability to provide consistent quality, technical support, and supply continuity should outweigh short-term price advantages. Engaging with multiple suppliers to ensure redundancy and comparing total cost of ownership, including integration complexity and lifecycle support, will lead to more robust sourcing strategies. Access to detailed segmentation data and customized market intelligence can further refine these decisions, allowing stakeholders to align procurement strategies with specific project timelines and performance goals.
For detailed analysis of this topic, please visit the official page: Worldwide Microbolometer Infrared Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


