



Carbide Spray Coating Equipment Market: Why a 6.24% CAGR to $823M Means Real Competition Shifts

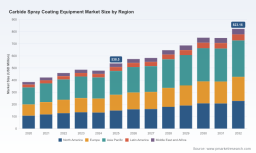
Global Carbide Spray Coating Equipment Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Snapshot and Core Challenges
The worldwide market for carbide spray coating equipment has demonstrated robust expansion over the past half-decade, transitioning from a fragmented industrial niche to a strategically critical enabler of asset durability and performance across heavy industry. Valued at approximately $385.4 million in 2020, the sector has grown to an estimated $538.5 million in 2025, reflecting a compound annual growth rate of roughly 6.24 percent through the forecast horizon to 2032. This trajectory is not merely a function of baseline industrial activity; it signals a structural shift in how manufacturers approach surface engineering, corrosion mitigation, and wear resistance in high-stress environments. The revenue base is projected to cross the $800 million threshold by the early 2030s, driven by sustained capital expenditure in asset-intensive sectors and the gradual replacement of legacy coating methods with high-velocity thermal spray technologies.
Despite the positive headline trajectory, the industry operates at a critical inflection point shaped by three interconnected challenges. First, the supply chain for tungsten and chromium carbide feedstocks has become increasingly volatile. Raw material constraints, particularly those originating from concentrated production hubs in East Asia, have triggered significant price escalations and forced equipment manufacturers and end-users to recalibrate cost models. The resulting margin pressure is reshaping procurement strategies and accelerating demand for alternative feedstock formulations and closed-loop material recovery systems.
Second, the skilled labor bottleneck is intensifying. Thermal spray operations require operators who can precisely manage powder feed rates, gas dynamics, standoff distances, and thermal profiles. Wage inflation in key manufacturing corridors has outpaced broader industrial averages, while apprenticeship pipelines remain underdeveloped. This talent gap is pushing equipment suppliers to embed greater automation, closed-loop control, and operator-assist features directly into their platforms, effectively shifting the value proposition from hardware hardware alone to integrated performance ecosystems.
Gas Dynamic Cold Spray Equipment Market
Third, regulatory and standardization frameworks are tightening the definition of acceptable coating performance. Updated durability testing protocols and revised quality benchmarks for thermally sprayed carbide layers on metallic substrates are forcing manufacturers to validate process consistency with greater rigor. Compliance is no longer a passive checkbox; it is becoming a competitive differentiator that separates suppliers capable of delivering repeatable, auditable coating outcomes from those relying on artisanal or highly variable application methods.
Key Growth Drivers and Structural Shifts
Technology Innovation and Deposition Efficiency
The most consequential driver of market evolution is the steady convergence of deposition technology, automation, and process analytics. High-velocity fuel and plasma-based systems have matured significantly, enabling denser carbide layer formation with improved adhesion and reduced porosity. Recent upgrades in high-pressure injection nozzles, optimized combustion chamber geometries, and closed-loop particle velocity monitoring have narrowed the historical gap between laboratory-grade coating quality and production-floor repeatability. Equipment manufacturers are increasingly packaging these advancements into modular architectures that allow end-users to switch between feedstock types, adjust spray parameters on the fly, and integrate robotic handling for complex geometries. The strategic implication is clear: coating equipment is no longer evaluated solely on throughput or footprint, but on the consistency and traceability of the coating outcome itself.
Policy, Regulation, and Standardization Pressure
Regulatory and standards activity is reshaping demand patterns in subtle but durable ways. Updated international specifications for thermal sprayed carbide coatings have elevated the baseline for durability verification, particularly in applications where failure carries high operational or safety costs. These developments are filtering down into procurement requirements across aerospace-adjacent suppliers, power generation operators, and heavy equipment manufacturers. At the same time, export control dynamics have introduced a new layer of complexity for cross-border equipment flows. Certain high-velocity spray platforms are now subject to tighter licensing scrutiny in dual-use contexts, which is encouraging regional equipment sourcing, localized service networks, and increased investment in domestic application engineering capabilities. Rather than stifling growth, these measures are incentivizing supply chain regionalization and deeper technical partnerships between equipment vendors and end-users.
Demand-Side Behavior and Asset-Longevity Economics
End-user behavior is increasingly governed by total-cost-of-ownership logic rather than upfront equipment price. In sectors where downtime is expensive and component replacement cycles are long, carbide coatings are being deployed earlier in the asset lifecycle as a proactive durability strategy rather than a reactive repair measure. Turbine components, valve trims, drill components, and high-wear industrial surfaces are seeing expanded adoption as operators seek to extend service intervals and reduce metallurgical wear under aggressive chemical or mechanical conditions. Aerospace-adjacent demand has been particularly influential, with engine efficiency mandates and higher operating temperatures pushing OEMs and MRO providers toward more advanced surface treatments that can tolerate thermal stress without compromising structural integrity. This demand-side shift is accelerating the migration from conventional spray methods toward systems that deliver higher deposition efficiency and more predictable metallurgical outcomes.
Supply Chain and Cost Structure Realignment
Cost structures across the equipment and coating value chain are undergoing a quiet but meaningful realignment. Feedstock price volatility has made material yield and overspray recovery economically significant, prompting manufacturers to invest in recovery systems, optimized powder morphology, and process control that reduces waste. Simultaneously, the rising cost of skilled labor is accelerating the business case for automated application cells, programmable manipulators, and integrated inspection workflows. Companies that can offer equipment together with feedstock management, parameter recipe libraries, and application support are capturing more of the economic value than those competing strictly on unit price. The result is a gradual shift from transactional equipment sales toward performance-based engagement models, where outcomes such as coating uniformity, reload frequency, and maintenance intervals become part of the commercial conversation.
Competitive Landscape and Leading Strategies
The competitive arena for carbide spray coating equipment is characterized by a moderate degree of concentration, with a handful of established players holding meaningful share while a broader tier of regional specialists and application-focused integrators competes on responsiveness, niche expertise, and total deployed cost. The market remains dynamic enough that leadership is determined less by scale alone and more by the ability to combine deposition technology, feedstock compatibility, and service depth into a coherent customer value proposition.
Global specialists with strong aerospace and energy pedigrees have built their positioning around high-pressure deposition platforms, process control, and integration into demanding manufacturing environments. Their advantage lies in documented performance in high-stakes applications, mature engineering support networks, and the ability to align equipment specifications with stringent durability expectations. These firms have increasingly emphasized system-level upgrades, demonstrating refined high-pressure platforms and automated application capabilities at industry forums, signaling a shift toward repeatable industrial throughput rather than bespoke, labor-intensive application.
Parallel to the global specialists, a group of technology-focused manufacturers has carved out strong positions by optimizing specific spray architectures for carbide deposition efficiency and industrial robustness. Their strategic emphasis tends to center on nozzle design, combustion stability, and hardware configurations that improve material utilization while maintaining the thermal profiles required for tungsten and chromium carbide adhesion. Product enhancements released over the past couple of years have focused on improving deposition consistency and expanding the practical operating envelope for industrial carbide coatings, appealing to buyers who prioritize throughput reliability and reduced process variability.
A third competitive vector is emerging around turnkey integration and automation. Equipment providers that bundle spray booths, robotic manipulators, powder handling, and environmental controls are targeting sectors where labor availability, floor space, and process repeatability constrain adoption. By demonstrating automated application cells in live industrial settings, these companies are making a compelling case that coating equipment can be deployed as a predictable production resource rather than a specialized craft operation. This is particularly relevant for automotive, steel, and paper industry applications where throughput consistency and operator safety carry significant economic weight.
The market is evolving along two simultaneous paths: consolidation among players seeking broader geographic reach and deeper aftermarket revenue, and fragmentation among specialists pursuing narrow application advantages or regional service intensity. New entrants are unlikely to succeed by replicating established spray hardware alone; they are more likely to gain traction by addressing underserved feedstock-formulations, integrating advanced process monitoring, or offering equipment-as-a-service models that lower the barrier to upgrading legacy lines. Competitive advantage is increasingly tied to lifecycle support, training ecosystems, and the ability to help customers navigate feedstock volatility and compliance requirements without sacrificing coating quality.
Future Outlook: Three Trends Shaping 2026–2032
The next three to five years will likely be defined by the maturation of automation, the hardening of compliance expectations, and the increasing economic importance of material efficiency. First, automated and semi-automated carbide spray cells will move from selective adoption to mainstream consideration in mid-volume industrial environments. As robotic handling, parameter presets, and inline verification become more accessible, the operational case for automation will strengthen even in settings that previously relied on experienced operators. This trend will favor equipment suppliers that can deliver repeatable outcomes with reduced dependency on specialized labor, and it will create aftermarket demand for software updates, recipe management, and service contracts.
Second, standards and export-control dynamics will continue to reshape procurement geography and partner selection. Buyers in regulated industries will place greater weight on documented process validation, traceable parameter records, and supplier capability to support regional compliance requirements. This environment rewards vendors with strong application engineering depth and penalizes those selling hardware without a clear support pathway. For end-users, it means sourcing decisions will increasingly factor in long-term assurance rather than initial price advantage.
PVD Coating Equipment Market
Third, feedstock economics will push the market toward higher material utilization and more disciplined process control. As carbide powder costs remain sensitive to supply constraints and geopolitical factors, companies that can demonstrate lower overspray, better recovery, and tighter control over deposition parameters will capture margin advantages. This creates opportunities for equipment configurations that integrate powder management, closed-loop feedback, and operator guidance tools, as well as for service providers that help plants optimize existing lines rather than replace them outright.
The principal uncertainties lie in the pace of feedstock price normalization, the trajectory of export and dual-use restrictions, and the speed at which labor shortages are mitigated through training or automation. Any significant relaxation in material availability could temporarily ease cost pressure, while tighter controls or sustained wage inflation could accelerate automation adoption faster than some suppliers are prepared to support. Forward-looking strategies should therefore stress flexibility, regional service readiness, and the ability to adapt equipment configurations to evolving feedstock and compliance conditions.
Strategic Recommendations for Decision-Makers
For equipment manufacturers and system integrators, the priority is to shift competitive positioning from hardware specification alone toward demonstrated coating consistency, automation readiness, and lifecycle support. Investing in closed-loop process control, recipe-based application workflows, and regional service coverage will strengthen resilience against labor constraints and feedstock volatility. Partnerships with feedstock suppliers and application engineering teams can also create differentiated offerings that help customers manage cost and compliance without sacrificing performance.
For investors and corporate strategy teams, the most attractive opportunities are likely to emerge in automation-adjacent upgrades, material efficiency solutions, and service-based revenue models rather than in undifferentiated hardware expansion. Monitoring the pace of regional equipment sourcing, the formation of integrated vendor-customer application programs, and the commercial impact of evolving standards will provide early signals of where value is shifting. Caution is warranted around exposure to markets that depend heavily on unrestricted cross-border equipment flows for high-performance platforms, given the regulatory uncertainty.
For procurement and operations leaders in end-user industries, the focus should be on evaluating total deployed cost and outcome reliability rather than sticker price. Requesting documented process validation, training pathways, and spare-parts and service commitments can reduce the risk of variability in coating performance. Aligning equipment selection with anticipated feedstock availability, internal labor capacity, and compliance documentation requirements will help secure longer-term operational stability.
PW Consulting
Detailed segmentation data, regional revenue splits, technology adoption curves, and company-level benchmarking are available in the full market research report, where the underlying figures and scenario analysis can be matched to specific procurement, investment, or product Roadmap decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Carbide Spray Coating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


