



H-Line Photoresist Market: How Positive Resists and Asia Pacific Fuel 2032 Outlook

Global H-Line Photoresist Market: Strategic Trends and Commercial Opportunities (2025-2032)
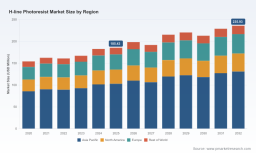
The worldwide H-line photoresist market has entered a phase of measured expansion, characterized by steady absolute growth alongside notable cyclical fluctuations. Valued at approximately $185.4 million in 2025, the market has grown from $154.2 million in 2020, reflecting a compound annual growth rate of 3.5 percent over the forecast horizon extending to 2032. This trajectory underscores a mature yet evolving landscape where incremental technological refinements and shifting application demands gradually reshape revenue streams. The market's composition reveals pronounced regional concentration, with Asia Pacific accounting for a substantial share of global consumption, followed by Europe and North America. Demand is broadly distributed across positive and negative tone formulations, with positive variants commanding a larger footprint due to their prevalence in high-volume packaging and display-related processes. Application-wise, power semiconductor fabrication, light-emitting diode and optoelectronics manufacturing, micro-electromechanical systems development, and consumer electronics assembly collectively drive volume, each segment responding to distinct performance and cost parameters. High market concentration further defines the commercial environment, with three leading suppliers capturing roughly two-thirds of total revenue and five dominant players accounting for over eighty percent of market value. This structure suggests entrenched competitive advantages, supply chain integration benefits, and established qualification pathways that continue to shape procurement behavior across industrial customers.
Despite this foundational stability, several structural challenges and inflection points are reshaping how participants navigate the market. One persistent tension lies in the interplay between mature process requirements and evolving regulatory expectations. The transition toward lower-volatile organic compound formulations and stricter solvent controls has forced manufacturers to recalibrate production protocols, testing regimes, and supply chain disclosures. Compliance costs are rising, and the burden falls disproportionately on suppliers without the scale to absorb incremental certification expenses or reformulate legacy chemistry without compromising linewidth fidelity. A second challenge stems from raw material volatility, particularly in specialty precursors and photoactive compounds whose pricing has exhibited upward pressure amid regional supply constraints and limited supplier diversification. These input cost swings compress margins for mid-tier producers and incentivize long-term contract renegotiation, pushing procurement teams toward multi-sourcing strategies that can dilute relationship depth but improve cost predictability. A third inflection point emerges from the geographic realignment of advanced packaging and power device manufacturing. As fabrication capacity expands beyond traditional clusters and new facilities come online in regions with varying infrastructure maturity, qualification timelines lengthen, technical support requirements intensify, and logistics networks face renewed stress. The market is no longer a static demand pool; it is a moving target where regional capability gaps, capacity additions, and shifting qualification priorities create both disruption and selective advantage.
Key Drivers Shaping Market Trajectories
Technological Innovation and Process Migration
Progress in H-line photoresist performance continues to be driven by the need for thicker, more uniform film deposition and improved etch resistance in non-critical lithography steps. As semiconductor packaging moves toward embedded structures, wafer-level interconnects, and power device architectures that demand high-aspect-ratio patterning, formulators have prioritized resists that maintain adhesion and dimensional stability under extended bake and develop cycles. Recent product introductions targeting high-aspect-ratio etching for power semiconductors illustrate this shift, showcasing formulations engineered to withstand aggressive processing while preserving sidewall profile integrity. At the same time, temporary bonding, sacrificial layer deposition, and sensor fabrication workflows are incorporating H-line materials where i-line or deep ultraviolet alternatives would be cost-prohibitive. This application-specific engineering reduces the pressure to migrate every process node to shorter wavelengths, preserving a viable role for 405 nm exposure in throughput-sensitive manufacturing environments. The result is a market where incremental performance gains rather than revolutionary substitution drive adoption, and where differentiation increasingly hinges on formulation resilience, defectivity control, and compatibility with downstream stripping and cleaning chemistries.
Worldwide EUV Resist Market
Policy and Regulatory Environment
Regulatory frameworks are exerting a quiet but persistent influence on formulation design, export practices, and facility operations. Environmental compliance mandates have begun to reshape solvent selection, pushing manufacturers toward lower-VOC architectures and more rigorous emissions management. Recertification efforts at manufacturing sites emphasize sustainability metrics that align with customer procurement standards, indicating that environmental performance is becoming a qualification factor rather than a peripheral consideration. At the same time, export-related compliance requirements for photoresist shipments have introduced additional documentation and formulation scrutiny, particularly for solvent content that intersects with broader chemical registration regimes. In parallel, trade measures applied to chemical imports in key regions have indirectly affected cost structures by altering procurement pathways for certain precursors and intermediates, prompting suppliers to reevaluate sourcing footprints and contract terms. These developments do not halt market growth, but they elevate the importance of compliance readiness, formulation flexibility, and transparent supply chain communication as competitive attributes.
Demand-Side Transformation
Customer behavior is shifting as end-use industries redefine their processing priorities. Power semiconductor demand continues to benefit from electrification trends, where robust packaging and device isolation requirements sustain volume for H-line materials used in wafer-level and thick-film processes. Optical and display-related manufacturing similarly maintains steady consumption patterns, driven by sensor integration, lighting platforms, and component miniaturization that rely on cost-effective patterning where H-line exposure remains practical. Meanwhile, microcontroller and micro-electromechanical system development keeps a consistent baseline of demand, especially in research and pilot production settings where accessibility, cost, and process simplicity outweigh the need for extreme resolution. A notable change on the demand side is the growing emphasis on supply assurance. Procurement teams increasingly value formulation consistency, lot-to-lot reproducibility, and technical support responsiveness, particularly when production ramps are tied to infrastructure build-outs or new product introductions. This shift rewards suppliers who can offer reliable qualification support, flexible packaging, and predictable delivery timelines, reinforcing the commercial value of established relationships and documented process compatibility.
Supply Chain and Cost Structure Dynamics
Cost pressures are intensifying as feedstock pricing exhibits intermittent spikes and supplier concentration in certain specialty inputs limits negotiation leverage. Phenol-based precursors and photoactive compounds have seen price movements influenced by regional availability and limited sourcing alternatives, embedding volatility into production economics. These dynamics compel manufacturers to balance inventory strategies, long-term agreements, and regional sourcing diversification to protect margins without disrupting customer supply. Capacity expansions in response to packaging-related demand have also altered the supply equation, with producers increasing output for legacy grades and reinforcing regional availability. However, capacity additions alone do not resolve cost sensitivity; they must be paired with yield optimization, waste reduction, and process efficiency improvements to translate volume growth into margin stability. For downstream customers, this environment elevates the importance of supplier financial health, production reliability, and transparent cost communication, particularly when multiple grades and custom formulations are required across different fabrication steps.
Competitive Landscape and Leading Strategies
The competitive environment remains defined by a small group of established suppliers with deep formulation expertise, broad application portfolios, and mature qualification networks. Japanese manufacturers continue to anchor a significant portion of global supply, leveraging integrated chemistry capabilities and long-standing relationships across packaging, power device, and display ecosystems. Their strategic positioning often centers on application-specific product lines that address thick-film patterning, high-aspect-ratio etching, and temporary bonding requirements, enabling customers to consolidate sourcing and reduce process variability. North American and European participants contribute differentiated value through specialized grades, research-oriented formulations, and regional technical support models that cater to microfabrication, sensor development, and laboratory-scale production. This multi-geography supplier base creates a market where scale advantages coexist with niche specialization, and where customers select partners based on a combination of performance reliability, qualification support, and regional availability rather than price alone.
Strategic differentiation has increasingly moved beyond basic product availability. Leading players are investing in formulation upgrades that address environmental compliance without sacrificing process window, targeting lower-VOC architectures and improved solvent management while maintaining linewidth consistency and adhesion performance. Product launches tailored to power semiconductor etching requirements reflect a deliberate focus on high-growth application pockets where process robustness translates directly into customer productivity. Capacity expansions for legacy grades signal a different strategic logic: securing supply for established demand streams, reducing lead-time risk, and reinforcing regional service levels in markets where packaging volumes are climbing. Certification and sustainability initiatives further strengthen commercial positioning by aligning manufacturing practices with customer procurement expectations, reducing compliance friction, and supporting long-term contract stability. These moves illustrate a landscape where competitive advantage is built through a combination of technical reliability, supply assurance, and regulatory readiness rather than volume growth alone.
Market structure appears likely to persist in a concentrated form, though with subtle evolution. Consolidation pressure may intensify among smaller suppliers who lack the scale to absorb compliance costs or the application breadth to compete across multiple end markets. At the same time, specialized participants can preserve relevance by focusing on research-grade materials, regional service depth, or niche process requirements where flexibility and technical support outweigh the benefits of large-scale sourcing. New entrants face meaningful barriers in qualification lead time, customer trust, and formulation complexity, yet opportunities remain in underserved application segments, alternative solvent systems, and region-specific supply arrangements that address localized demand patterns. The broader trend is toward a bifurcated environment: disciplined scale players compete on reliability and breadth, while focused suppliers compete on specificity and responsiveness. For customers, this structure rewards strategic supplier selection, multi-source planning for critical grades, and early engagement during process development to secure favorable qualification outcomes.
PW Consulting
Future Outlook: Trends and Commercial Implications (2026-2032)
The next several years are likely to be shaped by a combination of application-led demand growth, formulation modernization, and supply chain recalibration. One clear trend is the continued reinforcement of H-line materials in power semiconductor and advanced packaging workflows, where cost-effective patterning and thick-film performance remain valuable even as shorter-wavelength lithography expands elsewhere. This trend supports a commercial opportunity for suppliers that can demonstrate consistent etch resistance, sidewall control, and compatibility with high-aspect-ratio processes, especially as fabrication volumes scale in newly commissioned facilities. A second trend involves incremental formulation shifts driven by environmental and compliance expectations. Lower-VOC architectures, improved solvent management, and documented sustainability metrics are poised to become baseline expectations rather than differentiators, creating opportunities for manufacturers that can accelerate reformulation cycles without disrupting qualification timelines. A third trend concerns regional supply reconfiguration. As capacity additions and procurement diversification efforts continue, supply chains will likely become more regionally balanced, with qualified local or near-regional sources gaining preference for critical grades. This shift can reduce lead-time risk and improve service continuity, but it may also raise structural costs if duplication of capability and qualification overhead increase across geographies.
These trends carry embedded uncertainties. Raw material price volatility could compress margins if input costs rise faster than contract adjustment mechanisms allow. Regulatory changes affecting solvent content or chemical registration could introduce reformulation bottlenecks, particularly for products with tightly constrained performance requirements. Demand growth may prove uneven if certain end-markets face investment pauses or if packaging capacity expansions outpace near-term absorption. For commercial planning, these uncertainties argue for flexible sourcing strategies, early qualification engagement, and scenario-based volume forecasting that accounts for both application momentum and input cost exposure. The opportunity is not simply to capture growth, but to structure supply and formulation strategies that remain resilient when cost, compliance, or demand assumptions shift.
PHS Resin for KrF Photoresist Market
Actionable Guidance for Decision-Makers
For manufacturers and formulation suppliers, the priority is to strengthen differentiation where it matters most: process reliability, compliance readiness, and application-specific performance. Investing in lower-impact solvent systems, reinforcing quality consistency across production lots, and aligning technical support with high-growth applications such as power packaging and sensor-related processing can improve customer stickiness and protect margin under volatile input conditions. Capacity planning should be paired with yield and waste optimization so that volume increases translate into sustainable economics rather than temporary scale benefits.
For investors and strategic planners, the market rewards disciplined evaluation of supplier positioning rather than broad sector optimism. Focus on participants with strong qualification networks, application breadth across packaging and optoelectronics, and credible pathways to manage compliance-driven reformulation. Monitor capacity announcements and raw material sourcing strategies as early indicators of margin resilience, and assess whether regional supply shifts create durable service advantages or merely redistribute cost structures. In concentrated markets, competitive outcomes often hinge on operational execution and customer retention, making supplier stability a critical assessment criterion.
For procurement and sourcing leadership, diversification should be pursued with qualification feasibility in mind. Establishing backup sources for critical grades, engaging suppliers during process development, and securing transparent cost frameworks can reduce exposure to volatility and lead-time disruption. At the same time, maintaining deep relationships with proven partners can accelerate troubleshooting, minimize process variability, and support faster ramp readiness when production requirements change. Detailed segmentation data, regional supply mapping, and formulation-level scenario analysis can materially improve sourcing decisions, particularly when balancing cost, compliance, and supply assurance across multiple applications and geographies.
For detailed analysis of this topic, please visit the official page: Worldwide H-line Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


